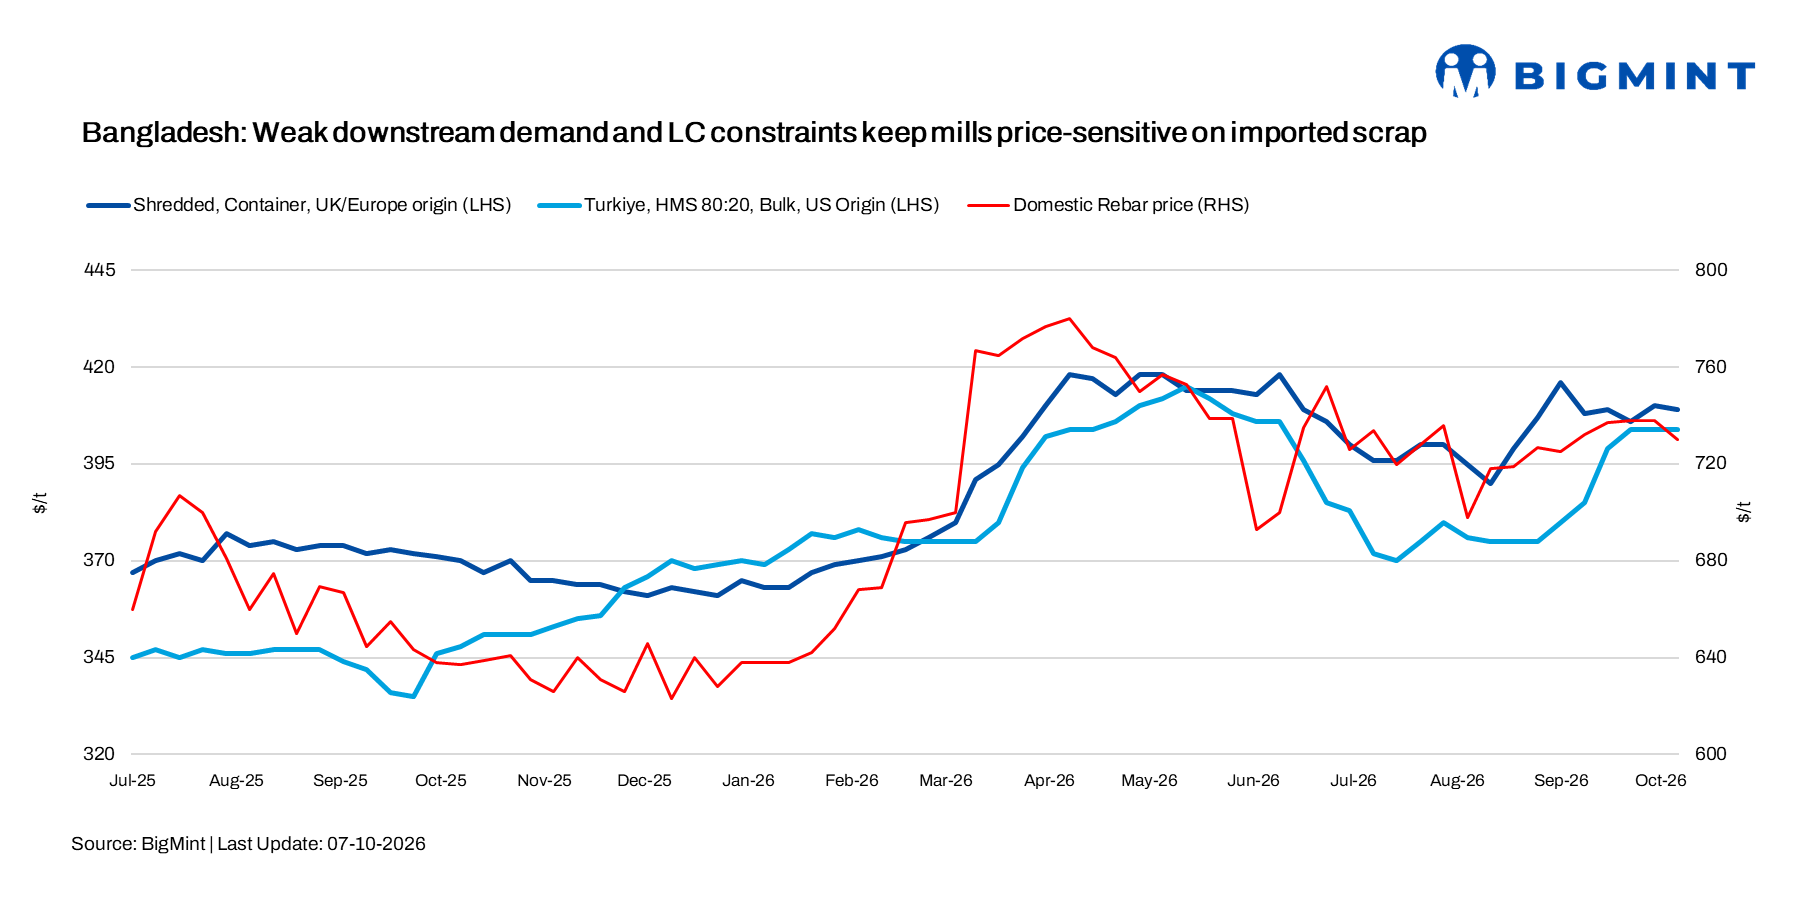
- Asian suppliers maintain higher offers on firm replacement costs
- Fresh bookings remain limited as buyers seek $8-10/t discounts
Bangladesh’s imported ferrous scrap market remained subdued during the week ended 7 October, as weak demand for semi-finished and finished steel products limited mill procurement. As per market insiders, buyers remained selective and continued to negotiate for lower prices, while letter of credit (LC) constraints restricted import activity and encouraged some mills to rely more on domestic scrap.
BigMint’s weekly assessments, CFR Chattogram
- European-origin containerised HMS 80:20: $375/t, up by $2/t w-o-w
- European-origin containerised shredded: $409/t, up by $3/t w-o-w
- Japanese-origin bulk H2: $396/t, inched up by $1/t w-o-w
- US-origin bulk HMS 80:20: $404/t, up $2/t w-o-w
Market scenario
A Southeast Asia-based trader said, “Malaysia-origin PNS offers were heard at around $415-420/t CFR Chattogram, while Malaysia-origin busheling was offered at around $425/t CFR Chattogram. Singapore-origin PNS offers were also reported as high as $430/t CFR Chattogram, although bids were still awaited.”
A Dhaka-based source informed that Australia-origin HMS 90:10 offers were at around $400/t CFR Chattogram, while PNS offers were heard at $405-410/t. PNS offers stood at around $410-415/t, while UK-origin shredded scrap was offered at $405-410/t CFR Chattogram.
Workable levels for UK-origin containerised PNS were reported at around $418/t CFR Chattogram, while Singapore-origin PNS was traded at around $420/t CFR Chattogram. However, fresh trading activity remained limited, with buyers selectively active and seeking discounts of around $8-10/t amid weakening demand.
A Chattogram-based international supplier said, “Recent trades from our side included 2,000 t of Panama-origin HMS 80:20 at $376/t CFR Chattogram and 1,000 t of Hong Kong-origin PNS at $415/t CFR Chattogram. Australia/New Zealand-origin HMS-PNS mix with less than 2% impurities was offered at $390-400/t CFR Chattogram, against bids of around $380-385/t, negotiable.”
Domestic market
Bangladesh’s domestic steel market remained slow, with subdued demand for both semi-finished and finished steel products. LC-related difficulties continued to restrict scrap imports, prompting mills to rely more on locally sourced material.
Local scrap prices were reported at around BDT 56,000/t ($455/t) for shipyard scrap, BDT 54,000/t ($438/t) for heavy scrap, BDT 53,000-54,000/t ($430-438/t) for light scrap, and BDT 40,000/t ($325/t) for tin/can bundles.
Rebar prices stood at BDT 80,000-84,000/t ($650-682/t) in Dhaka and BDT 89,000-91,000/t ($723-739/t) in Chattogram.
Outlook
Bangladesh’s imported scrap market is likely to remain rangebound and buyer-driven in the coming days. Mills are expected to cover immediate requirements and seek discounts, while domestic scrap availability will limit aggressive imports. LC availability and finished-steel demand will be the key triggers for any pickup in bookings. Until then, buying is likely to remain selective.
Leave a Reply