- Tight availability limits fresh spot trade
- Higher pellet prices provide upside support
India’s iron ore concentrate prices remained stable this week as tight material availability and higher pellet prices continued to support seller expectations, while adequate buyer inventories and resistance to elevated prices limited fresh spot-market activity. Sellers remained focused on clearing pending orders accumulated during the earlier supply constraints, with improved weather conditions helping dispatches gradually resume.
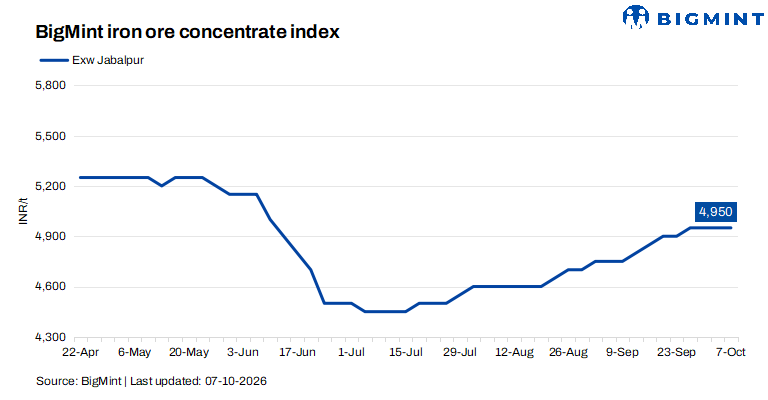
BigMint’s bi-weekly assessment for Fe 62% concentrate remained unchanged at INR 4,950/t ($52/t) ex-works on 6 October 2026. Seller indications ranged from INR 4,700/t ($49/t) to around INR 5,100/t ($53/t), while Fe 63% concentrate offers were heard at around INR 5,300/t ($55/t). The benchmark remained stable as supply tightness and firm pellet prices offset cautious buying sentiment.
Market participants said sellers were prioritising the dispatch of previously booked material rather than committing to new orders, as pending deliveries remain substantial. Although weather conditions have improved, allowing dispatches to pick up, sellers continue to face limited availability for fresh commitments. Meanwhile, buyers, holding stocks for around 15 days, are reluctant to chase higher prices, resulting in a largely stable market with some deals still under negotiation.
A Jabalpur-based seller told BigMint that “pending dispatches could take the entire month to complete, leaving limited scope for fresh deals in the near term. The seller added that while the broader market remains firm, buyers are yet to fully accept higher concentrate prices.”
Rationale
- One (1) trades were recorded in this publishing window, which were not taken into consideration. Therefore, this category received a 0% weightage.
- Nine (9) offers and indicative prices were heard, of which six (6) were taken into consideration as T2 trades, receiving 100% weightage.
Factors supporting market dynamics
- Raipur pellet price rise by INR 500/t ($5/t) w-o-w: PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% ± 0.5%) index for Raipur, rose by INR 500/t ($5/t) w-o-w to INR 11,800/t ($122/t) DAP Raipur on 6 October 2026, supported by tight spot availability, firm sponge iron and finished steel demand, and higher semis and long-product prices. Pellet offers increased by INR 300/t to INR 11,700-11,800/t ex-works on 5 October, marking the third hike and a cumulative increase of nearly INR 900/t in ten days, amid maintenance shutdowns at some local pellet plants.
- Odisha iron ore prices edge up by INR 50/t ($0.5/t): BigMint’s Odisha Fe 62% iron ore fines assessment increased by INR 50/t ($0.5/t) w-o-w to around INR 5,550/t ($57.6/t) ex-mines in the week ending 3 October 2026, supported by restricted availability and firm offers. However, buyers remained reluctant to procure at elevated levels, keeping spot-market activity subdued with no significant deals reported. Although rainfall has eased, mining and dispatches are yet to return to normal, continuing to constrain supplies.
Outlook
Iron ore concentrate prices are expected to remain largely stable in the near term, with sellers likely to prioritise pending order dispatches before taking on fresh commitments. Tight material availability and continued support from rising pellet prices could prevent any significant downside, while adequate buyer inventories and resistance to higher levels may limit further price gains.
Leave a Reply