- EU offers remain unchanged, buying interest remains subdued
- Middle East and Vietnam offers remain on hold
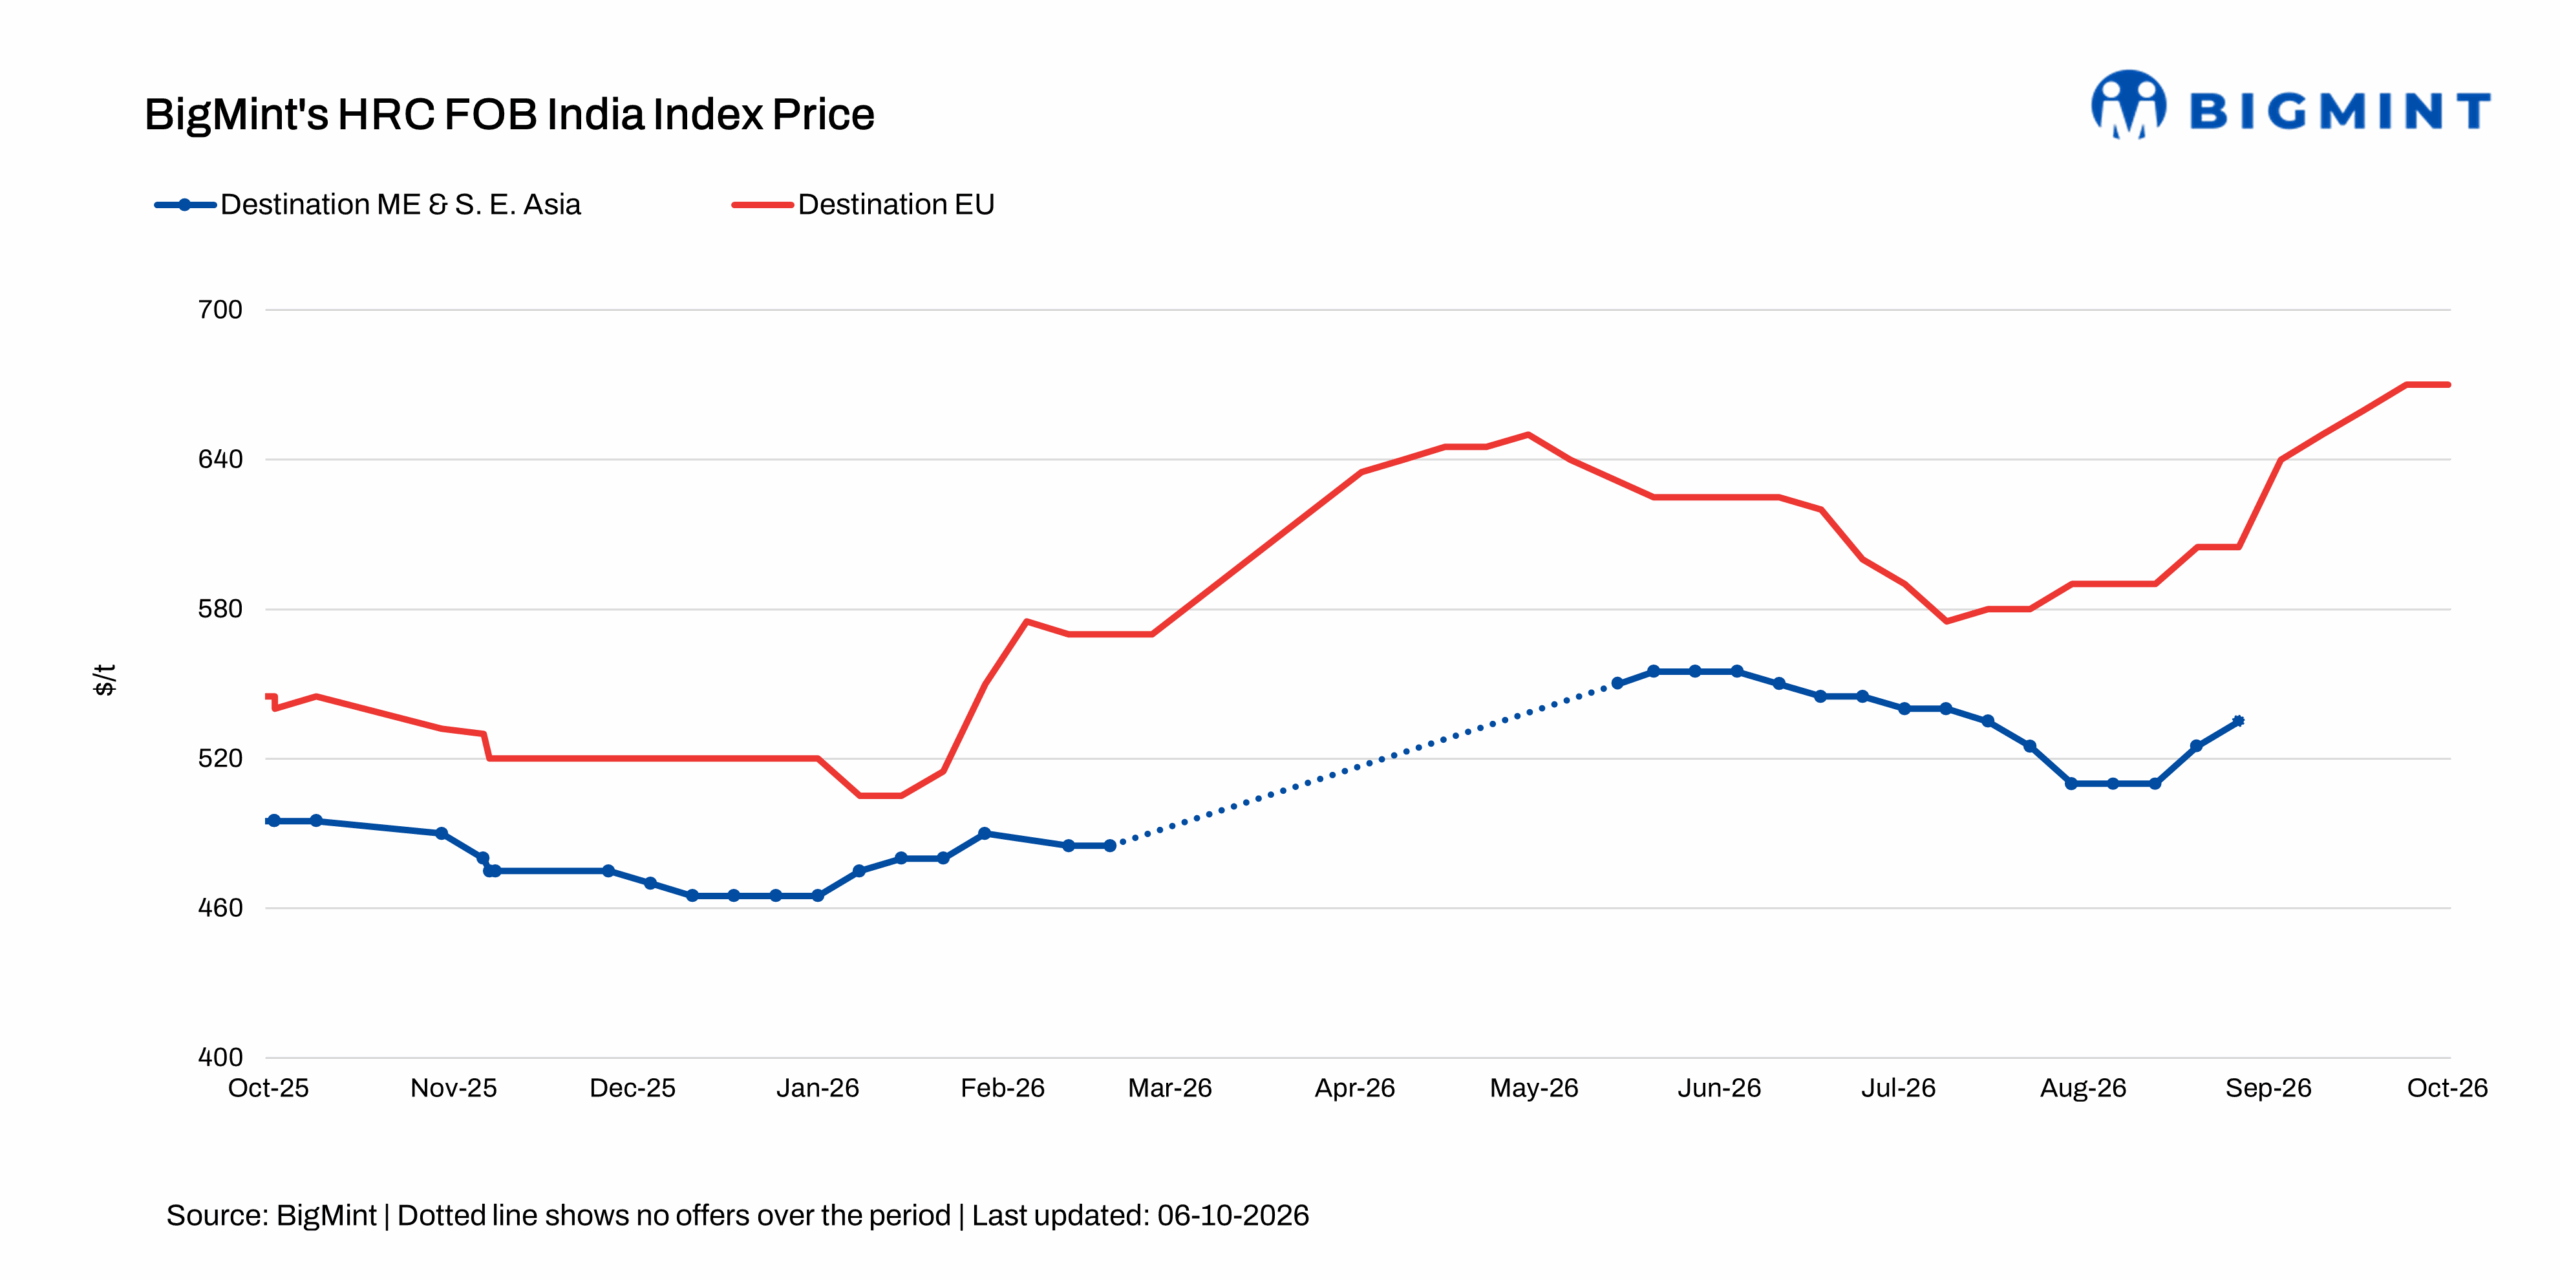
Indian HRC export offers varied across key destinations during the assessment week ended 6 October 2026. EU-bound offers held steady at around $670/t FOB, supported by firm domestic realisations; however, no fresh bookings were heard during the week as buyers remained reluctant to transact at elevated price levels. Meanwhile, offers to the Middle East and Vietnam remained on hold, as mills continued to prioritise domestic sales, restricting volumes available for fresh export bookings.
Indian HRC export offers to EU stable w-o-w: Indian HRC export offers to the EU remained stable w-o-w at around $670/t FOB, with freight estimated at around $70/t for Antwerp. Firm domestic realisations continued to support mills’ pricing. However, European buying interest remained subdued, as buyers were well covered on inventories and remain reluctant to accept higher import prices. This kept overall market activity muted, with firm mill offers meeting cautious buying interest.
A major Indian steel exporter stated, “Booking activity is expected to resume in the coming week as market participants gain greater clarity on Q3 CY’26 quota exhaustion figures along with the opening of the new quota booking window for Q1 CY’27.”
Moreover, the EU has published the CBAM certificate price for Q3 CY’26 at EUR 82.32 ($92.75), up by 9.4% from EUR 75.28 ($84.81) in Q2, potentially increasing the carbon cost burden for exporters, with the extent of the impact depending on the embedded emissions of individual shipments.
HRC export offers to Middle East, Vietnam on hold: Indian HRC export offers to the Middle East and Vietnam remained on hold, as mills continued to prioritise domestic sales amid firm HRC realisations in the local market. This has reduced mills’ willingness to allocate additional material for export, leaving little availability for fresh bookings.
Similarly, Chinese HRC export offers to the region remained absent during the week amid the National holiday and Golden Week period from 1-7 October. Mills and traders were largely inactive, limiting the availability of fresh offers during the holiday. Market participants expect selling activity to gradually resume after the holidays, which could bring greater clarity on export availability and pricing.
Outlook
Indian HRC export offers are likely to remain firm in the coming week. EU-bound offers may hold at elevated levels, with bookings expected to improve as buyers gain greater clarity on Q3 CY’26 quota exhaustion and the opening of the Q1 CY’27 quota window. Meanwhile, Middle East and Vietnam offers are likely to remain on hold amid mills’ continued focus on domestic sales, while the resumption of Chinese activity after the Golden Week holiday could provide clearer direction for regional pricing.
Leave a Reply