- Hindalco terminates AluChem acquisition
- EU review of Aughinish alumina exports could tighten European supply
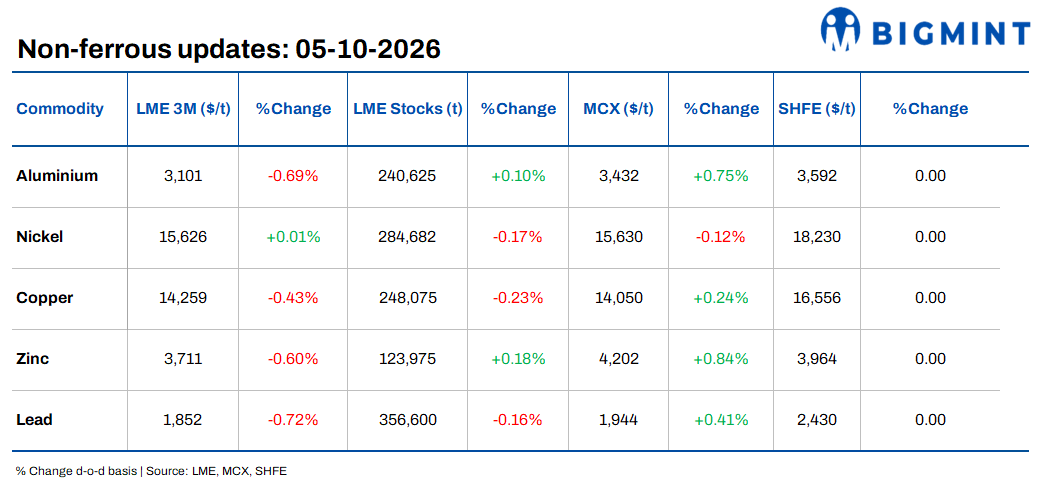
LME base metals traded mixed on 02 October. Lead recorded the sharpest decline, falling 0.72% d-o-d to $1,852/t, followed by aluminium, down 0.69% to $3,101/t, and zinc, lower by 0.60% to $3,711/t. Copper slipped 0.43% to $14,259/t, while nickel edged higher by 0.01% to $15,626/t.
SHFE prices for all five metals remained unchanged as the exchange was closed for China’s Golden Week holiday from October 1-7.
LME inventories recorded mixed trends. Zinc stocks posted the largest gain, rising 0.18% to 123,975 t, followed by aluminium, up 0.10% to 240,625 t. Copper inventories declined 0.23% to 248,075 t, while nickel and lead stocks fell 0.17% and 0.16% to 284,682 t and 356,600 t, respectively.
Domestic market overview
India’s non-ferrous scrap market witnessed mixed trends d-o-d. Aluminium tense scrap remained unchanged at INR 245,000/t ex-Delhi and INR 247,000/t ex-Chennai. Aluminium P1020 scrap declined by INR 5,000/t (1.4%), to INR 345,000/t from INR 350,000/t. These movements came despite MCX aluminium rising 0.75% d-o-d to INR 3,432/t.
Meanwhile, copper armature scrap (Cu 99%) increased by INR 7,000/t, or 0.5%, to INR 1,350,000/t from INR 1,343,000/t. MCX copper rose 0.24% d-o-d to INR 14,050/t, supporting firmer domestic copper scrap pricing.

Other updates
Middle East oil shock keeps aluminium cost risks elevated
Oil prices remained above $100/bbl, with Brent at $101.49/bbl, despite a 0.74% decline after Houthi attacks targeted Saudi Aramco facilities. Rising Middle East crude exports, which exceeded pre-war levels on four of seven days in the final week of September, and a planned 100-million-barrel G7 reserve release capped gains. However, continued attacks on energy infrastructure and shipping routes kept supply risks elevated.
EU review of Aughinish exports raises European alumina supply risk
Aughinish Alumina has intensified lobbying as the European Commission considers measures that could restrict alumina shipments from its Limerick refinery to Russia. The refinery shipped 422,474 t of alumina to Russia in H1 2026, while its annual capacity stands at roughly 1.9 Mnt. Therefore, any restriction that leads to lower refinery utilisation could tighten European alumina availability and lift regional premiums.
Glencore secures RIGI approval for Agua Rica copper project
Glencore received Argentina’s RIGI approval for the $4 billion Agua Rica/MARA copper project on 02 October. The project could eventually produce around 200,000 t of copper annually, while Glencore has also accelerated the restart of Alumbrera, with first production now expected in H2 2027. As a result, the development strengthens the longer-term copper supply pipeline.
C.S. Aluminium approves TWD 1.02 billion low-carbon facility
Taiwan’s C.S. Aluminium received approval to invest around TWD 1.02 billion in a new facility in Kaohsiung’s Xiaogang District. The project will focus on high-grade and low-carbon aluminium while incorporating solar generation, smart sensors and digital technologies. Moreover, the investment reflects growing demand for lower-carbon and value-added aluminium products.
Hindalco terminates AluChem acquisition
Hindalco and AluChem jointly terminated the proposed $125 million acquisition on 01 October after prolonged closing delays. AluChem operates three US manufacturing facilities with annual speciality-alumina capacity of around 60,000 t, while Hindalco currently has about 500,000 t of speciality-alumina capacity and targets 1 Mt by FY30. Hindalco will need another route to expand its US speciality-alumina presence.
Leave a Reply