- Buyers remain cautious amid limited procurement activity
- Gujarat steel prices show mixed trends, while Mandi holds steady
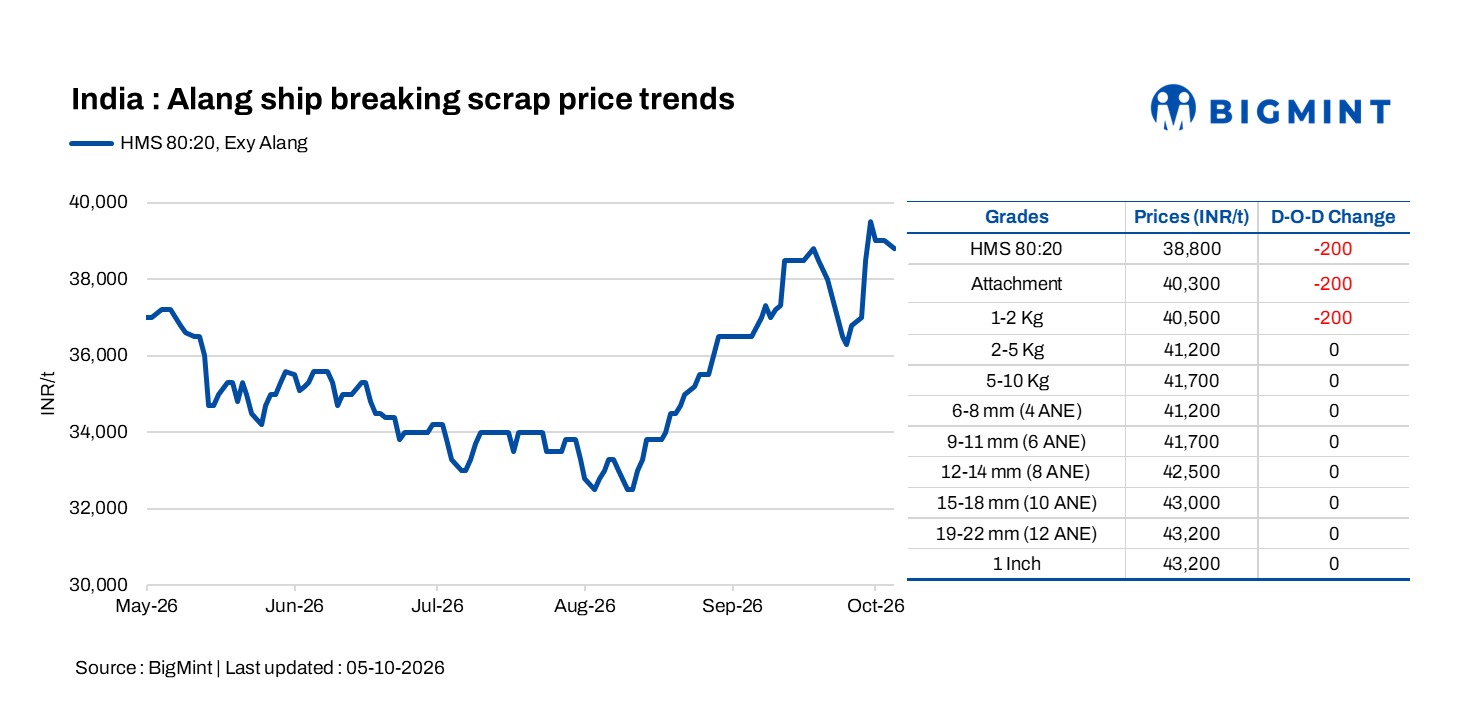
Alang’s ship-breaking melting scrap prices for HMS 80:20 decreased by INR 200/tonne (t) day-on-day (d-o-d) to INR 38,800/t ($403/t) ex-yard on 5 October 2026. Market sentiment remained weak, with limited buying interest and a wide gap between sellers’ offers and buyers’ bids. Buyers continued to restrict procurement to immediate requirements, anticipating further price corrections amid uncertain demand and fluctuating steel prices in key consuming markets. Sellers faced resistance to higher offers as buyers remained unwilling to match their expectations, keeping trade activity subdued.
On the supply side, vessel availability at Alang remained exceptionally tight. According to local market participants, disruptions to major shipping routes amid geopolitical conflicts, including tensions around the Strait of Hormuz, have restricted the flow of vessels nearing the end of their operating lives towards Alang. Arrivals from the Singapore side have also remained limited. The shortage has constrained fresh ship-recycling activity despite firmer scrap demand and improved local scrap prices.
“Due to ongoing conflicts between Russia-Ukraine, Iran-Israel, and the US, maritime cargo transport has been impacted. Sea routes are in a stalled state. The local scrap market has improved, and shipbrokers have funds to acquire ships, but the availability of vessels sent for breaking in the international market has reached rock bottom.” stated by Rameshbhai Mendpara, Vice President, Ship Recycling Industries Association (SRIA).
Industry participants said local scrap prices have increased by around INR 3-5/kg in recent weeks, but the improvement has not translated into adequate vessel supply. Alang received only 64 vessels during April-September 2026, significantly below historical levels, highlighting the structural decline in vessel inflows. The limited availability of ships is tightening scrap supply from the recycling sector and could remain a key factor for prices if steel demand improves further.
Gujarat market update

In Gujarat, Bhavnagar billet prices decreased by INR 300/t d-o-d to INR 48,000/t DAP, while Ahmedabad rebar prices increased by INR 200/t to INR 53,500/t ex-works. The divergent movements indicated mixed trends across the steel value chain, with softer billet prices reflecting pressure on semi-finished steel demand, while rebar prices found some support. However, the improvement in finished steel prices has yet to translate into stronger scrap procurement, as buyers remain cautious about replacement costs and downstream demand.
Mandi market update
In Mandi Gobindgarh, billet prices remained stable d-o-d at INR 48,750/t DAP. HMS melting scrap prices were also unchanged at INR 40,000/t DAP, while rebar prices held steady at INR 53,700/t ex-works.
Market sentiment showed some support from moderate buying interest and a brief pickup in spot enquiries. However, procurement remained largely need-based, with mills cautious about building inventories amid uncertainty over the sustainability of recent price gains. Limited trading activity and concerns over downstream demand continued to restrict further price increases.
Outlook
Scrap prices are likely to remain rangebound, with near-term direction depending on billet and rebar movements and mill procurement. Improved downstream demand could support prices, while weak steel realisations may keep buyers cautious. The uncertainty over when vessel inflows will normalise remains a key concern for the ship-recycling industry, particularly as steel and scrap demand improves while availability of recyclable vessels remains restricted.
Leave a Reply