- Atlantic Panamax firm on tight tonnage, steady enquiries
- Supramax stays firm despite limited Indonesian activity
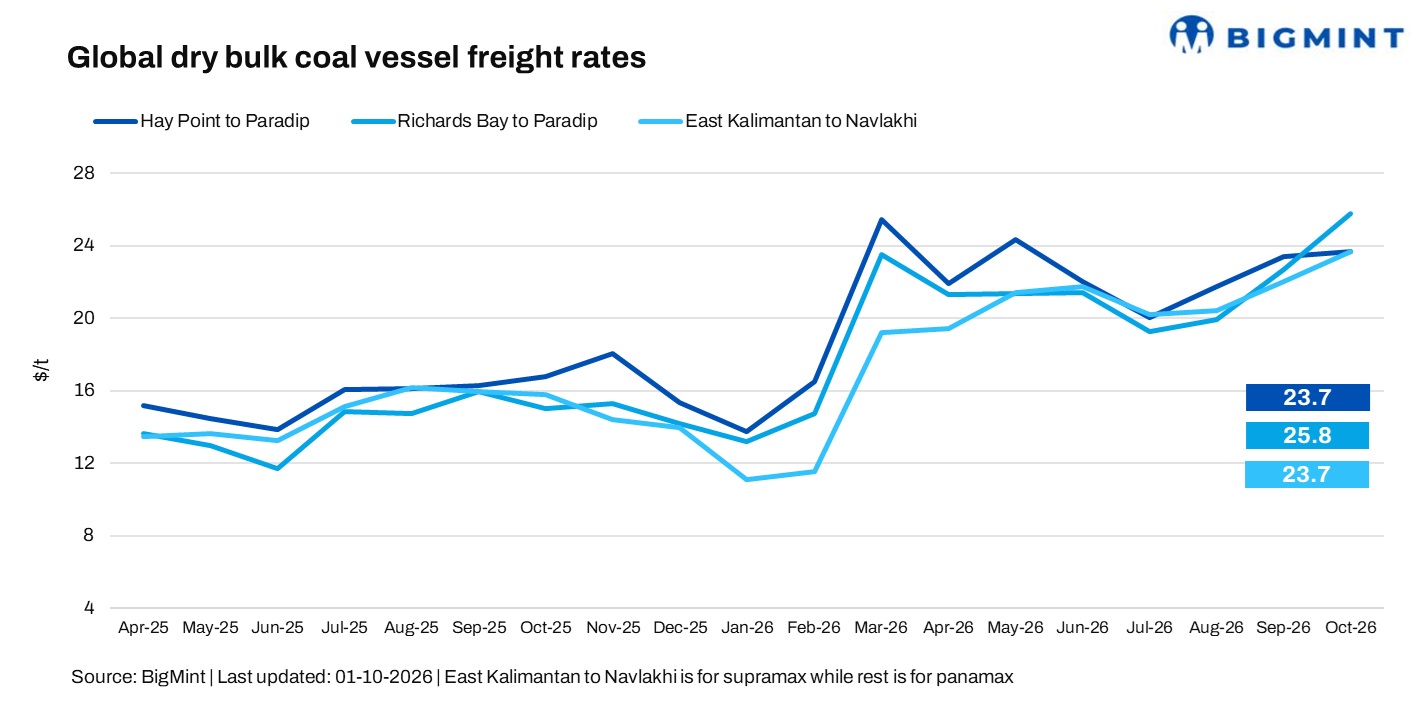
India-bound coal freight markets were mixed in the week ended 1 October 2026, with Panamax rates remaining supported by tight prompt tonnage and steady India-bound enquiries, while Supramax rates edged higher despite quieter spot activity. Pacific business remained subdued, particularly on Indonesian coal routes, while charterers continued to resist higher freight levels on some Australian routes.

Panamax stays resilient amid quiet Pacific activity
Panamax freights remained supported by tight prompt tonnage and steady India-bound enquiries, although Australian activity stayed subdued as charterers resisted higher levels.
A shipbroker told BigMint, “Panamax freight rates were mixed as sentiment softened in the Pacific. Activity is still quiet, but shipowners are maintaining their fixing ideas and remain reluctant to provide discounts.”
Despite softer sentiment across the wider dry bulk market, balanced supply-demand conditions allowed owners to hold their rate ideas. However, weaker Capesize sentiment could exert some pressure on Panamax going forward.
Supramax remains firm
Supramax freights were mostly steady to higher despite Indonesian coal routes seeing slower activity and fewer fresh enquiries. Spot fixing remained limited, although steady India-bound requirements and firm owner ideas continued to lend support.
A trader mentioned, “Supramax market freight rates were mostly flat to higher as the Pacific market continued to witness slower activity, more notably on the Indonesian coal routes.”
With the market remaining relatively quiet, firm tonnage ideas and steady India-bound demand continued to keep Supramax sentiment on a firm footing.
Dry bulk indicators weaken as fuel and coke prices fall
- Baltic Dry Index (BDI) declines w-o-w: The BDI declined 10.4% (360 points) w-o-w to 3,113 as of 30 September, from 3,473 as of 24 September, reflecting a broad weakening in overall dry bulk market conditions. While the Panamax segment remained broadly stable, edging up 0.1% (2 points) to 2,384 from 2,382, Supramax also showed a modest improvement, rising 0.8% (15 points) to 1,797 from 1,782, indicating relatively firmer conditions in the smaller-size segment.
- Bunker prices decline w-o-w: Singapore very low sulphur fuel oil (VLSFO) fell 6.5% ($59/t) w-o-w to $845/tonne (t) as of 1 October, from $904/t on 25 September. The decline indicates some easing in bunker market pressure, although fuel-oil supply dynamics, crude price volatility and Middle East-related uncertainty continue to influence bunker costs and voyage economics.
- Brent crude futures decline w-o-w: December Brent crude futures fell 4.2% to $4.40/barrel (bbl) w-o-w to $100.54/bbl as of 1 October, from $104.94/bbl on 25 September. The decline indicates some easing in crude price pressures, although ongoing Middle East tensions and disruption risks around the Strait of Hormuz continue to keep crude markets and marine fuel costs volatile, with implications for voyage economics.
- DCE coke futures edge lower w-o-w: January 2027 Dalian Commodity Exchange (DCE) coke futures fell 4.6% (RMB 94/t; $14.05/t) w-o-w to RMB 1,958.50/t ($292.11/t) as of 1 October, from RMB 2,052.50/t ($306.16/t) a week earlier, amid cautious market sentiment and softer steel demand expectations.

Outlook
BigMint expects Panamax sentiment to remain supported but largely stable, with tight prompt tonnage and steady India-bound enquiries offsetting subdued Pacific activity. Supramax is likely to retain a firm undertone, although slower Indonesian activity and limited fresh cargo flow may keep spot fixing subdued in the near term.
Overall, freight sentiment remains supported but lacks strong fresh cargo momentum, with the return of enquiries and prompt tonnage availability likely to shape the next move.
Leave a Reply