- Fresh enquiries turn scarce as Chinese mills complete pre-holiday restocking
- Global iron ore prices ease, weak Chinese steel demand outlook weighs on market
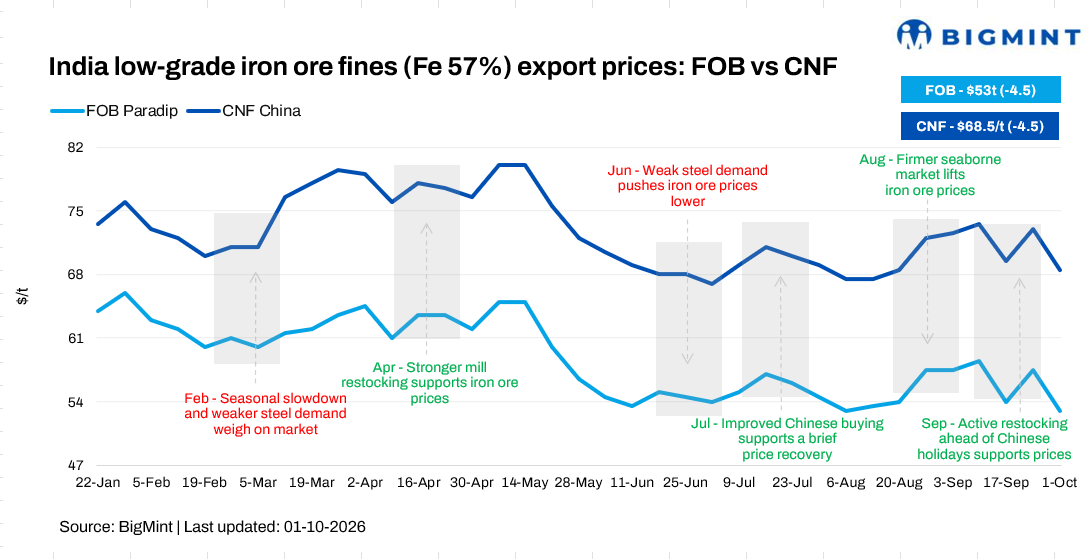
India’s low-grade iron ore fines (Fe 57%) export prices fell by around $4.5/tonne (t) w-o-w to $53/t FOB east coast in the week ended 1 October 2026, from $57.5/t a week earlier, reaching their lowest level since 10 August. The price was equivalent to around $68.5/t CFR China.
The decline was primarily driven by weak Chinese buying interest, with buyers showing limited appetite for Indian low-grade fines amid subdued steel demand and cautious mill procurement. The onset of China’s Golden Week holiday (October 1-7) further dampened market activity, as most mills and traders had already completed their pre-holiday restocking and stepped away from the spot market.
A trader told BigMint, “Nothing much is happening in the market as China’s Golden Week holiday has begun, keeping buying activity largely on hold.”
Indian exporters faced increasing pressure to lower offers as fresh enquiries from China remained scarce. With holiday-related buying largely concluded, market participants were reluctant to commit to additional cargoes, particularly at prevailing freight-inclusive prices. This left Indian low-grade fines suppliers with limited room to negotiate, resulting in a sharp weekly correction.
The weakness in China’s physical market was also reflected in limited spot activity and cautious mill buying, despite some improvement in broader ferrous-market sentiment. High-grade material continued to attract relatively better interest, while lower-grade fines faced greater pressure as mills remained focused on cost control and operating margins.
“The market remains slow, with activity also affected by port restrictions and tightening of norms along India’s eastern coast, limiting cargo movement and fresh bookings,” another trader highlighted.
Rationale
- No deals were reported during the current publishing window; consequently, T1 trades received 0% weightage in the index calculation.
- BigMint received thirteen (13) indicative price inputs, of which nine (9) qualified as T2 inputs and accounted for the 100% weightage.
Chinese holiday slowdown weighs on iron ore prices and futures
- Global iron ore prices ease as Chinese mills complete pre-holiday restocking: Global benchmark iron ore (Fe 61%) prices declined by $2/t w-o-w to $93/t CFR China on 30 September, from $95/t on 23 September. Ahead of China’s Golden Week holiday (October 1-7), most market participants stepped away from fresh buying due to the week-long break. However, slightly improved sentiment across the ferrous complex, following China’s recent housing and targeted monetary support measures, limited the price drop.
China’s official manufacturing PMI rose to 50.1% in September from 49.8% in August, returning to expansion territory, according to the National Bureau of Statistics. However, the improved macroeconomic sentiment had limited impact on physical iron ore demand, as mills had largely completed their pre-holiday restocking. With earlier restocking already priced in, fresh buying interest remained limited ahead of the holiday.
- DCE iron ore futures weaken on cautious Chinese demand outlook: January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) decreased by RMB 11/t ($1.6/t) w-o-w to RMB 702.5/t ($104.8/t) on 1 October, from RMB 713.5/t ($106.4/t) a week earlier. The decline reflected cautious market sentiment ahead of China’s Golden Week holiday, with reduced participation and limited fresh buying from mills. Persistent concerns over weak steel demand, subdued mill margins and ongoing production controls also weighed on futures sentiment. Although China’s manufacturing PMI returned to expansion territory in September, the improvement provided limited support as physical iron ore demand remained soft and mills had largely completed their pre-holiday restocking.
China holiday pressure widens low-grade iron ore export & domestic realisations spread
The spread between domestic and export realisations widened significantly to around INR 1,158/t ($12/t) this week, as prices in the two markets moved in opposite directions. Export realisations declined to INR 2,692/t ($28/t), pressured by weak overseas demand, limited fresh enquiries from Chinese buyers and reduced spot-market activity during China’s Golden Week holiday. Indian exporters faced limited room to maintain offers as buyers remained cautious and freight-inclusive economics weakened.
In contrast, domestic low-grade iron ore prices rose by INR 150/t ($1.6/t) w-o-w to INR 3,850/t ($40/t) ex-mines, supported by relatively firmer domestic buying interest and higher offers from miners. The divergence has significantly increased the premium for domestic sales over exports, making the domestic market comparatively more attractive for Indian suppliers of low-grade ore. However, the sustainability of this spread will depend on the recovery in Chinese buying activity after the holiday and the direction of domestic iron ore demand and prices.
Outlook
India’s low-grade iron ore export market is expected to remain subdued in the near term as China’s Golden Week holiday keeps spot activity muted. Buying interest could gradually return after the holiday, but price recovery is likely to depend on the pace of Chinese mill restocking, steel demand and margins. Until then, Indian exporters may continue to face pressure amid limited Chinese enquiries and competitive seaborne supply.
Leave a Reply