- Turkiye scrap prices firm; India buying remains subdued
- Pakistan buying cautious; Bangladesh offers remain firm
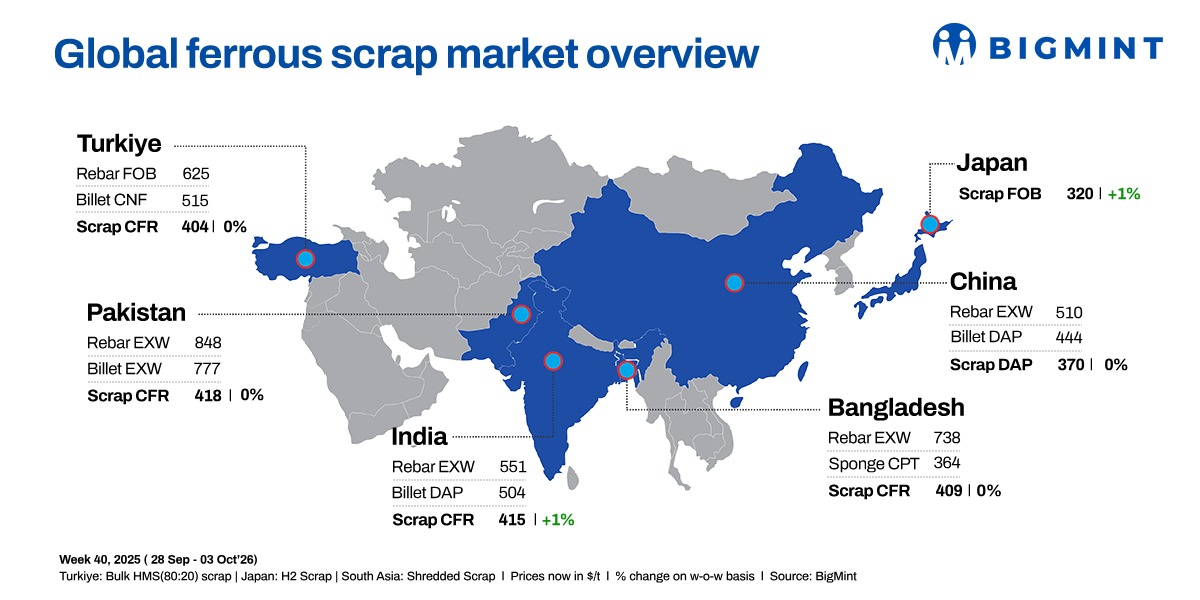
Global ferrous scrap markets remained mixed on 3 October, with Turkiye and Japan seeing firmer prices, while India, Pakistan and Bangladesh faced cautious buying amid weak downstream demand. Firm seller offers and higher replacement costs supported regional prices, although elevated freight and import-related constraints continued to limit trading activity across key Asian markets.
Turkiye: Turkiye’s deep-sea scrap market remained stable during the week ended 1 October amid cautious mill buying and weak rebar demand. Higher freight and energy costs and tighter European scrap availability supported offers.
US HMS 80:20 was $404/t CFR, unchanged w-o-w. US offers were around $410/t, with tradable levels at $404-405/t; Baltic and EU scrap were around $400/t and $398-399/t CFR, respectively.
Two Netherlands-origin cargo was booked at $395/t CFR Turkiye. Domestic rebar was $630-650/t exw and exports $620-630/t FOB, keeping the scrap-rebar spread at $220-222/t.
Imported scrap market remained subdued through the week, with mills limiting purchases to need-based requirements amid weak downstream demand. New PSIC requirements and higher Türkiye prices continued to weigh on import activity, while rising freight costs further pressured import economics.
Offers remained high against buyer bids, keeping trading activity thin. UK HMS 80:20 was offered at $365-375/t CFR Mundra, US HMS 80:20 at $370-375/t and African HMS 80:20 at $365-370/t. UK shredded was offered at $445-450/t for 1% impurities, while Brazilian HMS 80:20 was booked at $385/t CFR Mundra.
Near-term buying is expected to remain cautious; however, demand for HMS 80:20 imports is expected to remain relatively firm until Diwali.
Pakistan: Imported scrap market remained largely rangebound through the week, with buying activity initially subdued as suppliers held material on water while buyers resisted higher levels. Shredded scrap was offered around $415-420/t CFR Qasim, against bids near $412/t, while UK-origin material was increasingly offered at higher levels amid continued demand for prompt and quality cargoes.
Towards the end of the week, market activity improved, with UK shredded scrap deals heard at $422-427/t CFR Qasim and a possible settlement around $420/t. High grade origin yard material was also reported at $427/t CFR. However, local scrap prices remained at PKR 134,000-138,000/t ($484-499/t), while uncertainty over the new sales tax on power bills continued to weigh on market sentiment.
Bangladesh: Imported scrap market remained rangebound through the week, with trading activity limited by weak rebar sales and slow buying interest. Despite subdued demand, sellers-maintained firm offers amid higher replacement costs, with US West Coast bulk HMS around $400/t CFR Chattogram and Malaysian and Philippine PNS offers reaching around $420/t.
Buying interest remained selective as buyers resisted higher prices. An Australian PNS cargo was booked at $405/t CFR Chattogram, while Australian HMS 90:10 was offered at around $400/t but considered too high. Overall, firm seller expectations against weak downstream demand kept the market rangebound.
Japan: FOB Tokyo Bay scrap prices increased JPY 700/t to JPY 50,500/t ($320/t), while H2 export prices also edged higher during the week.
Fresh Japan-origin offers remained limited during the holiday period, with suppliers expected to resume negotiations once the market reopens. Shredded scrap and other export prices are also likely to track currency movements and overseas market trends.
UAE: UAE domestic scrap prices remained broadly stable as weak steel demand and limited mill buying offset firmer international markets. BigMint assessed processed HMS 80:20 at AED 1,033/t ($281/t), up AED 3/t w-o-w. Rebar demand remained subdued, while billet offers stood at $650-660/t CPT Jebel Ali for GCC and $590-600/t for Chinese material.
Leave a Reply