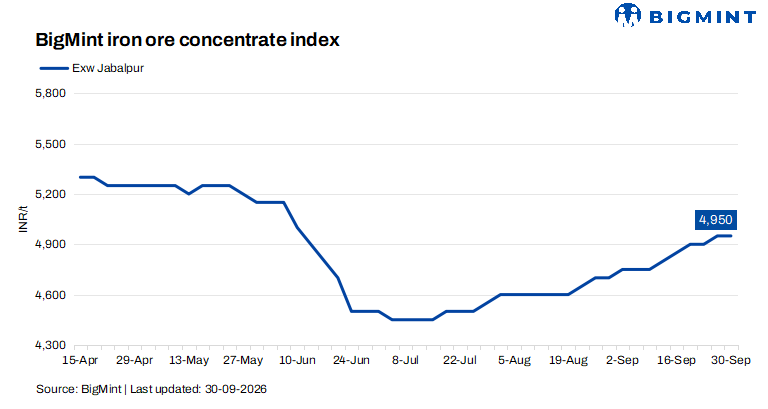
- Improving concentrate demand supports market sentiment
- Tight spot availability strengthens sellers pricing stance
India’s iron ore concentrate prices remained firm this week, supported by positive sentiment in the domestic pellet and Odisha iron ore markets. Trading activity also remained healthy, while limited availability of spot material further strengthened sellers’ pricing positions. Despite the Fe 62% assessment remaining unchanged, the overall market sentiment continued to be supportive, with sellers showing limited willingness to negotiate at lower levels amid firm raw-material prices and improving buying interest.
BigMint’s bi-weekly assessment for Fe 62% concentrate remained stable at INR 4,950/t ($52/t) ex-works, unchanged from the previous assessment on 26 September 2026, seller indications ranged from INR 4,700/t ($49/t) at the lower end to around INR 5,100/t ($53/t) while Offers for Fe 63% concentrate were heard at around INR 5,300/t ($55/t). The stability in the benchmark price reflects a balanced market, with firm demand and tight availability offsetting cautious sentiment in the downstream steel market.
Concentrate availability remains relatively tight in the region. Monsoon-related disruptions had impacted mining and dispatches, resulting in delays in fulfilling old orders. Although rainfall has eased over the past few days and mining activity has started improving, fresh spot availability remains limited as producers continue to prioritise pending commitments. This has enabled sellers to maintain firm offers and avoid significant price concessions.
Trading activity remained supportive as buyers who had stayed out of the market started entering after price negotiations, while sellers completing their old-order commitments returned with fresh offers at current market levels. A Jabalpur-based seller told BigMint that “production is currently focused on completing pending old-order quantities and that there would be no price revision until those orders are fulfilled”
Another seller said, “We have sold out and are now taking bookings for the entire coming month,” highlighting firm demand and limited availability.
Rationale
- Three (3) trades were recorded in this publishing window, which were taken into consideration. Therefore, this category received a 50% weightage.
- Seven (7) offers and indicative prices were heard, of which all were taken into consideration as T2 trades, receiving 50% weightage.
Factors shaping market dynamics
- Raipur pellet prices increase for 2nd time this week: Pellet manufacturers in Raipur, Chhattisgarh, have raised offers for Fe 62.5/63% (±0.5%) grade pellets by another INR 300/t ($3/t) to INR 11,400-11,500/t ($119-120/t) ex-works, marking the second consecutive hike this week. Around 70,000 t of pellets were reportedly booked earlier this week, while tight spot availability and higher sponge iron prices have strengthened sellers’ pricing positions.
- Odisha iron ore prices hit four-month high: BigMint’s Odisha Fe 62% iron ore fines assessment increased by INR 300/t ($3/t) w-o-w to around INR 5,500/t ($57/t) ex-mines in the week ending 26 September 2026, marking a four-month high. The increase followed higher OMC base prices in its 19 September auction and supported firmer sentiment across the domestic iron ore market.
- Spot concentrate availability remains tight: Monsoon-related disruptions have delayed mining and dispatches, while producers continue to fulfil pending old-order commitments. Although mining activity has started improving with better weather, fresh spot availability remains limited, supporting sellers’ firm stance.
Outlook
Iron ore concentrate prices are expected to remain largely stable with a positive bias in the near term, supported by firm pellet and iron ore prices, improving domestic buying activity and constrained spot availability.
Leave a Reply