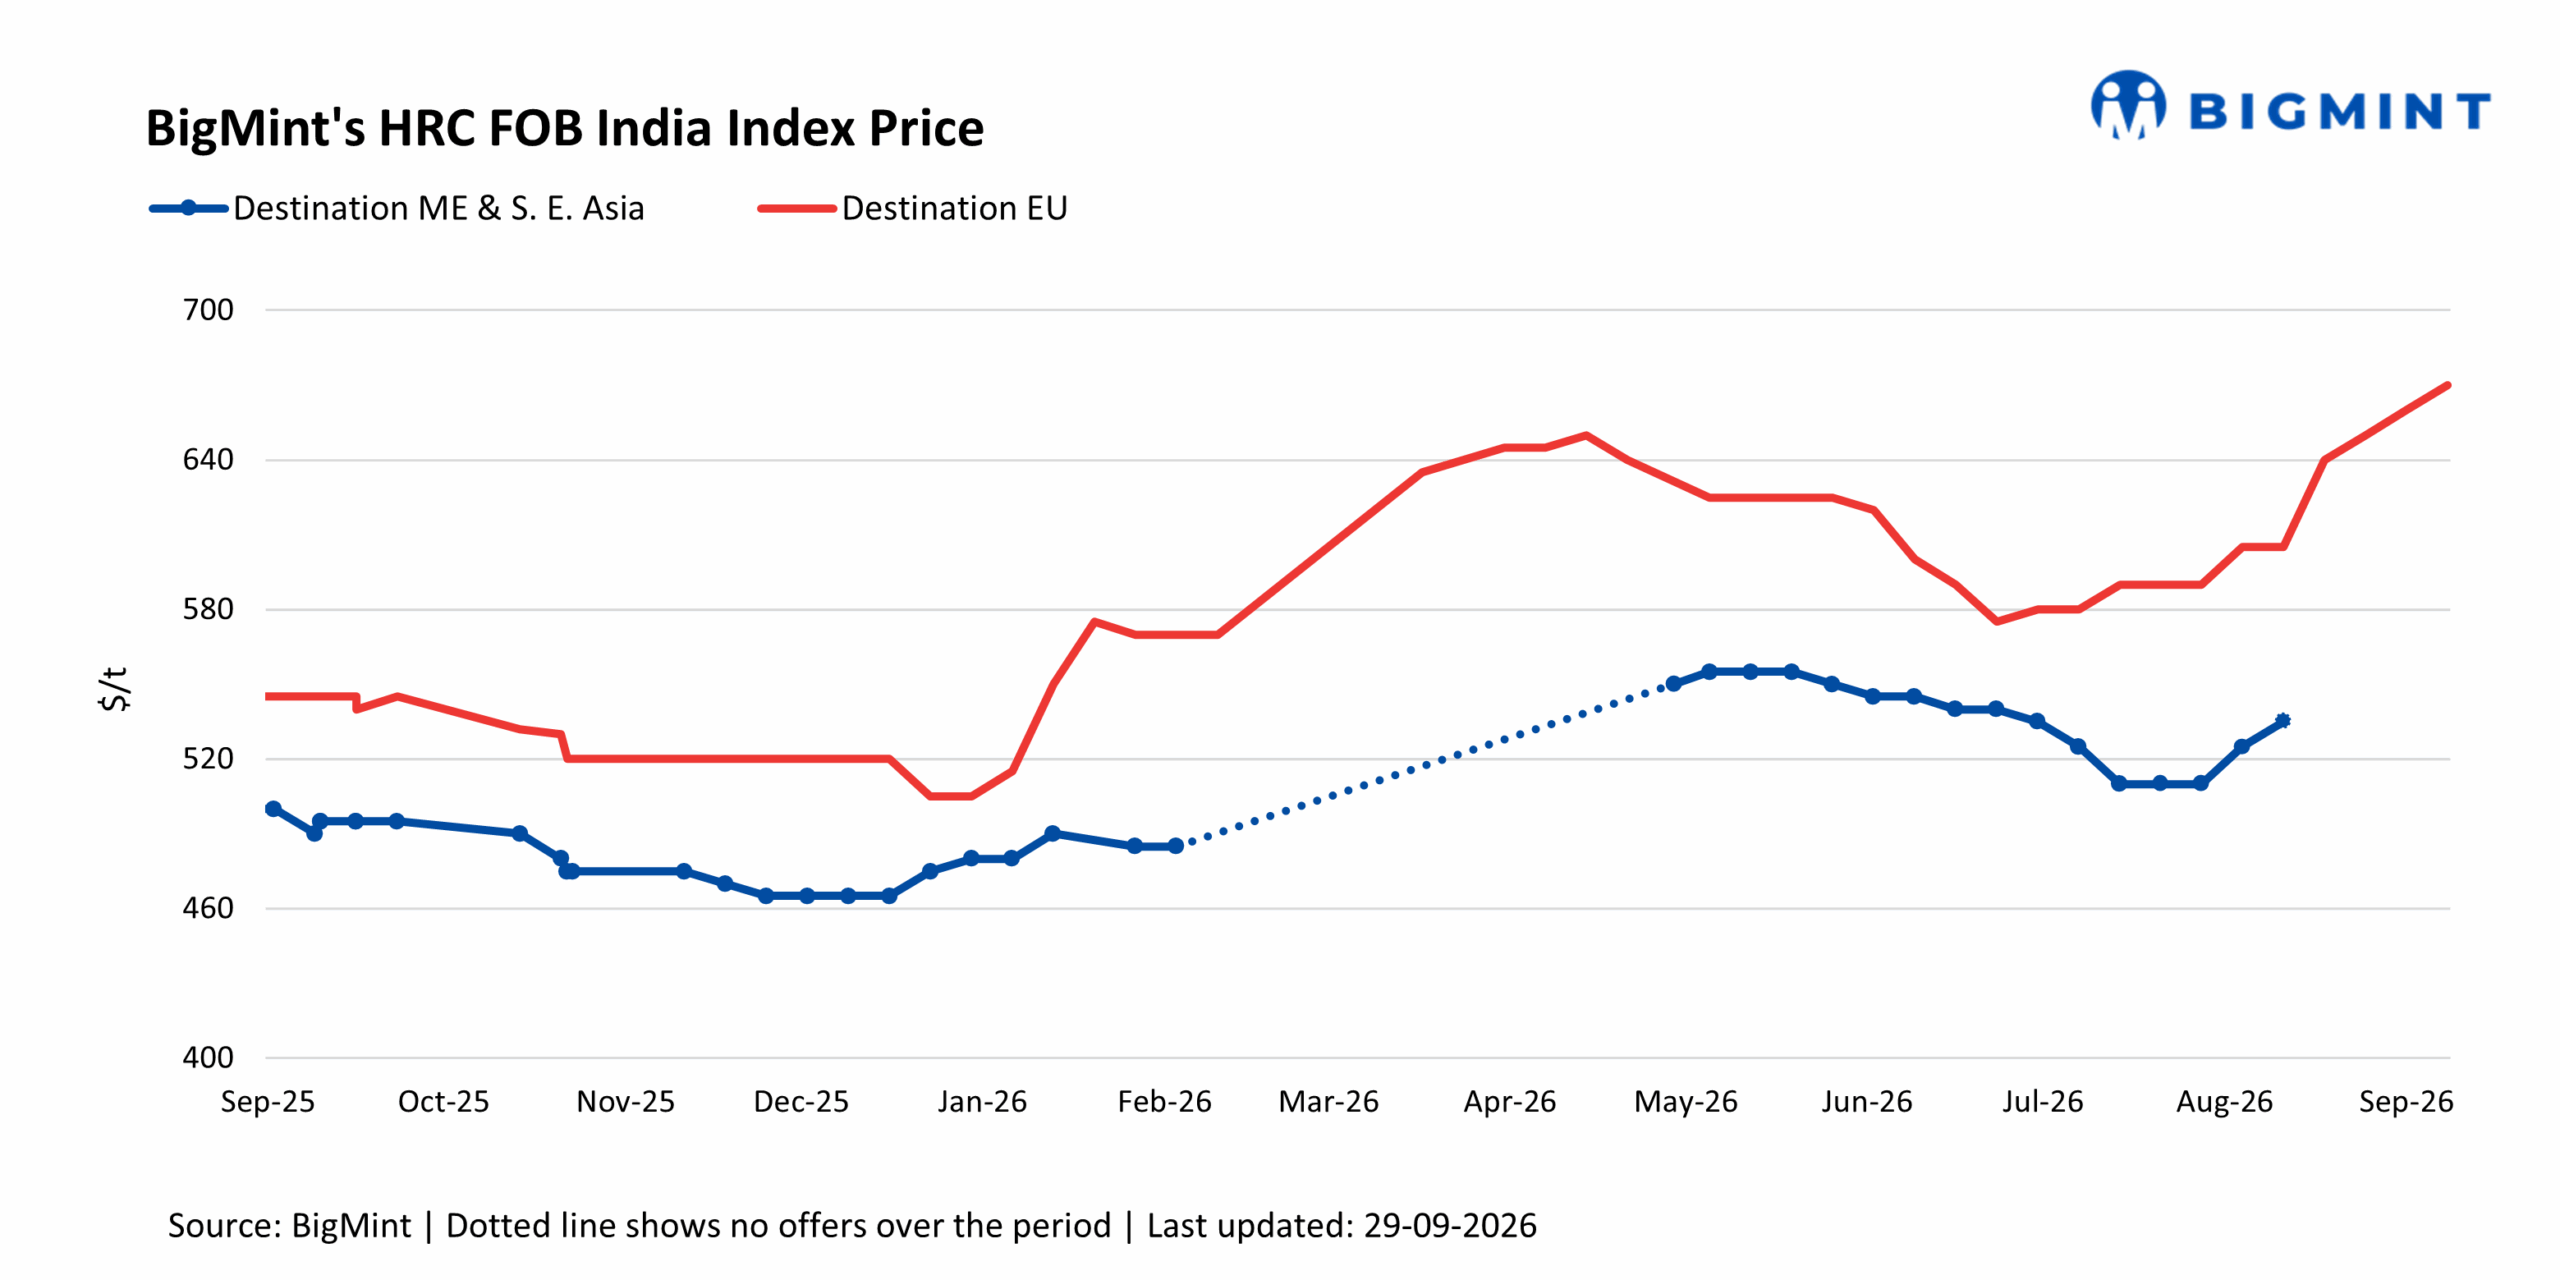
- EU offers surge to nearly 3-year high on firmer mill expectations
- Middle East, Vietnam offers remain on hold amid fully booked allocations
Indian HRC export offers showed mixed trends w-o-w across key destinations during the assessment week ended 29 September 2026. EU-bound offers moved higher amid firmer mill price expectations, although buying interest remained subdued as buyers were reluctant to accept the higher levels. Meanwhile, offers to the Middle East and Vietnam remained on hold, with mills having limited availability for fresh export bookings and continuing to prioritise domestic sales.
HRC export offers to EU rise w-o-w: Indian HRC export offers to the EU rose by around $10/t w-o-w to $670/t FOB, compared with $660/t a week earlier, reaching a nearly three-year high. However, no fresh bookings were reportedly concluded at these levels during the assessment window, as buyers remained reluctant to accept the elevated offers.
An EU-based source stated, “Prices have been increasing consecutively w-o-w, widening the gap between mills’ offers and buyers’ workable levels. Buyers have therefore become increasingly cautious about committing at elevated prices, keeping fresh purchasing activity subdued during the week.”
Meanwhile, another EU-based source noted that buyer inventories remain relatively well covered following heavy pre-summer purchasing, with previously booked material still arriving in the market. This has reduced the need for immediate replenishment and kept spot buying subdued. While the impact of quotas is expected to become more pronounced shortly and could tighten supply.
EU domestic mills are currently offering HRC at around EUR 735-740/t ($834-840/t) and testing higher levels of EUR 750/t ($851/t). However, buyers remain reluctant to accept the higher offers, making it difficult for mills to establish EUR 750/t ($851/t) as the prevailing market level.
Indian HRC export offers to the Middle East and Vietnam remain on hold: Indian HRC export offers to the Middle East and Vietnam remained on hold, as mills continued to prioritise domestic sales, leaving no volumes available for fresh export bookings. Firm domestic HRC prices have further reduced mills’ willingness to allocate material to export markets, keeping fresh offers on hold.
Meanwhile, Chinese HRC export offers to the region rose by around $15/t w-o-w to $600/t CFR, up from $585/t in the previous week. A booking of around 45,000 t was also reportedly concluded at similar levels for November shipment.
Moreover, a China-based source stated, “With China’s National Day and Golden Week approaching, market activity is likely to remain subdued. There may be limited active offers available in the market from 1 to 7 October, as mills are expected to remain less active during this period, with fresh offers and market activity expected to pick up thereafter.”
Outlook
Indian HRC export offers are likely to continue showing mixed trends in the coming week, with offers to the Middle East and Vietnam expected to remain on hold as mills are likely to continue prioritising domestic sales. Meanwhile, EU-bound offers could remain elevated as mills maintain higher price expectations. While subdued buying interest and relatively well-covered inventories may continue to limit fresh spot bookings, concerns over availability under the Q1 CY’27 EU quota and the possibility of further price increases could encourage buyers to secure volumes before the quota is fully booked.
Leave a Reply