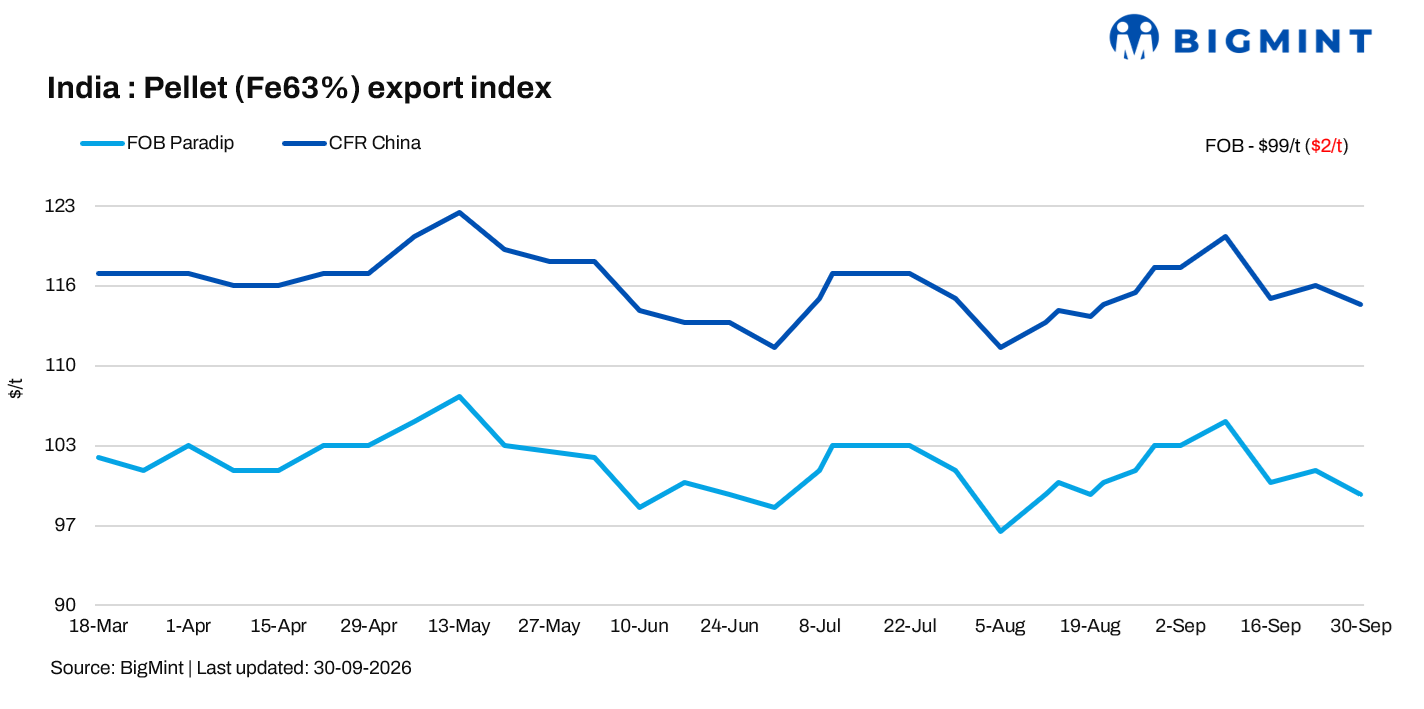
- Holiday-related market lull and lower iron ore prices weigh on sentiment
- India pellet export prices decline as Chinese demand remains weak
BigMint’s India pellet export index declined by around $2/t w-o-w to $99/t FOB East Coast on 30 September 2026, equivalent to around $114/t CFR China, amid continued weakness in the global iron ore fines market. The decline comes as Chinese buying remains subdued ahead of the Golden Week holidays, while lower iron ore prices continue to weigh on pellet market sentiment.
Chinese pellet inventories at 34 major ports declined to around 5.66 million tonnes (mnt), from 5.73 mnt a week earlier, indicating some inventory drawdown. However, the decline has not translated into stronger spot buying, as most Chinese mills had already completed their procurement requirements ahead of the extended holiday period.
Rationale
- Zero (0) confirmed deals from India’s east coast were recorded in this publishing window for T1 trade, and, therefore, this category was allotted 0% weightage for today’s price calculations. Click here for the detailed methodology.
- Ten (10) bids, offers, and indicative prices were heard, of which seven (7) were considered for the calculation of the index and given the balance 100% weightage.
Trades and Deals
No fresh export sales from India’s east coast were heard during the publishing window, as sellers remained largely absent from the seaborne market. Domestic realisations continue to be significantly more attractive than export parity, limiting the availability of pellets for overseas sales.
Some Fe 63% pellet tenders (around 110,000 t) from India’s western coast were heard during the period; however, the material was ultimately sold in the domestic market. As a result, no fresh export transactions were concluded, while sellers continued to withhold offers from the international market.
Market updates
Chinese pellet buying remained subdued amid the ongoing Mid-Autumn Festival and the upcoming Golden Week holidays. The holiday period from 1-7 October has significantly reduced spot-market activity, with most mills having completed their near-term procurement requirements in advance. This has left limited scope for additional restocking before the holidays.
An international trader told BigMint that buying sentiment remains weak across the ferrous value chain, with prolonged weakness in downstream demand and the extended holiday period discouraging Chinese mills from making aggressive purchases. International traders have also remained largely inactive, anticipating limited market participation during the holiday period.
Activity in both the spot and portside markets for iron ore fines and pellets remained limited. Weak iron ore prices and subdued downstream steel demand continued to reinforce a cautious procurement approach among Chinese mills.
On the supply side, Indian pellet exporters remained largely focused on the domestic market. Domestic plants were reportedly achieving realisations around INR 1,900-2,000/t higher than export parity on an ex-plant basis, leaving little incentive for producers to participate actively in the international market.
Market participants indicated that Indian sellers would require export prices to improve to around $117-118/t CFR China, equivalent to approximately $104-106/t FOB East Coast, before export participation become attractive. At current levels, the gap between domestic and export realisations continues to discourage fresh overseas sales.

Domestic vs export market
Pellet export realisations for Fe 63% were recorded at INR 7,350/t ($78/t), falling by INR 150/t this week, while domestic realisations (Fe 62.5%) edged up slightly by INR 50/t w-o-w to INR 9,250/t ($96.5/t) exw. Thus, the gap widened further by INR 200-250/t w-o-w to INR 1,925/t making it still unrealistic for exports to take place.
Factors impacting pellet exports
Chinese iron ore fines prices showed weakness w-o-w: The benchmark iron ore fines Fe 61% index declined further by $2/dmt to $93/dmt CFR China on 29 September. Physical demand continued to remain weak as pre-holiday restocking activity would down, while persistently slim steel mill margins kept buyers cautious. China’s iron ore portside prices also softened day over day, pressured by declining finished steel prices and weak buying interest. The correction in iron ore prices was largely linked to the weakness in finished steel prices, which continued to weigh on procurement sentiment among mills.
DCE iron ore futures decline w-o-w: Iron ore futures on the Dalian Commodity Exchange (DCE) for the January 2027 contract settled at RMB 702.5/t on 29 September falling by RMB 13/t, indicating an upcoming subdued session.
Outlook
BigMint expects pellet exports to remain weak in the near term, as firm domestic realisations are likely to continue discouraging sellers from pursuing overseas markets. Export activity may remain under pressure even after mid-October, with easing supply constraints unlikely to provide meaningful support unless Chinese demand strengthens and international iron ore prices recover.
Leave a Reply