- BF rebar market strengthens while IF-based markets weaken
- Flat steel prices continue uptrend following recent mill hikes
- Domestic iron ore prices edge up, coking coal remains firm
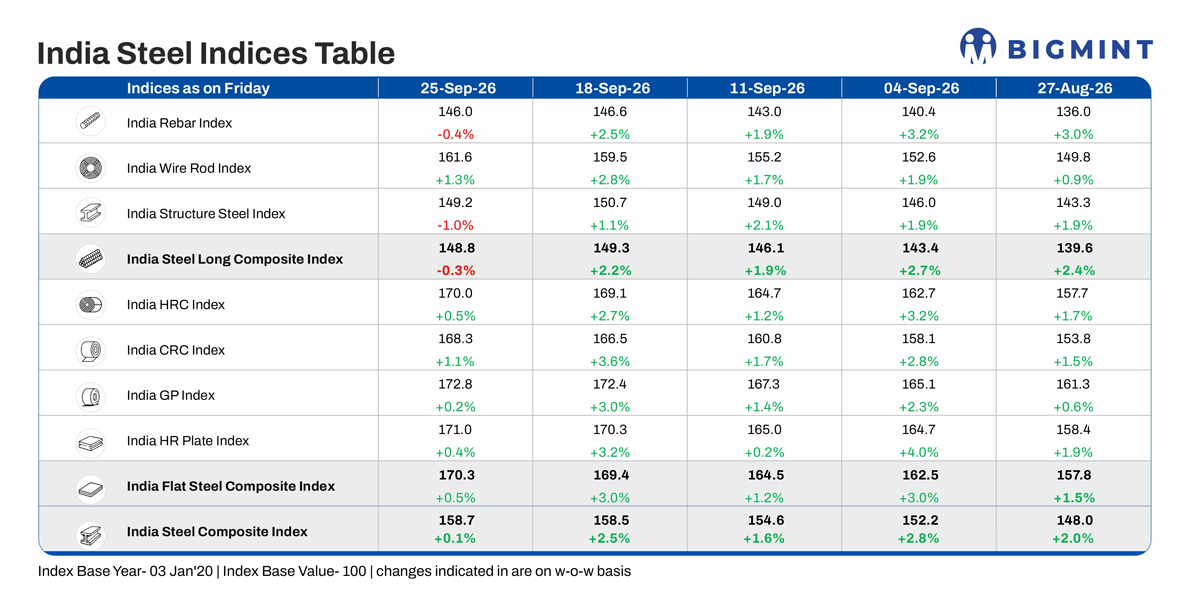
Morning Brief: BigMint’s India steel composite index increased by 0.1% w-o-w on 25 September 2026, extending its upward trend for the 10th consecutive week. Domestic steel prices are hovering at over four-year highs.
The index remained stable as gains in flat steel offset a marginal correction in long steel prices. While the market continued to benefit from improving post-monsoon demand and supportive mill pricing, buying activity selective following the sharp price increases recorded over the previous two weeks. The composite index registered a modest increase, with the flat steel segment continuing to provide support to broader market.
The domestic market was underpinned by controlled spot availability and firm mill pricing strategies. However, market participants increasingly adopted a requirement-based procurement approach as higher prices prompted caution among buyers. While demand conditions continued to improve ahead of the festive season, the pace of price appreciation moderated compared to the previous week.

The longs composite index declined by 0.3% w-o-w, while the flats composite index increased by 0.5% w-o-w. The divergence reflects a temporary correction in certain long steel markets even as flat steel products continued to gain support from recent mill price revisions.
Highlights of price movements
HRC, CRC prices remain firm on mill support, improving demand: BigMint’s benchmark assessment for HRC (IS2062, Grade E250, 2.5–8 mm/CTL) decreased to INR 63,700/t as of 25 September, down INR 200/t w-o-w from INR 63,900/t in the previous assessment on 18 September. The assessment for CRC (IS513, Grade O, 0.9 mm/CTL) increased to INR 73,800/t on 25 September, up INR 300/t w-o-w from 18 September. Prices are ex-Mumbai and exclusive of 18% GST.
The flat steel segment continued to strengthen during the week, supported by recent mill price hikes and expectations of further upward revisions. One major domestic mill has raised HRC prices by around INR 1,000/t and CRC prices by around INR 2,000/t, and these increases were reflected in the market.
Trading remained largely requirement-driven, although expectations of additional mill price hikes encouraged selective procurement. Demand in the western India remained relatively healthy, particularly for CRC, while buying interest in the north continued to be cautious. In the southern region, demand improved gradually, supported by the OEM segment. Inventory levels across key markets remained moderate, with no major supply overhang reported.

Firm domestic market supports HRC export offers: Strengthening domestic realisations continued to support India’s HRC export market. Indian export offers to the EU increased by around $10/t w-o-w to $660/t FOB as mills raised their expectations following stronger domestic prices and successful recent bookings. Approximately 25,000 t was reportedly booked into Europe for November shipment, supported by the opening of the new quota window.
Meanwhile, export offers to the Middle East and Vietnam remained on hold. Most allocations had already been committed, while stronger domestic returns encouraged mills to prioritise local sales. Chinese offers remained relatively stable, although elevated freight costs continued to limit buying interest in several overseas markets.
BF-rebar market resilient despite correction in longs index: BigMint’s assessment for rebar (IS 1786 Fe 550D, 12-32 mm, BF route) increased to INR 62,100/t as of 25 September, up INR 1,100/t w-o-w from INR 61,000/t on 18 September. Prices are ex-Mumbai for the distributor-to-dealer segment and exclude 18% GST.
Trade-level rebar prices increased on tight supply and improving demand from both project and distribution segments. Some of the integrated mills increased list prices by INR 500-1,250/t, reflecting continued confidence in market fundamentals.
Supply remained constrained across the value chain, with limited prompt availability strengthening mills bargaining power. Project enquiries improved as construction activity recovered with monsoon gradually withdrawing, while distributors increased procurement ahead of the festive period. Lean inventories and expectations of further price increases encouraged buyers to secure material despite elevated prices.
IF steel market weakens as raw material prices correct sharply: IF-route rebar prices, however, corrected by INR 500-1,400/t across major markets amid subdued trading activity, buyer resistance to higher prices and disruptions caused by heavy rainfall and festive holidays. In key markets in eastern India, price parity increased by around INR 500/t for 10-25 mm and INR 1,000/t for 8-, 6- and 32-mm rebar.

Sharp correction in sponge iron and billet prices weighed on IF-rebar prices which weighed on the overall longs composite index.
Key steel raw material prices remain strong: BigMint’s assessment of iron ore prices in the key Odisha market showed an uptrend due to tight availability. Fe 60-62% fines prices edged up by INR 300-600/t w-o-w. On the other hand, coking coal prices remained firm at $274/t FOB Australia for PHCC on 25 September. Therefore, strong prices are providing support to primary steel prices.
Outlook
The long steel market is expected to remain fundamentally supported by tight supply conditions, improving project activity and festive season restocking. However, short-term volatility may persist in IF-route markets due to cautious buying behaviour, payment disruptions related to the bank strike from 28-30 September and fluctuations in raw material prices. BF-route rebar prices are likely to remain firm if demand continues to improve.
For flat products, recent mill price increases, expectations of further hikes and stable export market sentiments are likely to support prices. While buyers are expected to remain selective at current price levels, festive demand and controlled spot availability are likely to keep prices firm. Import arrivals may provide some balance to the market, although stronger domestic consumption and mill discipline should limit any significant correction.
Leave a Reply