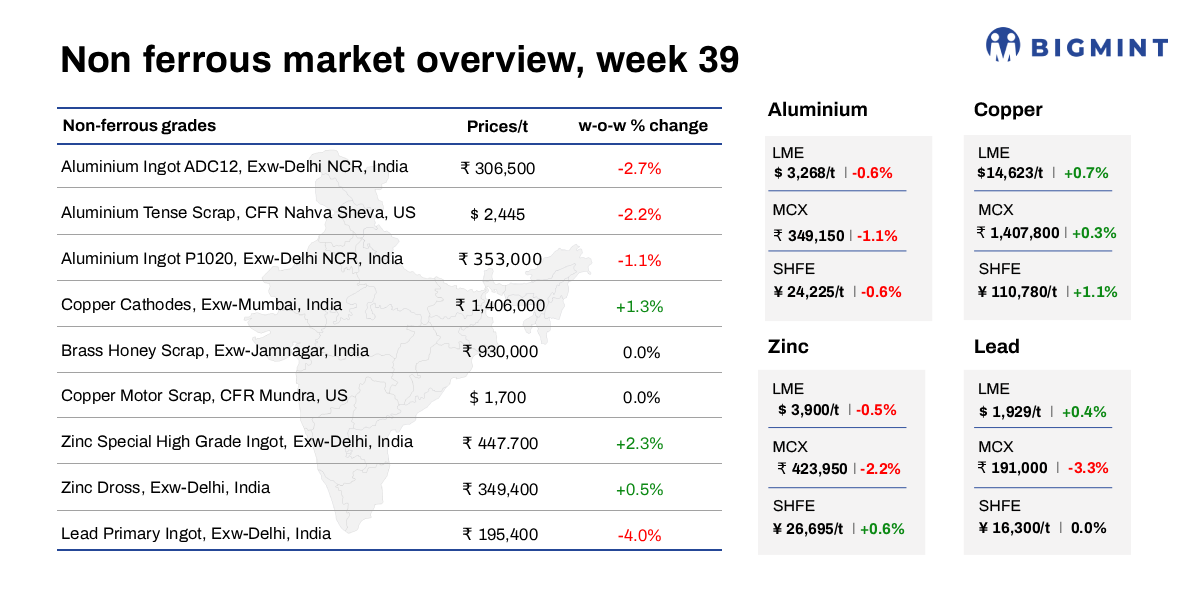
- Firm physical demand, tight availability lift LME copper prices
- Indian prices show mixed trends w-o-w amid cautious sentiment
LME base metals showed mixed movement during the week ended 25 September. Copper led gains, rising 0.7% to $14,623/t; lead followed, increasing 0.4% to $1,929/t, while aluminium and zinc declined 0.6% and 0.5% to $3,268/t and $3,900/t, respectively.
Copper remained supported by relatively firm physical demand and tight availability, while aluminium and zinc faced weaker near-term buying interest. In domestic markets, copper prices strengthened, whereas aluminium and lead declined. Zinc products remained broadly stable to firmer.
Aluminium
India’s imported aluminium scrap market remained subdued during the week. Ganesh Chaturthi holidays reduced trading activity and spot enquiries, while buyers maintained a cautious approach to procurement.
According to BigMint’s assessment, UK-origin Zorba 95-5 scrap declined by $15/t, or 0.5%, w-o-w to $2,785/t from $2,800/t. P1020 aluminium ingot prices in Delhi NCR fell by INR 4,000/t, or 1.1%, to INR 353,000/t.
In contrast, domestic aluminium tense scrap demand improved gradually as buyers increased enquiries ahead of September requirements. Declining inventories of competitively priced imported ADC12 could also encourage alloy producers to return to the market for fresh purchases.
China’s aluminium demand remained mixed. Weakness in the property sector continued to weigh on traditional construction demand, while industrial segments showed relatively better resilience. Meanwhile, China’s unwrought aluminium and aluminium product exports reached 626,000 t in August, up 17.2% y-o-y, indicating that strong overseas shipments continue to absorb part of high domestic production.
Domestic aluminium prices are expected to remain under pressure in the near term, with market direction likely to depend on LME trends, replacement costs and the pace of restocking.
Copper
India’s copper scrap market remained firm during the week, supported by higher cathode prices and tight scrap availability.
According to BigMint’s assessment, copper armature scrap, ex-Delhi, increased by INR 17,000/t, or 1.3%, w-o-w to INR 1,347,000/t from INR 1,330,000/t. Copper cathode prices ex-Mumbai rose by INR 18,000/t, or 1.3%, to INR 1,406,000/t.
Scrap availability remained relatively tight, while higher overseas offers limited the scope for aggressive import bookings. US-origin material offered to India was around 64% of LME, up from about 62% previously, as stronger domestic consumption in the US reduced export availability.
Domestic buyers remained cautious amid elevated copper prices and uncertainty over the global outlook. However, tight scrap availability and improving procurement interest provided support to secondary-market prices. Domestic copper prices are likely to remain firm in the near term, although cautious downstream buying could limit further gains.
Zinc & lead
India’s zinc market showed a mixed trend during the week, while HZL raised its benchmark zinc and lead ingot prices.
According to BigMint’s assessment, zinc dross prices ex-Delhi increased by INR 1,900/t, or 0.5%, w-o-w to INR 349,400/t. Zinc oxide (99% Zn) prices remained almost unchanged at INR 331,700/t, down marginally by INR 300/t, or 0.1%.
HZL increased its benchmark SHG zinc ingot price by INR 4,000/t to INR 424,600/t on 21 September, from INR 420,600/t previously. Its benchmark lead ingot price rose by INR 2,800/t to INR 214,200/t from INR 211,400/t.
Zinc continued to face mixed demand signals, with benchmark price increases providing some domestic support. Lead prices also benefited from firmer international markets, although domestic buying remained selective.
Domestic zinc prices are likely to track the combined impact of HZL’s revised benchmark, LME movements, and exchange trends. The gap between HZL’s benchmark and physical-market assessments will remain an important indicator for domestic price direction in the coming sessions.
Leave a Reply