- China’s 3.7% production decline keeps global output under pressure
- India, North America and non-EU Europe provide key production growth
- Middle East and Russia-CIS remain the main regional drags outside China
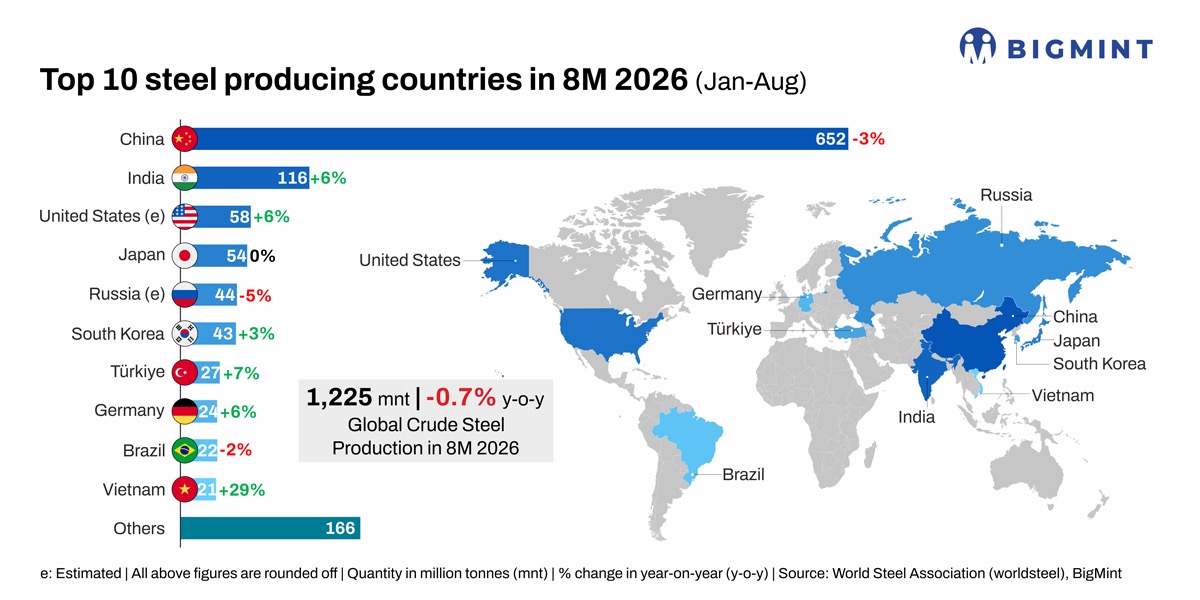
Morning Brief: Global crude steel production fell 1.2% y-o-y to 144.2 mnt in August 2026, with lower output in China, the Middle East and Russia-CIS outweighing gains across India, North America and parts of Europe. January-August production across the 70 countries tracked by the World Steel Association stood at 1,225.2 mnt, down 0.7% y-o-y, keeping global output slightly below last year’s level.
Chinese production continues to fall
China produced 74.6 mnt of crude steel in August, down 3.7% y-o-y, while January-August output fell 3.1% to 651.9 mnt. The decline continued to dominate the global production trend given China’s scale, with weaker property-related demand and construction activity weighing on steel consumption, while manufacturing and infrastructure provided relatively stronger support.
The decline in China was only partly offset elsewhere in Asia. Asia and Oceania produced 106.7 mnt in August, down 1.4%, while January-August output declined 0.9% to 906.4 mnt. India’s production rose 4.6% y-o-y to 14.8 mnt in August and 6% to 115.9 mnt in January-August. Vietnam recorded the strongest increase among major producers, with August output up 36.4% to 2.7 mnt and January-August production up 29.2% to 20.6 mnt. South Korea increased August production 2.6% to 5.4 mnt. Japan was broadly stable at 6.7 mnt, up 0.4%.
India emerges as a key offset to China’s decline
India produced 14.8 mnt of crude steel in August, up 4.6% y-o-y, while January-August output rose 6% to 115.9 mnt. With China cutting production by 3.1% during the first eight months, India’s continued expansion is becoming an increasingly important counterweight within the global production base.
India’s growth also stands out against the broader global trend. World crude steel production fell 0.7% during January-August, while India’s output increased by roughly 6.5 mnt y-o-y. The country’s August production of 14.8 mnt was also more than double Japan’s 6.7 mnt and substantially above South Korea’s 5.4 mnt.
Vietnam provided another strong source of Asian growth, with August production rising 36.4% y-o-y to 2.7 mnt and January-August output increasing 29.2% to 20.6 mnt. South Korea rose 2.6% in August, while Japan was broadly stable at 6.7 mnt.
Growth is shifting toward India and North America
North America remained one of the strongest growth regions, with August crude steel production rising 3.9% y-o-y to 9.4 mnt and January-August output increasing 5.2% to 75.3 mnt. US production was estimated at 7.3 mnt in August, up 3%, with January-August output rising 5.5% to 57.5 mnt.
Africa also recorded strong percentage growth, although from a much smaller production base. Regional output increased 8.8% y-o-y to 2.1 mnt in August and 9.4% to 16.7 mnt during January-August.
Europe remains uneven
EU-27 production rose 1% y-o-y to 8.9 mnt in August, but January-August output remained marginally lower at 84.5 mnt, down 0.3%. Europe outside the EU performed better, with August production increasing 1.2% to 3.8 mnt and January-August output rising 4.8% to 29.5 mnt.
Germany continued to outperform the wider European market. August crude steel production increased 1.7% to 2.6 mnt, while January-August output rose 6.3% to 23.9 mnt. Turkiye also recorded a mixed monthly and cumulative trend, with August output down 0.4% to 3.4 mnt but January-August production up 6.8% to 26.6 mnt.
Middle East and Russia-CIS deepen the decline
The Middle East remained one of the weakest regional markets, with crude steel production falling 4.6% y-o-y in August to 3.7 mnt and 7.8% during January-August to 33.3 mnt.
Russia, other CIS countries and Ukraine also continued to contract. Regional output fell 5.6% y-o-y to 6.3 mnt in August and 5.7% to 52 mnt during January-August. South American production declined 4.9% to 3.4 mnt in August, while January-August output was down 0.7% at 27.5 mnt.
Outlook
The global production decline remains concentrated rather than broad-based. China’s January-August contraction is being partly offset by higher output in India, Vietnam, North America, Africa and Europe outside the EU, while weaker production in the Middle East, Russia-CIS and South America is adding to the global decline.
With global January-August production down only 0.7%, the key market shift is the changing regional contribution to steelmaking. China’s lower output is reducing the weight of the world’s largest producer, while India and several other growth markets are taking a larger share of incremental global production. The final months of 2026 will show whether that redistribution is sufficient to keep global output close to 2025 levels.
Leave a Reply