- Rebar market faces pressure from ample supply
- High billet costs limit scope for price cuts
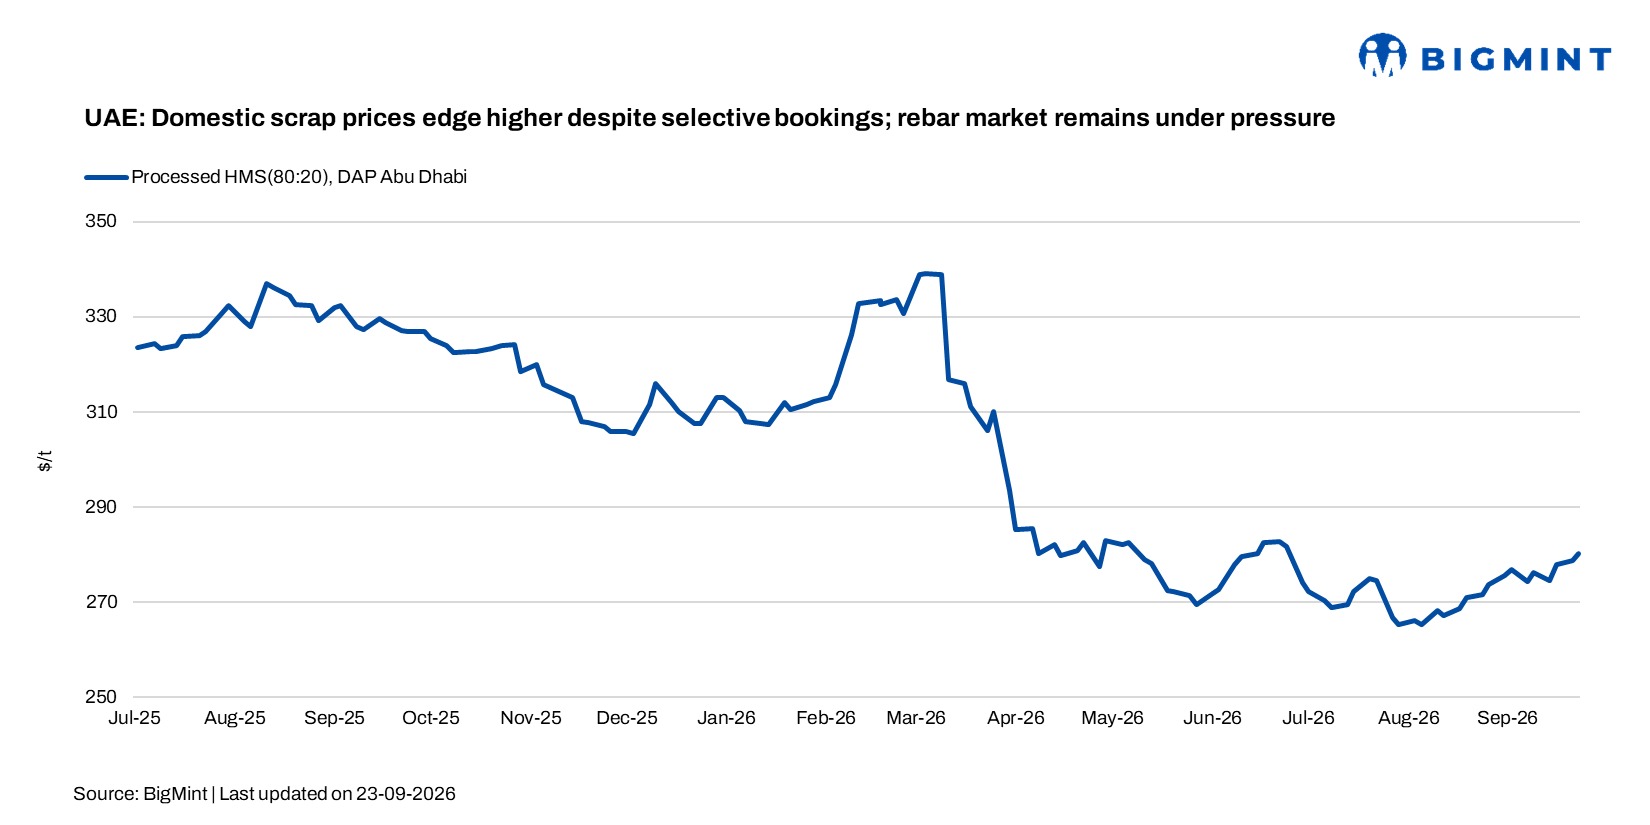
UAE scrap prices edged higher during the week, with processed HMS 80:20 assessed at AED 1,030/t ($280/t) DAP Abu Dhabi, up AED 9/t ($2/t) w-o-w. Workable levels were heard at around AED 1,025-1,030/t ($279-280/t) for HMS processed, while shredded was around AED 1,125-1,140/t ($307-310/t) DAP Abu Dhabi.
Market sentiment remained stable after Emirates Steel rolled over its October rebar sales price. However, fresh scrap buying remained limited, with mills mainly completing earlier bookings.
“We are completing the old bookings. There are no new bookings this week,” a major Dubai-based trader source said.
Another trader said the last workable levels were around AED 1,030-1,035/t ($280-282/t) from one of the major steelmakers and AED 1,025-1,030/t ($279-280/t) from another mill.
An Abu Dhabi-based supplier source said they haven’t heard any new quotes from AGSI during the week.
A recent HMS processed deal was reported around AED 1,010/t ($275/t), while PNS was around AED 1,080/t ($294/t) for a 500-1,000 t lot.
Rebar demand remains subdued
The UAE rebar market is facing renewed pressure as ample supply and cautious purchasing weigh on transaction levels.
Non-benchmark suppliers were heard indicating October prices around AED 2,820-2,840/t ($768-773/t), below September transaction levels. One producer has since indicated around AED 2,810-2,820/t ($766-769/t), while traders are seeking prices around AED 2,790-2,800/t ($760-763/t) and below levels.
Retail rebar offers have also moved down to around AED 2,900/t ($790/t), compared with AED 2,940-2,950/t ($801-803/t) previously. The decline is putting pressure on traders holding higher-cost inventory.
Demand indicators remain uneven. Some re-rollers reported active buying, while other market participants said consumption has remained subdued following the summer slowdown.
“Demand is likely weaker in the coming month, and we will try to maintain current prices, although market activity remains slow,” another market insider said. Monthly UAE rebar consumption is estimated at 400,000 t.
Scrap outlook
Scrap prices are likely to remain supported by collection and replacement costs, but subdued finished-steel demand is limiting mills’ willingness to accept higher scrap prices. With no significant fresh bookings reported this week, buying is expected to remain cautious. At the same time, elevated billet costs and mills’ resistance to further rebar price cuts could limit the downside for scrap prices.
Leave a Reply