- Chennai scrap prices hold steady amid sluggish steel demand
- Billet prices decrease by INR 1,000/t w-o-w
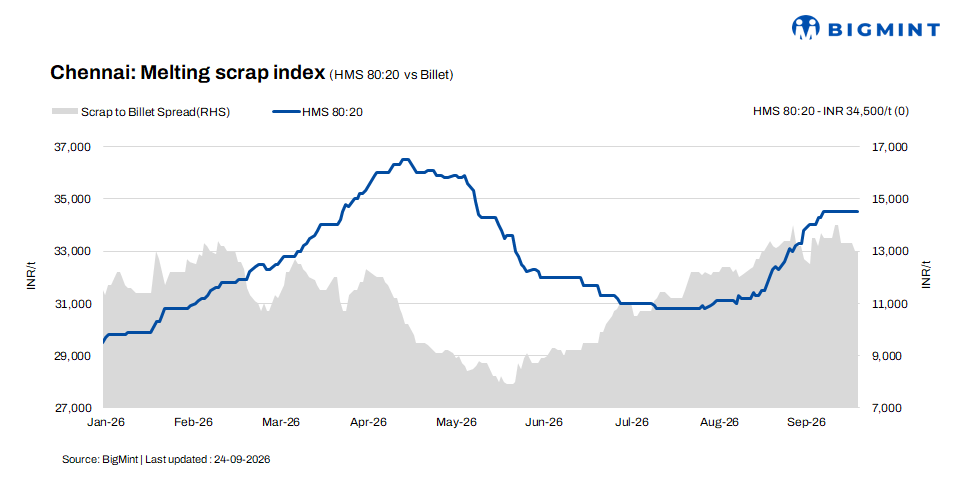
According to BigMint’s latest assessment, HMS (80:20) scrap prices in Chennai remained stable at INR 34,500/t, with no change observed on either a day-on-day or week-on-week basis. In the semi-finished steel segment, billet prices remained unchanged d-o-d at INR 47,500/t, while recording a weekly decline of INR 1,000/t. Similarly, rebar prices held steady on a daily basis but fell by INR 300/t w-o-w to INR 50,200/t. The divergent movement highlights stable scrap pricing despite softer weekly trends in finished and semi-finished steel.
Imported and domestic price trends
Market participants reported that Australia-origin shredded scrap was offered at $380-382/t CFR Chennai, while HMS (80:20) was quoted at $360-362/t CFR. Buyers remained cautious, with bid levels trailing prevailing offers by around $10-15/t, resulting in a significant bid-offer gap. Despite the shortage of imported bookings, domestic scrap continued to remain the more economical procurement option, limiting buying interest for imported material and keeping import trade activity muted in the Chennai market.

In the domestic market, HMS (80:20) scrap prices were quoted at INR 34,500-34,800/t for spot transactions with immediate payment, while extended credit-term deals were concluded at INR 34,800-35,500/t. Overall, market activity remained concentrated within the INR 34,500-35,500/t range, highlighting balanced demand-supply dynamics despite cautious procurement sentiment.
Market participants indicated that payment terms, procurement volumes, and mill-specific requirements continued to influence transaction prices, with premiums observed for deals involving longer credit periods.
Buyer-supplier sentiments
A mill representative shared with BigMint that buyers are adopting a cautious approach to bulk bookings ahead of the expected onset of the monsoon season in Chennai next month. Seasonal disruptions are likely to slow construction activity and weigh on finished-steel demand, reducing buyers’ willingness to build inventories. At the same time, the upcoming festive period is expected to further limit trading activity and market participation. Buyers are therefore focusing mainly on immediate requirements rather than committing to larger volumes.
According to the representative, the combination of monsoon-related uncertainty and the approaching festival season is keeping market participants cautious. These factors are expected to weigh on finished-steel demand and could limit scrap procurement activity in the near term.
A leading scrap supplier shared with BigMint that HMS (80:20) scrap is currently trading at INR 34,500-35,500/t, with prices varying according to payment terms. Scrap prices have remained largely stable, as buyers and sellers continue to assess market conditions. However, weaker billet and rebar demand is raising concerns over mills’ conversion economics.
If finished-steel demand remains subdued, mills may attempt to negotiate lower scrap procurement prices to protect margins. This could increase selling pressure and influence price expectations in the coming days. According to the supplier, the market will closely track finished-steel demand, mill operating economics and procurement activity, which are likely to determine the direction of Chennai scrap prices in the near term.
Outlook
Chennai HMS (80:20) scrap prices are expected to remain range-bound with a slightly weak bias in the near term, as weekly declines in billet and rebar prices weigh on market sentiment. Buyers are likely to maintain a cautious, requirement-based procurement approach amid subdued finished-steel demand. However, stable current scrap prices and limited willingness among suppliers to reduce offers may provide some downside protection. Overall, HMS (80:20) scrap prices are expected to remain range-bound, with fluctuations limited to around INR +/- 200-500/t.
Leave a Reply