- Some DRI producers shifting to pellets amid limited high-grade ore supply
- Healthy auction response supports prices, weak DRI demand limits gains
Karnataka iron ore prices remained firm during the assessment week ended 24 September 2026, supported by tight availability of quality ore and a healthy response in recent auctions. However, downstream markets remained under pressure, with sponge iron and finished steel prices witnessing a sharp correction, leading buyers to adopt a cautious, need-based procurement approach.
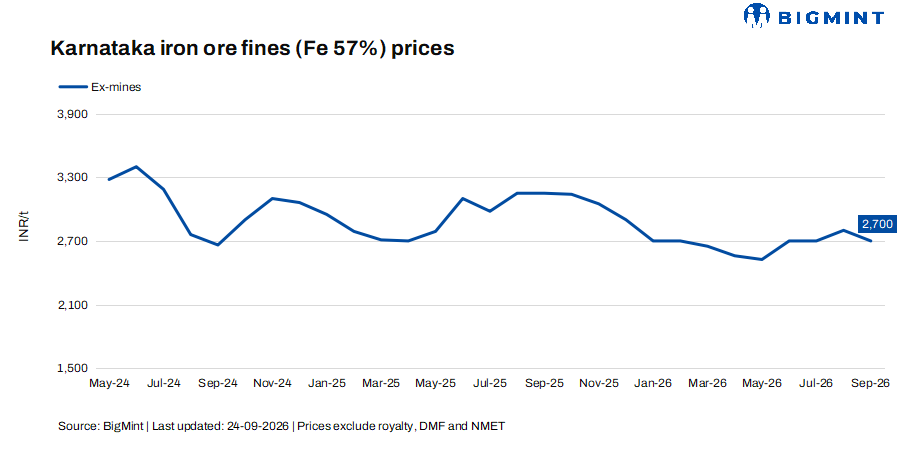
According to BigMint’s latest assessment, Fe 57% iron ore fines prices remained stable w-o-w at INR 2,700/t ($28/t) ex-mines, despite sluggish demand. Buyers continued to remain selective, with limited preference for low-grade material amid quality constraints and weaker sponge iron realisations.
Meanwhile, Fe 62% fines prices increased by INR 50/t ($0.5/t) w-o-w to INR 5,250/t ($55/t) ex-mines, supported by tight availability of suitable high-grade ore. Market participants noted that consumers are increasingly willing to pay a premium for quality material, while some sponge iron producers are shifting towards pellets amid difficulties in securing suitable iron ore.
Auction activity remained moderate during the week, while buyer participation continued to be encouraging. The healthy response in recent auctions has kept miners’ price expectations elevated, limiting any immediate downward correction in iron ore prices despite weakness in finished steel and sponge iron.
Market participants indicated that the decline in downstream prices has not yet translated into a significant correction in iron ore, mainly because raw-material costs remain elevated, particularly coal. Producers are also relying on existing inventories amid monsoon-related supply constraints.
One buyer commented, “Sponge prices are falling, but iron ore prices are still firm as coal prices remain very high. Due to rains, local coal availability is low. Once mining resumes, material availability should improve. We are currently using old stocks. Further price increases may be difficult.”
Rationale
- One (1) trade via e-auction was recorded for Fe 57% in this publishing window and was taken into consideration. Hence, the T1 trade category was accorded 50% weightage.
- Fourteen (14) offers and indicative prices were reported, out of which ten (12) were considered as T2. These were accorded 50% weightage.
Influencing factors
- C-DRI prices fall sharply by INR 1,100/t ($11/t) w-o-w in Bellary: Bellary lump-based sponge iron (C-DRI) prices declined by INR 1,100/t ($11/t) w-o-w to INR 30,700/t ($320/t) amid weak demand from neighbouring markets. The correction in finished steel prices has further encouraged buyers to restrict purchases to immediate requirements. Market participants expect sponge iron prices to remain volatile in the near term, keeping pressure on raw-material procurement.
- Imported coal prices remain elevated: South African thermal coal prices at Indian ports remained firm despite subdued market activity and softer bids. Ex-Paradip RB2 (5,500 NAR) increased by INR 200/t w-o-w to INR 13,500/t, while RB3 declined by INR 100/t to INR 11,500/t. Ex-Vizag RB2 rose by INR 150/t to INR 13,400/t, whereas RB3 declined by INR 50/t to INR 11,500/t. Elevated imported coal offers, coupled with weaker sponge iron demand, continued to limit fresh buying interest.
Karnataka iron ore sales scenario (18- 24 September 2026)

Outlook
Iron ore prices are expected to remain rangebound to slightly lower in the near term, with downstream weakness limiting upside. However, elevated coal costs, tight availability of quality ore, and firm miner offers could provide support and prevent a sharp correction.
Leave a Reply