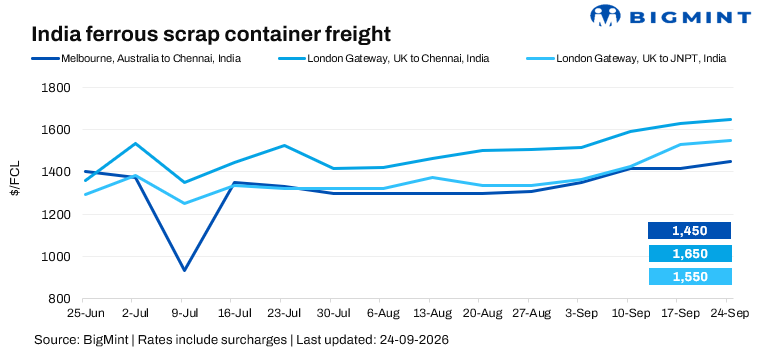
- Tight container availability, higher bunker costs support freight rates
- Weak scrap demand, competitive domestic supply limit fresh bookings
India-bound ferrous scrap container freight rates remained firm w-o-w on 24 September, supported by tight container availability, higher carrier costs and elevated bunker prices. However, the firmness in freight was not driven by stronger scrap demand, as weak downstream activity, production cuts and competitive domestic scrap continued to limit import appetite.
India’s scrap market sentiment remained subdued, with weak downstream demand and lower production limiting fresh buying. Competitive domestic scrap availability continued to reduce import appetite, while elevated freight and overseas offers kept imported material relatively expensive.
A shipbroker stated, “Ongoing market volatility has led to production cuts in some parts of India, limiting immediate scrap demand. With adequate domestic scrap availability, Indian buyers continue to benchmark import prices against local material before committing. As a result, import requirements remain selective, with buyers relying primarily on domestic supply and importing only a limited share despite relatively higher import prices.”
Another shipbroker stated, “Elevated freight costs pressuring import parity. Buyers remain cautious on fresh bookings, while tight container availability supports rates.”
A shipowner informed BigMint “Import requirements remain, with port-based manufacturers maintaining a balance between domestic and imported scrap depending on local price indications. If domestic prices rise, buyers are likely to shift toward nearby origins that can offer quicker deliveries, typically within 15 days, subject to vessel availability.”

Market highlights
- SCFI rises w-o-w: The Shanghai Containerized Freight Index (SCFI) increased 0.7% w-o-w to 3,687.83/twenty-foot equivalent unit (TEU) on 18 September, from 3,662.18/TEU on 11 September. Firmer Transpacific rates supported the overall index, while Europe-bound rates softened amid weaker post-summer demand and improving Suez capacity.
- Bunker costs remain elevated: Singapore bunker prices stood at around $887/tonne (t) on 24 September, rose w-o-w by $884/t on 17 September, keeping carrier operating costs elevated and providing continued support to freight offers.
Outlook
India-bound scrap freight rates are expected to remain firm in the near term, supported by tight container availability and elevated operating costs. However, weak Indian scrap demand, competitive domestic material and higher import parity are likely to keep bookings selective. If domestic scrap prices rise, port-based buyers could increase imports, particularly from nearby origins offering faster delivery, subject to vessel availability.
Leave a Reply