- SE Asian-origin bookings support imported scrap market
- High-priced European and Japanese cargoes face buyer resistance
Bangladesh’s imported scrap market remained firm this week, although buying was selective as mills continued to focus on prompt requirements and delivered economics. Seorigin material remained competitive, while elevated offers from Europe and Japan faced resistance. Malaysian PNS offers were heard at $410–415/t CFR Chattogram, while Singapore-origin PNS was offered at around $420-425/t CFR.
Malaysian shredded was workable around $405/t CFR, while HMS (90:10) was indicated at around $380/t CFR.
BigMint’s weekly assessments, CFR Chattogram
- European-origin containerised HMS 80:20: $372/t, stable w-o-w
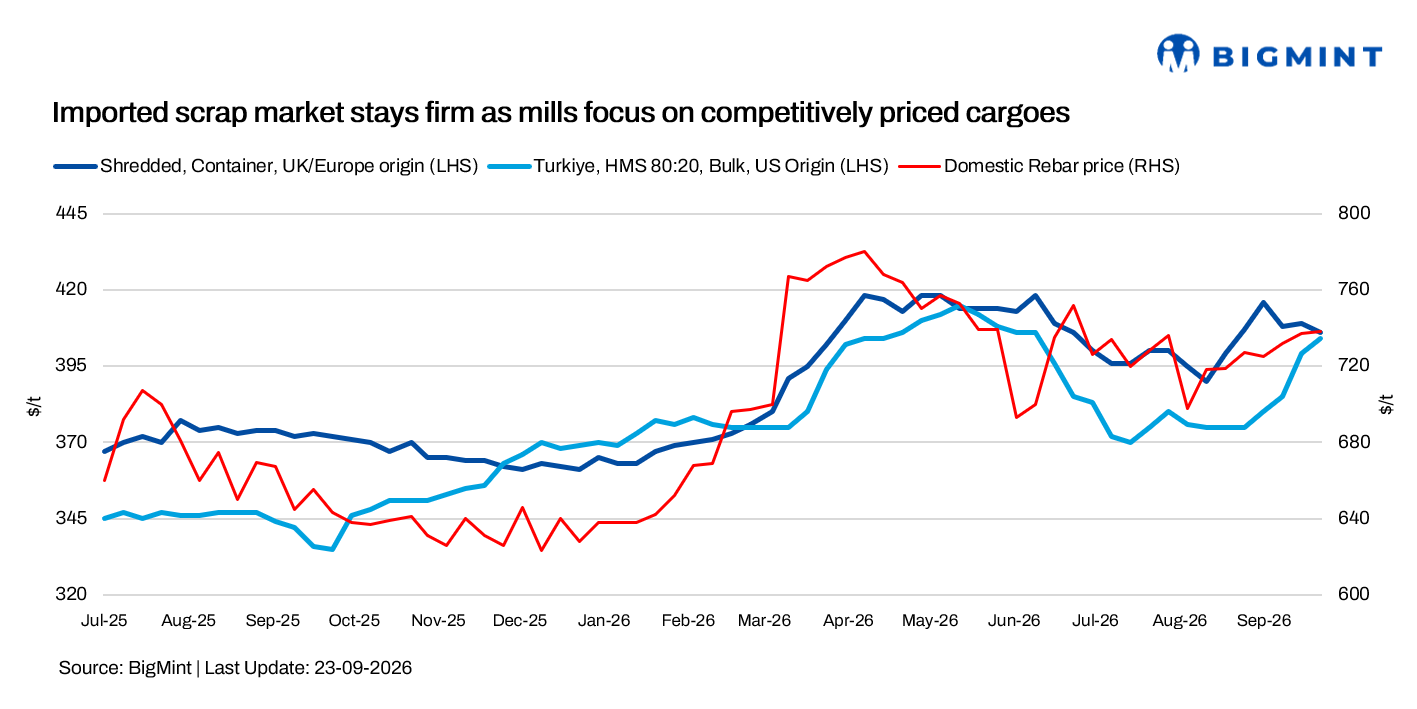
- European-origin containerised shredded: $406/t, down by $3/t w-o-w
- Japanese-origin bulk H2: $395/t, up $2/t w-o-w
- US-origin bulk HMS 80:20: $401/t, up $2/t w-o-w
Market scenario
Small- and medium-sized mills continued to favour containerised scrap from East Asian countries and Australia because of shorter transit times and more competitive freight compared with European material. No fresh US-origin trades were reported this week as market activity slowed and prices softened.
In the bulk segment, Singapore-origin HMS (80:20) was reportedly traded at around $385/t CFR last week. US-origin HMS (80:20) was available around $400/t CFR, up from $380-385/t in early September, supported by firmer US domestic scrap prices and stronger Turkish demand.
Japan and Singapore/Hong Kong bulk H2 and PNS were heard around $395-400/t.
Recent containerised scrap trades
- 3,000 t Malaysian PNS booked at $410-412/t CFR Chattogram
- 2,000 t of Philippines-origin mixed PNS and HMS 80:20 scrap booked at $376-383/t CFR Chattogram
- 500 t of Philippines-origin GI bundles were booked at $328/t CFR Chattogram
Domestic market
Local scrap prices remained firm; HMS scrap was indicated at BDT 56,000-58,000/t ($456-472/t), while PNS stood at BDT 60,000-62,000/t ($488-504/t).
Rebar prices remained stable at around BDT 83,000-85,000/t ($675-692/t) in Dhaka and BDT 90,000-92,000/t ($732-748/t) in Chattogram.
The firm domestic scrap market is keeping replacement costs elevated, but weak long-steel demand and subdued construction activity are limiting mills’ willingness to chase higher imported scrap prices. Buyers therefore remain focused on prompt requirements and delivered-cost comparisons.
Outlook
Bangladesh’s imported scrap market is expected to remain firm but selective in the coming week. SE-origin containerised scrap is likely to remain competitive for smaller and medium-sized mills, while elevated Japanese and European offers could continue to face resistance. The key market driver will remain the balance between firm international scrap costs and weak domestic steel demand. Further price gains could be difficult unless rebar sales and mill procurement activity improve.
Leave a Reply