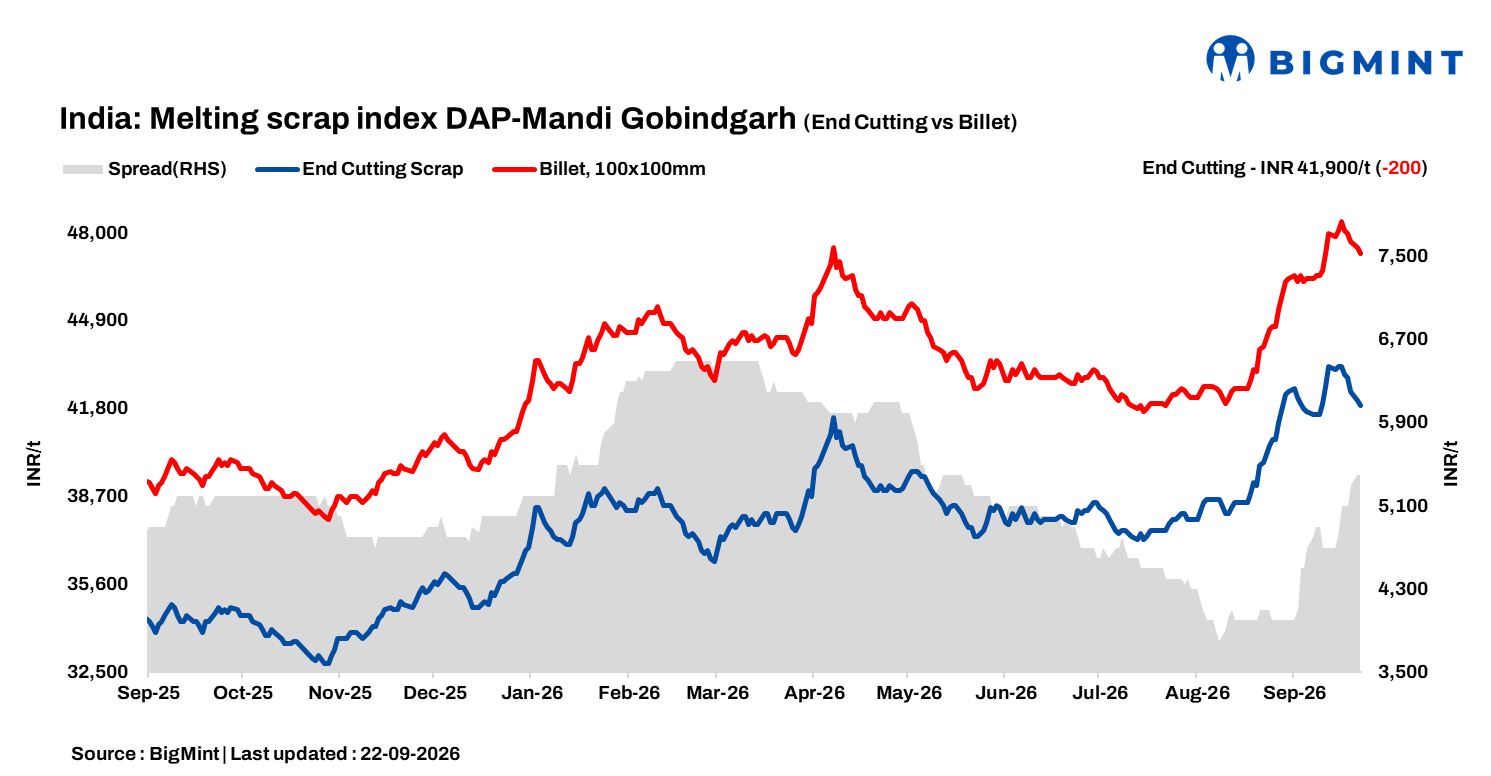
- Steel prices decline INR 200-500/t d-o-d
- Buyers remain cautious amid elevated inventories
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, eased by INR 200/tonne (t) d-o-d to INR 41,900/t DAP on 22 Sept 2026. The Mandi Gobindgarh steel market remained under pressure today, with scrap and finished-steel prices declining by INR 200-500/t d-o-d. Over the past week, prices have corrected by INR 800-1,700/t, reflecting cautious market sentiment and weak finished-steel demand.
Scrap buying activity remained slow despite steady arrivals. However, a few local steelmakers reported that buyer inquiries have started to improve following the sharp price correction. Market participants are hopeful that prices may stabilise and recover once the current decline eases.
Finished-steel demand continued to be subdued, as end-users remained largely inactive amid surplus inventory in the region. The combination of weak consumption and elevated stock levels is likely to keep market sentiment cautious in the near term.
Alternative raw material prices
Sponge iron (CDRI) prices in Mandi Gobindgarh remained stable d-o-d at INR 34,000/t DAP, reflecting subdued demand and cautious mill procurement. Meanwhile, steel-grade pig iron prices in Ludhiana continue to decline INR 300/t d-o-d to INR 43,500/t DAP, indicating soften buying conditions in the segment.
Steel market
Semi-finished steel prices in Mandi Gobindgarh decreased by INR 200/t d-o-d to INR 47,300/t DAP. Prices across other major steel-producing centres also declined by approximately INR 200-500/t, highlighting broad-based weakness in the secondary steel market.
In the finished-steel segment, Fe500 rebar prices in Mandi Gobindgarh fell by INR 300/t d-o-d to INR 52,700/t ex-works, reflecting subdued buying interest and cautious trading activity. HR strip, or patra, prices also declined by INR 500/t to INR 51,300/t ex-works, extending the ongoing downtrend. Overall, weak downstream demand, limited mill procurement and pressure on selling prices continued to weigh on market sentiment.
Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 5,200-5,600/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $374/t, approximately INR 38,050/t (inclusive of freight). HMS (80:20) prices in Mumbai dipped by INR 100/t to INR 36,500/t DAP. Indicative prices of shredded from Europe stood at $414/t CFR Nhava Sheva.A leading steelmaker booked approximately 1,500 t of HMS (90:10) scrap at INR 37,500-37,700/t DAP Mumbai.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 15,900/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply