- One major mill raises HRC and CRC
- Southern inventories remain at 60-70% levels
India’s hot-rolled coil (HRC) market remained largely stable to higher as of 22 September 2026, with trade-level prices increasing by around INR 200-500/t across most key markets. However, one market recorded a decline of around INR 400/t in HRC, while CRC prices in the same market decreased by around INR 500/t. No fresh price hikes were announced by domestic steel mills during the period.
Trade-level CRC prices increased by around INR 200-1,700/t across other key markets, with the extent of movement varying by region. Buying activity for both HRC and CRC remained largely requirement-driven, with buyers maintaining a cautious approach at current price levels and limited inventory accumulation reported.
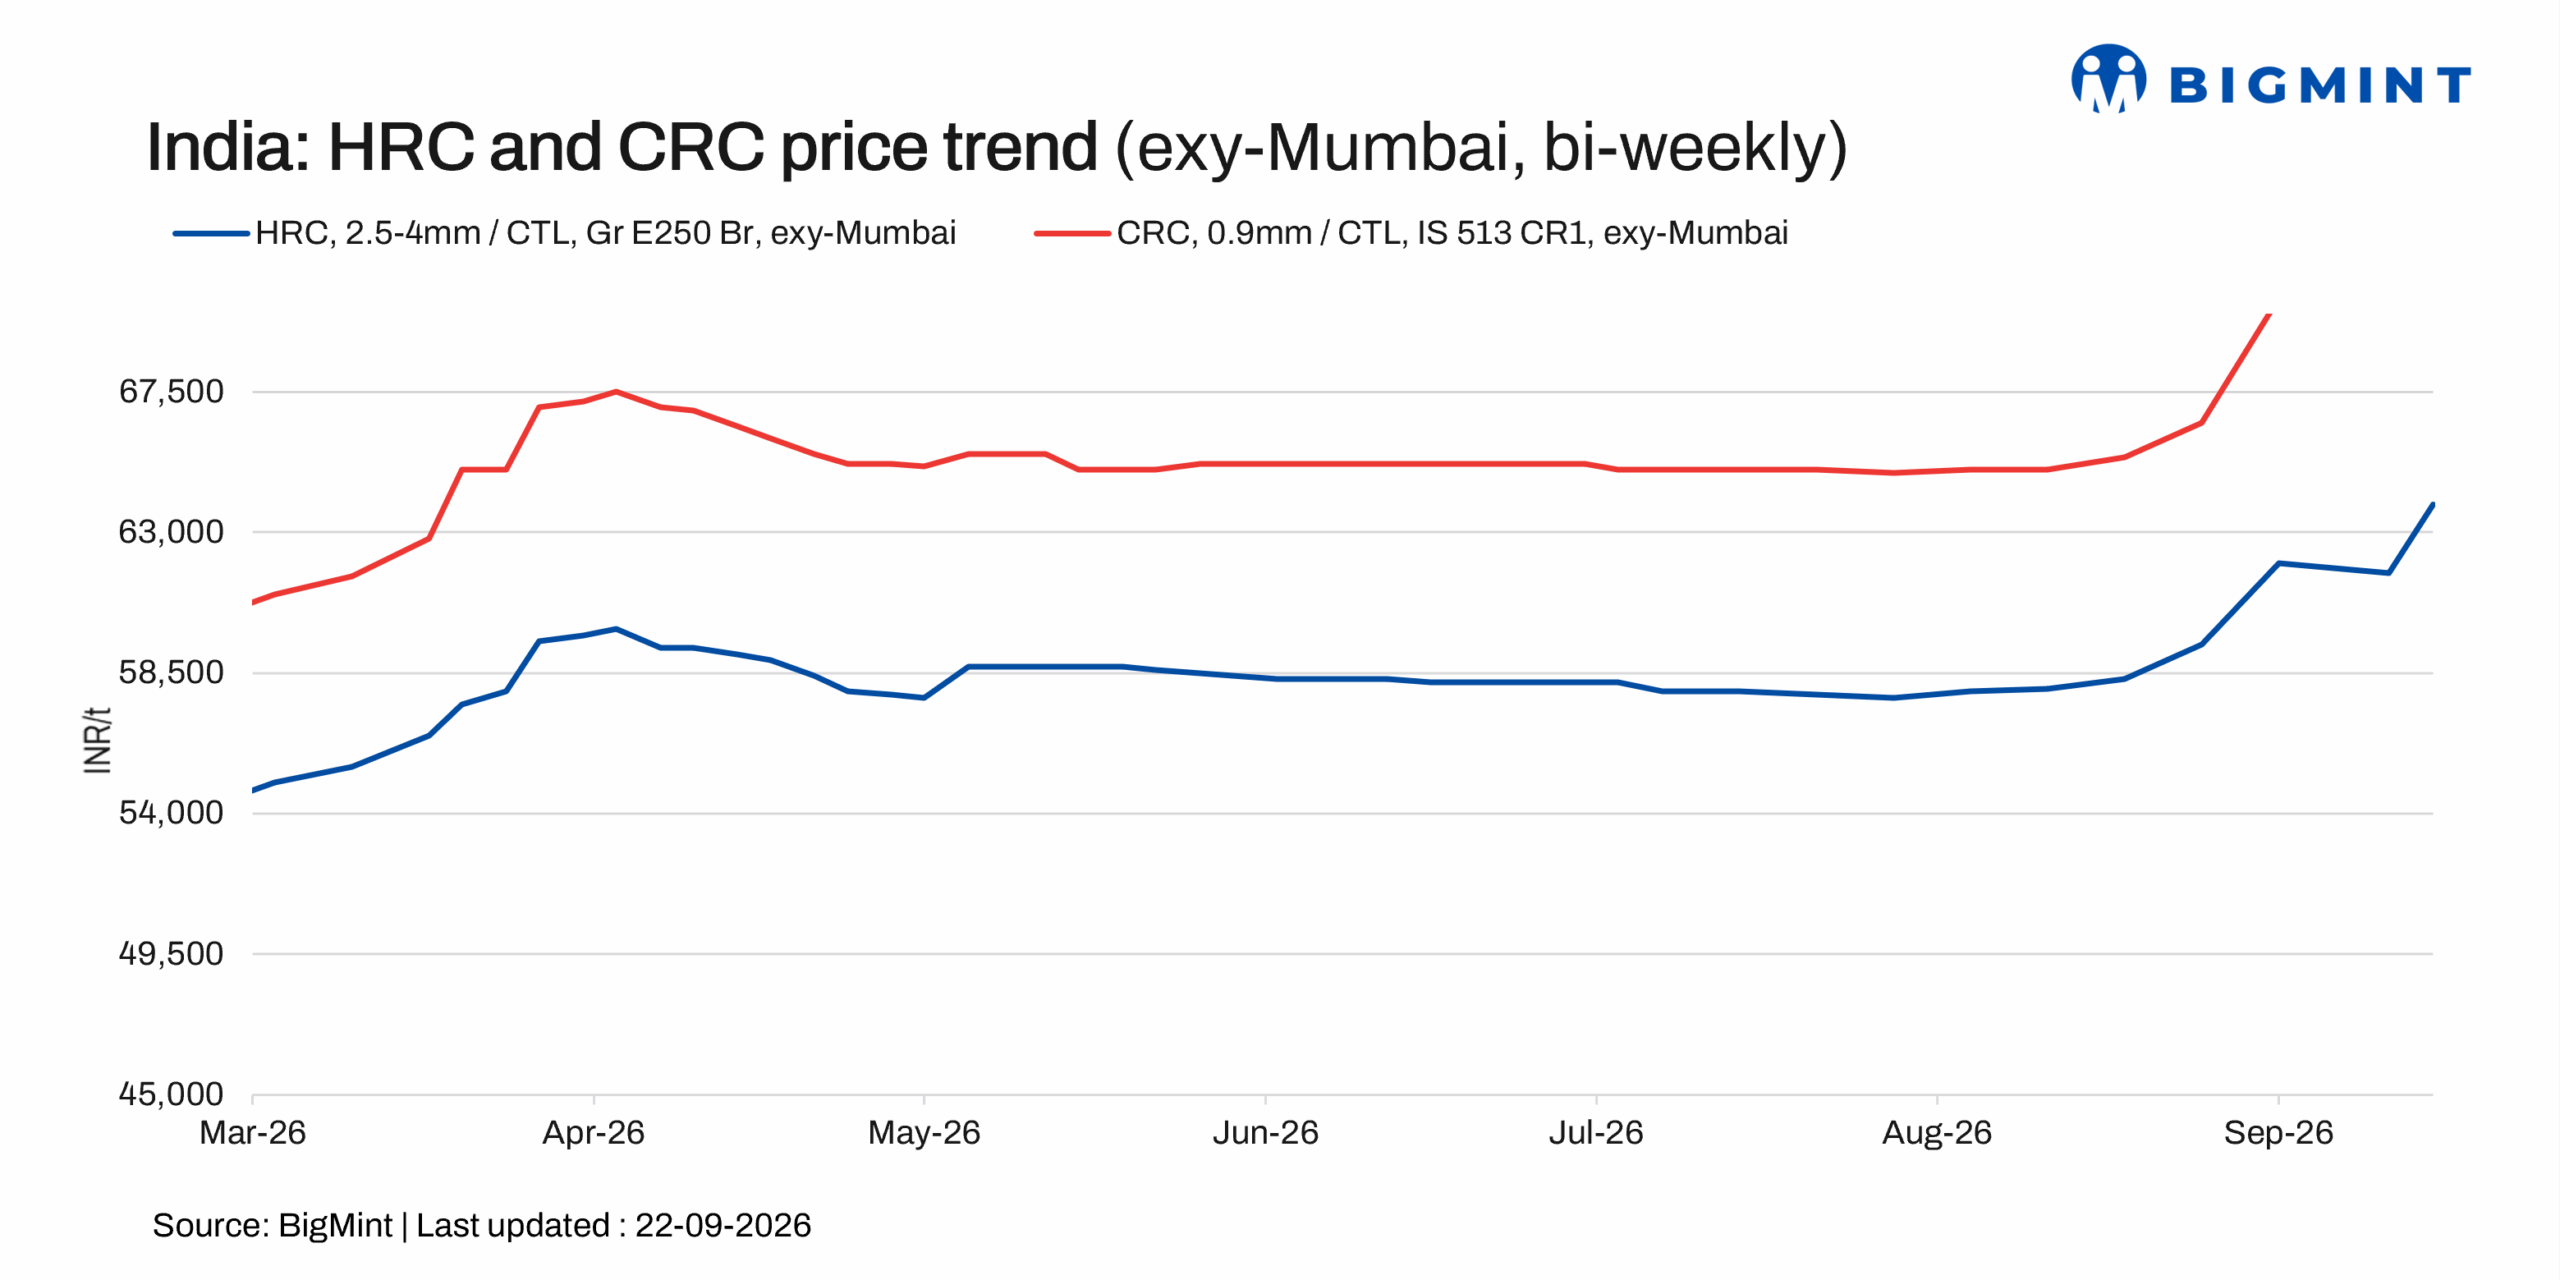
BigMint’s bi-weekly benchmark assessment for Mumbai HRC (IS2062, Grade E250, 2.5-8 mm/CTL) increased by INR 200/t w-o-w to INR 63,900/t ex-Mumbai as of 22 September 2026.
Meanwhile, Mumbai CRC (IS513, Grade O, 0.9 mm/CTL) was assessed at INR 73,700/t ex-Mumbai, up by INR 500/t w-o-w.

Market update
HRC demand remains moderate across key markets, with buying activity differing by region. Buyers are mainly purchasing as per their immediate needs, while expectations of further price increases are encouraging some buyers to procure material. One major domestic mill has raised HRC prices by around INR 1,000/t and CRC prices by around INR 2,000/t, and these increases have been reflected in the market.
In the western market, CRC demand remains relatively strong, with buyers continuing to procure material despite higher price levels. Market participants expect prices to remain supported and potentially increase further through the festive season, while demand is expected to improve over the next two months.
In the northern market, CRC demand remains largely need-based, with buying interest yet to fully align with recent price increases. Buyers are restricting purchases to immediate requirements and remain cautious about inventory accumulation at current price levels.
In the southern market, demand has shown some improvement, particularly from the OEM segment. Inventory levels are estimated at around 60–70% of normal levels, while overall buying remains selective.
A market participant said that prices could increase further in the coming week as mills are expected to announce additional hikes. However, market acceptance of higher price levels remains uncertain.
Overall, inventory levels remain moderate, with no significant build-up or shortage reported across key markets.
Trade scenario
Import volumes: India’s bulk HRC imports stood at 83,684 tonnes (t) as of 18 September 2026, with a further 83,260 t expected to arrive by the end of September. A significant portion of these imports is being undertaken under long-term agreements between Indian companies and their parent entities in South Korea and Japan.

Export volumes: India’s bulk HRC exports stood at 277,476 t as of 18 September 2026, with another 84,950 t expected to be shipped by the end of this week.
Outlook
HRC and CRC prices are expected to move higher in the near term, supported by recent upward revisions from a major domestic mill and expectations of further increases in the coming weeks. The festive season could provide additional support to consumption as buyers gradually increase procurement.
However, the pace of price gains may remain uneven across regions, as buyers are likely to remain cautious at elevated levels and continue purchasing primarily against confirmed requirements. The extent to which further mill-led increases translate into higher transaction prices will depend on market acceptance and the pace of demand improvement.
Import arrivals and the availability of material in the spot market could provide some counterbalance to the upward price movement, although stronger domestic consumption and continued mill price support may limit any significant downward correction.
Leave a Reply