- Flat steel market strengthens on price hikes by major mills
- BF-route rebar prices climb higher amid tightening supplies
- Firm domestic HRC prices enable mills to raise export offers
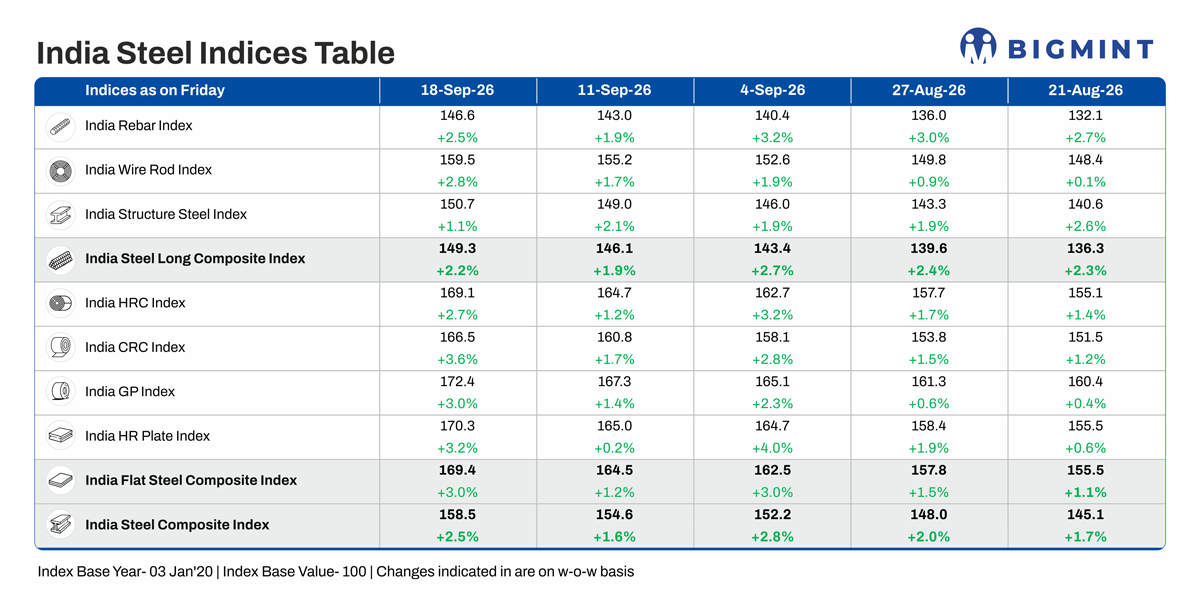
Morning Brief: BigMint’s India steel composite index increased by 2.5% w-o-w on 18 September 2026, extending its rally for the ninth consecutive week and reaching its highest level in more than four years. The index edged higher as prices strengthened across both long and flat steel segments, supported by lean inventories, improving post-monsoon demand, and continued supply discipline adopted by the major mills.
The domestic market gained momentum following mid-month price hikes announced by the major steelmakers. Buyers accelerated procurement amid expectations of additional increases, while mills maintained controlled spot availability across both long and flat products. The resulting combination of tighter supply and improving demand continued to support prices.

The longs composite index increased by 2.2% w-o-w, while the flats composite index rose by 3% w-o-w, with flat products leading the gains following significant mill price revisions.
Highlights of price movements
HRC, CRC prices rise on mill hikes, restocking demand: The flat steel segment recorded the strongest gains during the week following mid-month price revisions by domestic mills.
Major producers increased HRC prices by around INR 750-1,750/t and CRC prices by INR 1,500-2,250/t, prompting corresponding increases across trade markets.
BigMint’s benchmark Mumbai HRC assessment rose by INR 1,200/t to INR 63,900/t ex-Mumbai, while CRC prices increased by around INR 1,300/t to INR 73,500/t ex-Mumbai.

Market enquiries increased noticeably after the mill announcements as buyers sought to secure material before further price increases. While purchases remained largely requirement-based, distributors and end-users stepped up procurement and selective restocking activity.
On the supply side, mills continued to manage dispatches strategically and maintained controlled spot availability. Material allocation remained focused on existing commitments and priority customers, limiting spot market availability. The combination of tighter supply, moderate inventories and expectations of further mill-led price increases helped sustain the uptrend despite demand recovery remaining gradual.
Firm domestic prices support export offers: Improving domestic realisations continued to influence export markets. Indian HRC export offers to the EU increased by around $10/t w-o-w to $650/t FOB, supported by stronger domestic prices and limited allocations. Selective bookings for Q1CY’27 were reported, although higher offer levels continued to constrain buying interest.
Offers to the Middle East and Vietnam remained largely unchanged as mills prioritised domestic sales, where returns remained more attractive. As domestic prices continue to rise, mills are increasingly focusing on the local market, reducing pressure to pursue exports aggressively.
BF-rebar prices strengthen amid tight market conditions: Trade-level BF-route rebar prices increased by INR 2,000/t w-o-w to INR 61,000/t ex-Mumbai, reaching their highest level in recent months.
The market continued to benefit from improving project activity as monsoon-related disruptions eased across key regions and construction activities resumed. Market participants reported stronger enquiries and improved booking from infrastructure and construction projects, with buyers increasingly securing material amid expectations of further price increases.
A key driver behind the latest rally has been the exceptionally lean inventory position across the supply chain. Low stock levels at both mills and distribution channels have significantly tightened spot availability, enabling faster transmission of higher prices into the market.
Distributor procurement also improved as traders began replenishing inventories ahead of the festive season. Mills remained selective in accepting large forward bookings, contributing to a tighter project market and reinforcing upward price momentum.
Further supporting market sentiment, several producers introduced revised diameter premiums for smaller rebar sizes, reflecting tighter availability and efforts to improve product-level realisations.

IF rebar prices rise: W-o-w, IF-route rebar prices increased by INR 600-1,600/t across key regions, with Raigarh and Delhi witnessing the steepest rise of INR 1,600/t. However, buyers remained cautious and largely adopted a wait-and-watch approach. Trading activity remained limited due to Ganesh Chaturthi and Vishwakarma Puja.
Outlook
In the long steel segment, lean inventories, improving construction activity, stronger project bookings and distributor restocking are likely to sustain upward momentum. Project market availability may remain tight.
For flat products, recent mill price hikes, controlled spot availability and improving restocking activity should continue to support prices. Buyers are expected to remain active ahead of the festive season. However, for domestic HRC, the spread with landed cost of imports from the main destinations (factoring in safeguard duty) has significantly narrowed with sustained increases in domestic prices, thereby creating room for import demand. However, currently the majority of imports are as substrate products for feeding value-added exports under the export licencing scheme.
Export markets are also likely to remain supported by strong domestic realisations. While EU offers may stay high, mills are expected to continue prioritising domestic sales as long as local market conditions remain favourable.
Leave a Reply