- ICOMEX to introduce domestic ferro nickel benchmark
- Weda Bay resumes mining after four-month suspension
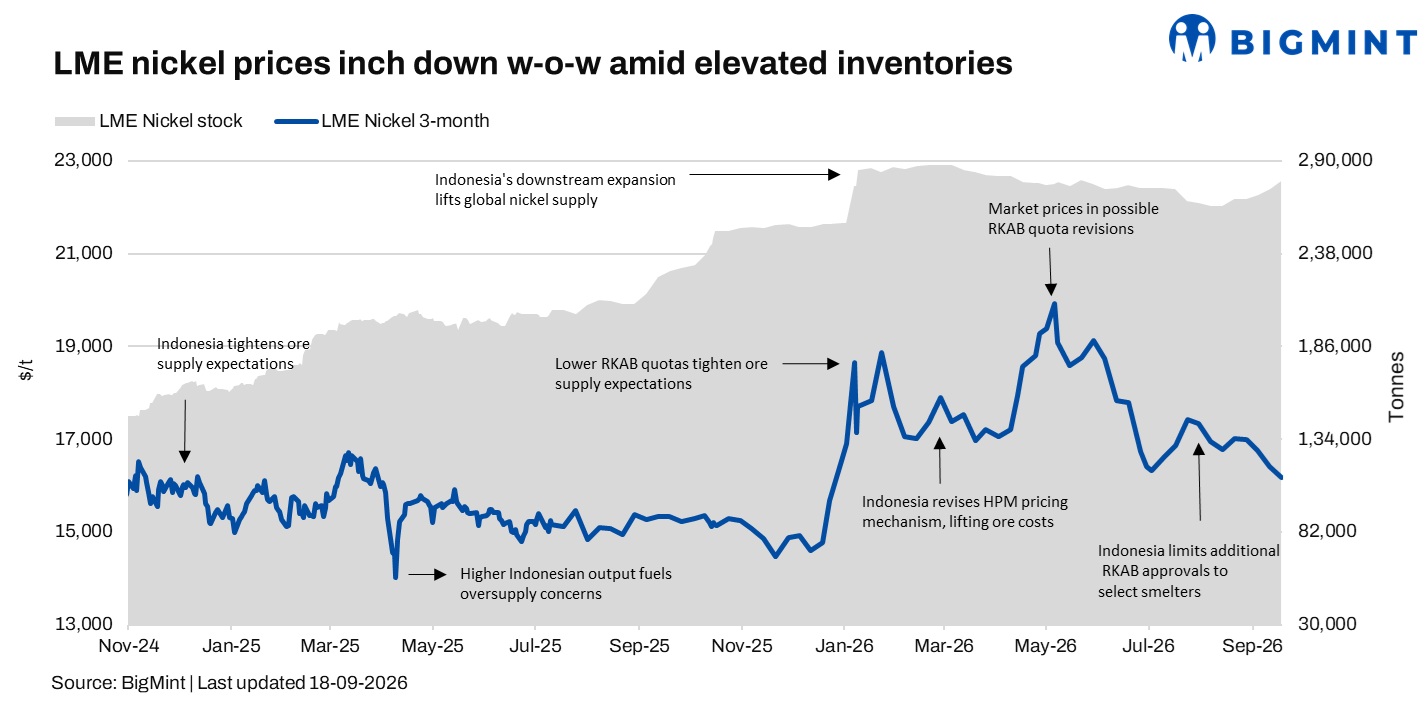
LME three-month nickel prices declined 1.5% w-o-w to $16,180/t on 18 September, 2026, from $16,415/t a week earlier, amid rising exchange inventories and expectations of higher Indonesian nickel supply. LME nickel inventories increased 3% to 278,826 t from around 270,768 t over the same period, indicating increased availability in the exchange system.
US Fed raises rates as inflation remains elevated
On the macro front, the key event was the US Fed’s September FOMC meeting. US August CPI rose 3.4% YoY, while the monthly increase accelerated to 0.4% from 0.1% in July. Core CPI rose 0.3% MoM. Meanwhile, August nonfarm payrolls increased by 162,000, while the unemployment rate remained at 4.1%. On 6 September, the Federal Reserve voted unanimously 12-0 to raise the federal funds rate by 25 basis points to 3.75%-4.00%, marking the first rate hike since July 2023. The Fed said inflation remained elevated and that the rate increase would support a more timely return to its 2% inflation goal.
Indonesia cuts nickel ore HPM for low-grade limonite
Indonesia has further revised its nickel ore benchmark price (HPM) formula, effective September 15, lowering key coefficients for low-grade limonite used as feedstock by HPAL (high-pressure acid leach) plants. The nickel correction factor for 1.2% nickel ore was reduced to 14% from 26%, bringing the benchmark closer to prevailing market prices. The revised HPM for 1.2% nickel ore stands at $24.89/wmt (wet metric ton), compared with $44.97/wmt under the previous formula, while actual delivered prices have been around $27/wmt.
The revision is expected to reduce miners’ royalty and tax burden and improve the economics of low-grade limonite mining, while potentially providing some relief to HPAL producers’ feedstock costs. However, the impact on actual ore prices is expected to remain limited in the near term, with market direction depending on RKAB quota releases, limonite availability and HPAL demand.
ICOMEX to introduce domestic nickel benchmark
Indonesia is also preparing to launch ICOMEX (Indonesia Commodity Exchange), with trading scheduled to begin on January 4, 2027. Tin and ferro nickel are expected to be among the initial commodities traded. The exchange aims to establish domestic benchmarks for strategic minerals, reduce reliance on international references such as the LME and improve price transparency.
The inclusion of ferro nickel could have implications for nickel and stainless steel raw material pricing across Asia, particularly if the exchange develops sufficient liquidity and participation to establish a widely accepted domestic reference.
Weda Bay restart adds to supply expectations
PT Weda Bay Nickel (PT WBN) has resumed mining operations after a four-month care and maintenance period following approval from Indonesian authorities. The restart is expected to be gradual as equipment, partners and personnel are redeployed and the company’s mining plan is re-established.
PT WBN’s initial 2026 RKAB allocation was 12 mnt, significantly below the 42 mnt approved for 2025. The lower allocation had resulted in the suspension of mining operations after the approved quota was expected to be exhausted. With operations now restarting, additional nickel ore could gradually return to the market, although the scale of the impact will depend on the final RKAB allocation and the pace of operational ramp-up.
Vale maintains investment focus despite cautious outlook
Meanwhile, PT Vale Indonesia plans to raise CAPEX to around $1.1 billion in 2027, with investments focused on HPAL projects and mine development. The company expects rising Indonesian nickel supply and price volatility to weigh on the market in the near term but maintains a positive medium- to long-term demand outlook, particularly from non-China EV markets, data centres and renewable energy.
Vale is expanding MHP production through HPAL projects at Pomalaa, Morowali and Sorowako. However, higher sulphur and sulphuric acid prices remain a cost challenge for HPAL operations.
Outlook
LME nickel prices are likely to remain sensitive to developments in Indonesian supply, exchange inventories and HPAL economics. The resumption of mining at Weda Bay, potential increases in RKAB allocations and continued HPAL expansion could add to ore availability, while the lower HPM may improve the economics of low-grade limonite supply. At the same time, rising inventories and cautious near-term demand could limit price recovery. Market direction will remain closely linked to Indonesian production policies, ore availability, HPAL demand and global nickel consumption.
Leave a Reply