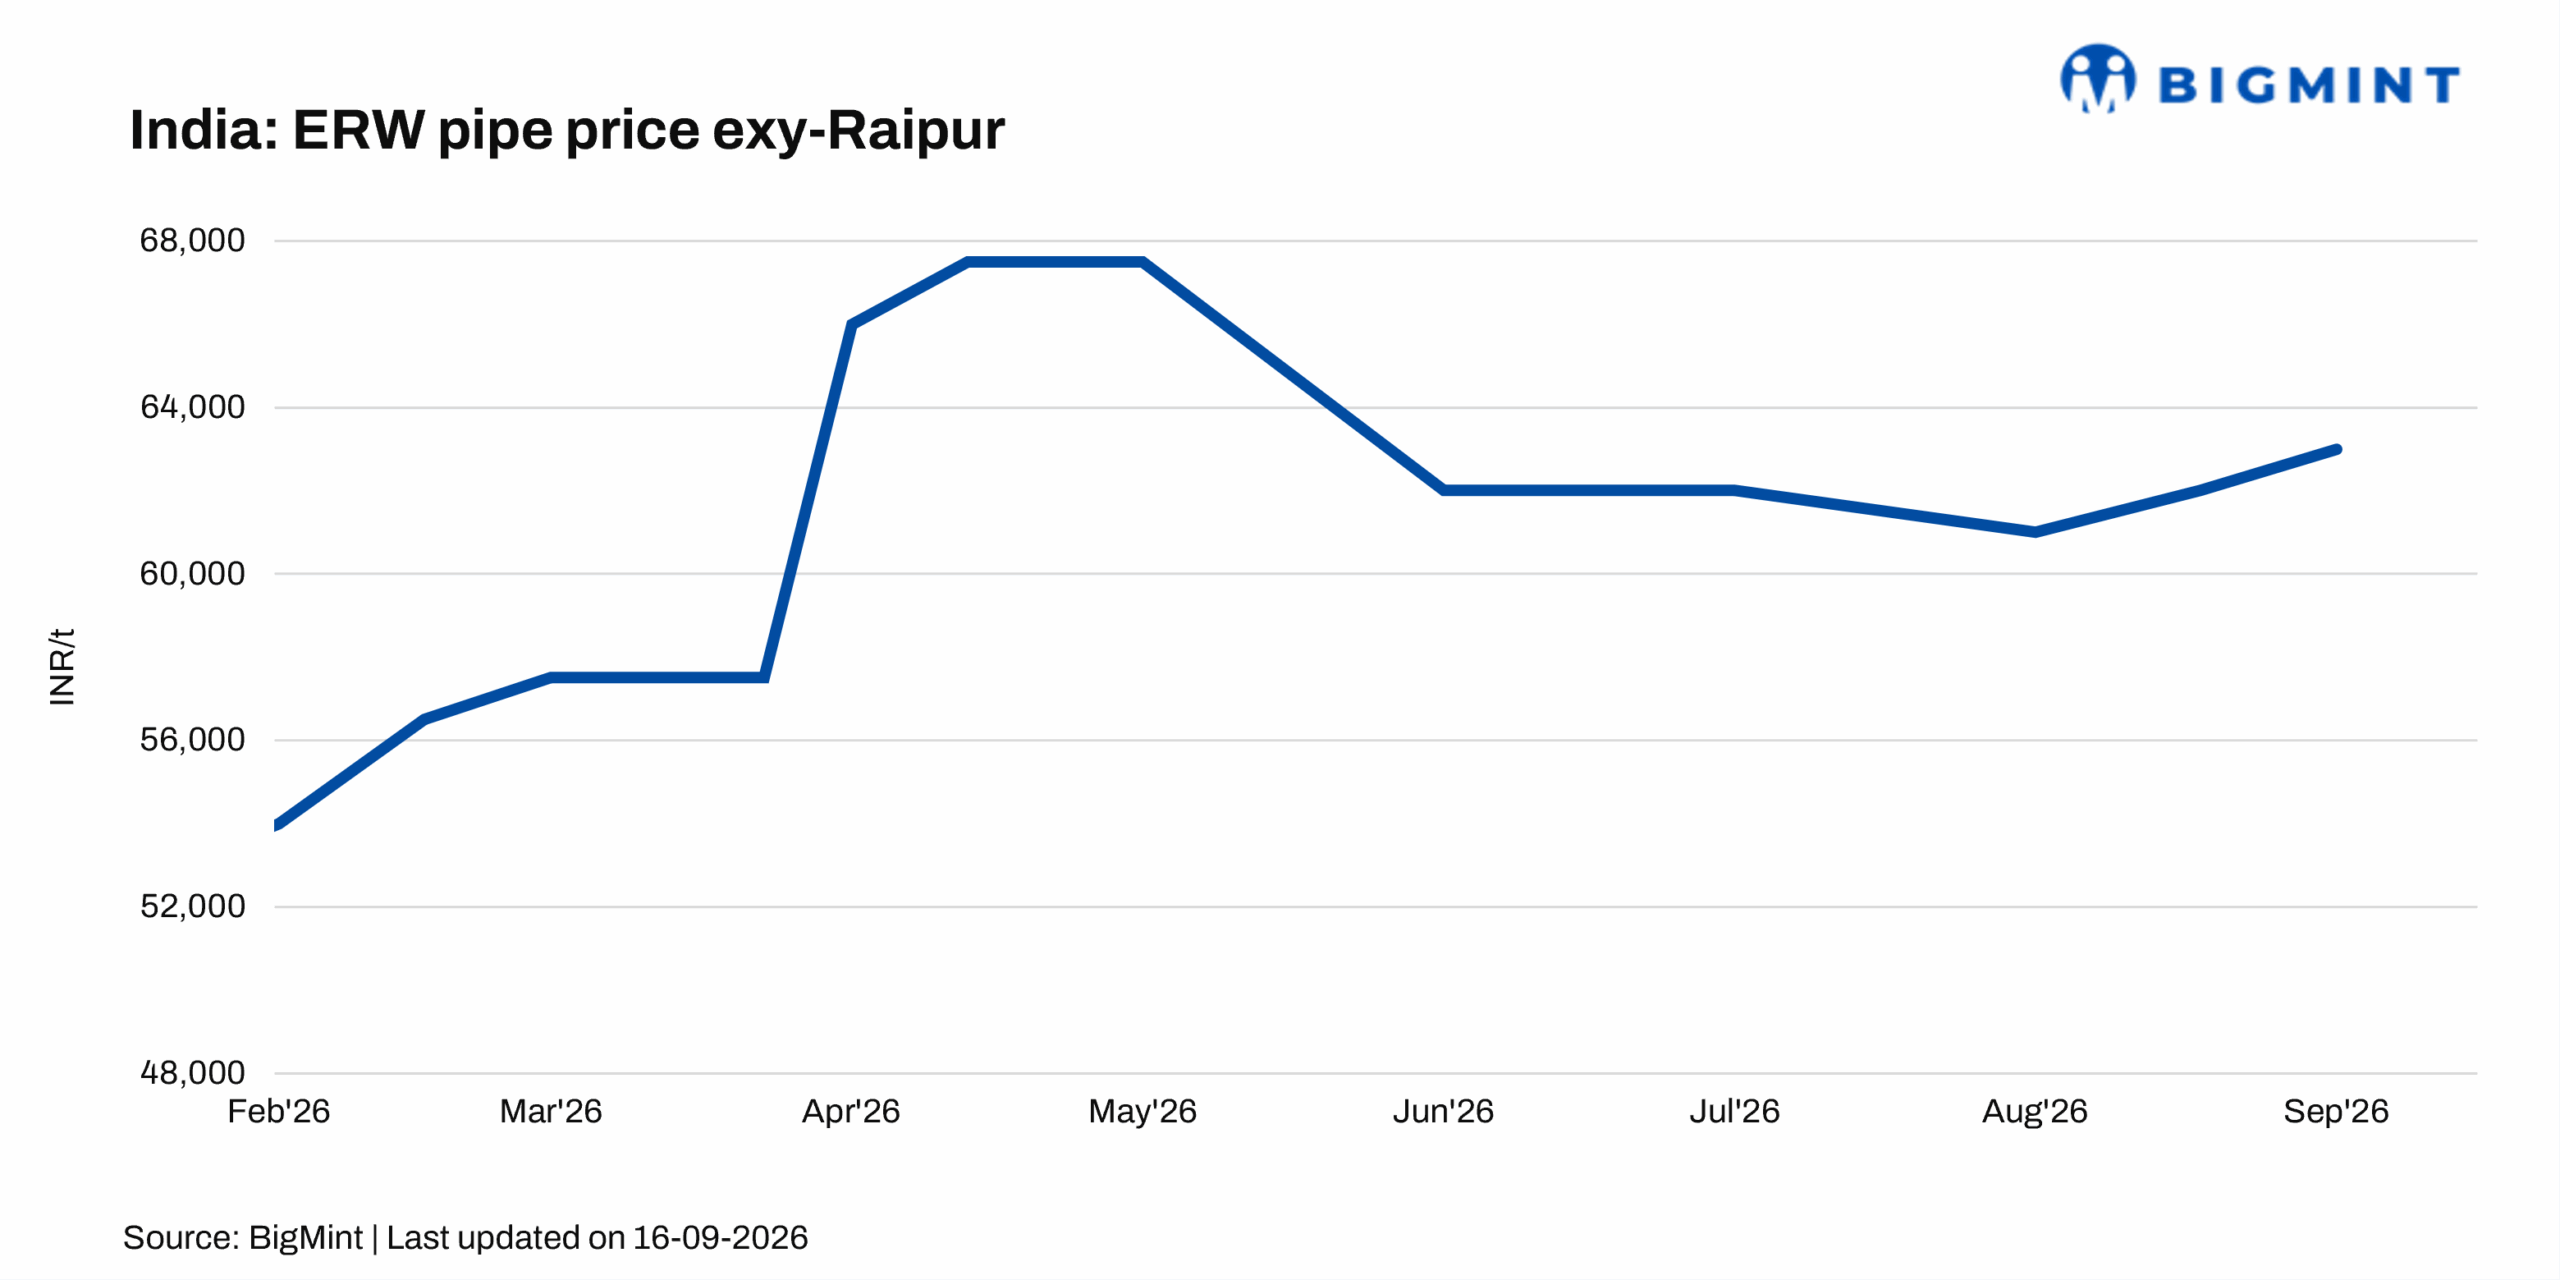
- Tight raw material supply prompts hike despite moderate demand
- Distributor prices also increase even as demand remains mixed
A major Indian producer of electric resistance welded (ERW) pipes has increased its list prices for round pipes by INR 1,000/t ($10/t) across key markets, effective 22 September, compared with its 15 September price list. The increase was supported by higher hot-rolled coil (HRC) costs and tighter raw material availability, while demand remained moderate with buyers largely procuring against immediate requirements.
The revised list prices for base-grade round pipes of 25-125 NB and 2.2-6 mm thickness stand at INR 66,500/t ($693/t) exy-Raipur and INR 68,500/t ($714/t) exy-Pune, excluding 18% GST.
Distributor prices edge higher
Distributor-level ERW pipe prices also increased in September, despite moderate-to-good demand across key markets.
In Raipur, weekly average prices rose by INR 800/t ($8/t) w-o-w to INR 64,500/t ($673/t) as of 16 September, from INR 63,800/t ($665/t) in the previous week.
In Pune, weekly average prices increased by INR 1,200/t ($12/t) w-o-w to INR 66,100/t ($689/t), compared with INR 64,900/t ($677/t) previously.
Buying activity remained largely requirement-driven. A market participant said, “People are in need-based procurement.”
Another participant said buyers were constrained, while suppliers are more in southern markets.
However, demand from large construction companies remained relatively steady. A market participant said, “Major construction companies who are into this are buying as they need it.”
HRC costs raise pipe production pressure
Higher HRC prices have emerged as a key cost driver for ERW pipe producers.
BigMint’s bi-weekly HRC benchmark for IS 2062, E250, 2.5-8 mm CTL increased by INR 2,000/t ($20/t) w-o-w to INR 63,700/t ($665/t) exy-Mumbai as of 16 September, from INR 61,700/t ($645/t) previously.
Major mills raised HRC prices during the week amid higher raw material costs and supply constraints. Mills have also been focusing on downstream products where demand has remained comparatively supportive, adding to cost pressure for pipe manufacturers.
The INR 2,000/t rise in the HRC benchmark is therefore providing producers with room to pass part of the higher input cost through pipe list prices.
Demand remains need-based
Despite higher prices, market activity has not weakened sharply, with procurement from construction-linked consumers continuing. However, buyers remain cautious about building inventories at elevated price levels, as demand has not improved significantly in line with the sharp rise in prices.
The current market is therefore characterised by a combination of firmer producer offers and requirement-based buying. Distributor prices have moved higher alongside mill list prices, although the increase has been more moderate in some markets.
Outlook
Market participants expect further price increases from mills during the next month if HRC prices continue to rise. Demand is expected to remain normal, with construction companies continuing to procure against requirements.
The direction of HRC prices and availability of raw materials are likely to remain key factors for ERW pipe prices through October. If input costs continue to increase, producers may seek further price revisions despite buyers maintaining a cautious procurement approach.
Leave a Reply