- Domestic scrap demand strong amid limited imports
- Scrap currently more economical than sponge iron
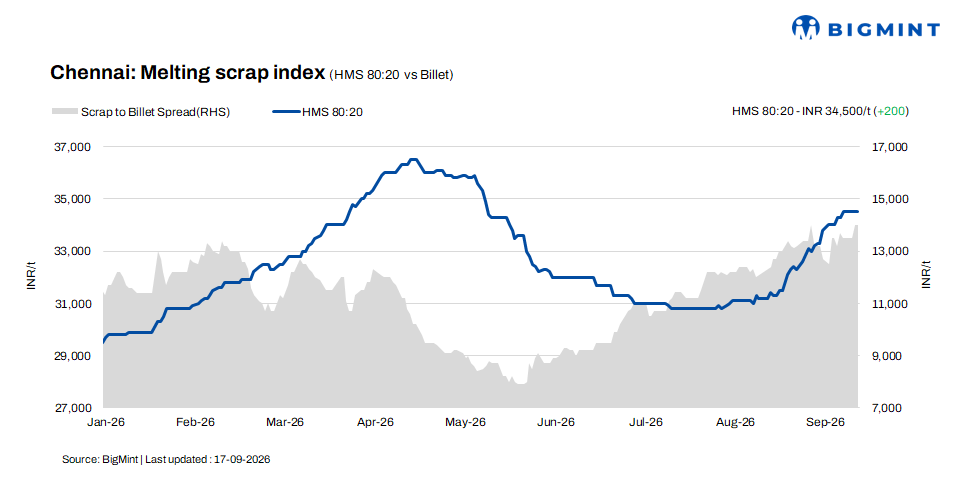
HMS (80:20) scrap prices in Chennai increased by INR 200/t w-o-w to INR 34,500/t on 17 September 2026, according to BigMint’s assessment, while remaining unchanged compared with the previous day. In the semi-finished steel segment, billet prices strengthened by INR 1,000/t w-o-w to INR 48,500/t, with no change recorded on a daily basis. Meanwhile, rebar prices in Chennai increased by INR 500/t w-o-w to INR 50,500/t exw, despite a INR 300/t d-o-d decline.
The sharp weekly gains across the steel value chain indicate strengthening market sentiment, supported by improved finished steel trading activity and stronger raw material demand.
Imported and domestic scrap price trends
Market participants reported that Australia-origin shredded scrap was offered at $380-385/t CFR Chennai, while HMS (80:20) was quoted at $360-365/t CFR. However, buyers were bidding $10-15/t lower than the prevailing offer levels. Buying interest remained subdued, as domestic scrap offers are currently more cost-effective compared to imported material, thereby limiting fresh bookings.

In the domestic market, HMS (80:20) scrap prices were quoted at INR 34,000-34,500/t for spot transactions with immediate payment, while extended credit-term deals were concluded at INR 34,500-35,000/t. Overall, market activity remained concentrated within the INR 34,000-35,000/t range, highlighting balanced demand-supply dynamics despite cautious procurement sentiment.
Market participants indicated that payment terms, procurement volumes, and mill-specific requirements continued to influence transaction prices, with premiums observed for deals involving longer credit periods.
Buyer-supplier sentiments
Market sentiment remains mixed despite firmer raw material prices. A mill representative said sponge iron prices have increased following a rise in iron ore and coal prices, but buyers are resisting current offer levels as scrap is currently more economical than sponge iron. Buyer bids are around INR 500-800/t below prevailing offers, limiting transaction activity.
Demand for billet and rebar remains moderate. Mills have nevertheless raised rebar offer prices over the past few days to protect conversion economics amid higher billet and raw material costs. At the same time, finished-steel inventories have increased by around 30% from normal levels, suggesting subdued downstream consumption. Elevated inventories and cautious buying are likely to keep near-term steel market sentiment under pressure.
According to a scrap supplier, HMS (80:20) scrap prices in Chennai are currently assessed at INR 34,000-35,000/t, with transaction levels varying based on payment terms and individual mill requirements. The supplier highlighted that buyers with higher scrap requirements, as well as those accepting delayed payment terms, have started offering higher bids to secure material. At the same time, reduced imported scrap bookings and tight domestic availability have created supply-side constraints in the market.
Consequently, sellers have been able to sustain firmer offer levels. The supplier added that increasing competition among buyers for limited domestic scrap availability is providing additional support to prices, despite overall demand remaining selective.
Outlook
Chennai scrap prices are likely to remain range-bound with a positive bias, as constrained domestic availability and subdued import bookings continue to support sellers’ price expectations. Selective buying at higher bids may lend further support to transaction levels. Meanwhile, firm billet and alternative metallic prices could limit downside. Moderate downstream demand is expected to cap significant upward movement. Overall, HMS (80:20) scrap prices are expected to remain stable to firm, with movements limited to around INR +/- 200-500/t in the coming days.
Leave a Reply