- Bellary C-DRI prices jump INR 800/t w-o-w
- South African RB2 prices rise further at Indian ports
Karnataka iron ore prices remained divergent across grades during 11-17 September, with higher-grade prices staying firm amid strong demand and limited availability, while lower-grade prices remained under pressure due to ample supply and weak buying interest. Firm sponge iron and finished steel prices, coupled with elevated coal costs, continued to support the overall market sentiment. However, buyers remained highly selective for lower-grade material, while scarcity of quality ore continued to push high-grade prices upward.
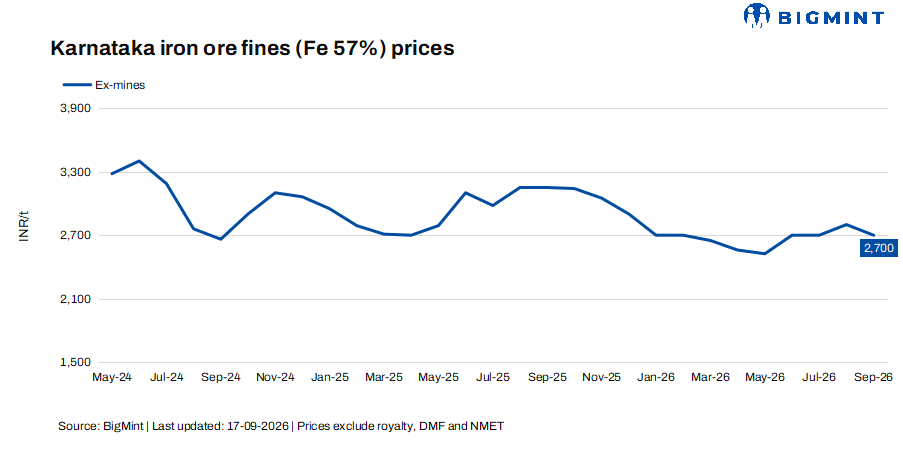
According to BigMint’s latest assessment, Fe 57% iron ore fines prices edged down w-o-w by INR 50/t ($0.5/t) to INR 2,700/t ($28/t) ex-mines. Demand remained weak as buyers continued to show limited preference for lower-grade material. Meanwhile, several miners were holding substantial quantities of lower-grade ore, further increasing availability in the market. Buyers remained selective and were reluctant to build inventories amid weak demand for this grade.
Meanwhile, Fe 62% fines prices remained stable w-o-w at INR 5,200/t ($54/t) ex-mines, supported by tight availability of quality ore. Market participants reported that buyers are increasingly willing to pay premiums for suitable high-grade material, while some consumers are shifting towards pellets due to difficulties in securing quality iron ore required for sponge iron production.
Auctions conducted during the week further highlighted the sharp grade-wise disparity in the market. NMDC’s auction witnessed a strong response for higher-grade Kumaraswamy material, with bids moving significantly higher amid a shortage of quality ore. In contrast, other miners continued to face difficulties in selling lower-grade material through auctions, while direct sales also remained subdued. Some miners holding higher-grade material are reportedly avoiding auctions and accumulating stocks amid expectations of stronger prices.
A Bellary-based buyer told BigMint that “we are not preferring NMDC’s auction because bids are going very high, so we will be thinking about buying from private miners.” The aggressive bidding in NMDC’s Kumaraswamy auction reflects the intense competition among buyers for limited high-grade material, despite elevated prices.
Rationale
- One (1) trade via e-auction was recorded for Fe 57% in this publishing window and was not taken into consideration. Hence, the T1 trade category was accorded 50% weightage.
- Thirteen (13) offers and indicative prices were reported, out of which twelve (12) were considered as T2 trades. These were accorded 50% weightage.
Supporting factors:
- C-DRI prices rise sharply by INR 800/t ($8/t) w-o-w in Bellary: Meanwhile, Bellary’s lump-based sponge iron (C-DRI) prices increased by INR 800/t ($8/t) w-o-w to INR 31,800/t ($332/t), supported mainly by a slight shortage of material in the market. The limited availability has provided sellers with stronger bargaining power, while rising input costs have further pushed up production costs. Higher prices of key raw materials, particularly iron ore-based inputs and other production essentials, have increased the cost of CDRI production. Despite the price increase, buying interest from steel mills remained relatively steady, allowing sellers to maintain firmer offers. Market participants expect prices to remain supported in the near term, provided raw material costs stay elevated and material availability remains relatively tight.
- Imported coal prices rise amid higher global costs: South African thermal coal prices at Indian ports strengthened further as of 17 September 2026, supported by tight domestic coal availability, limited South African cargoes and firm demand from overseas markets. Ex-Paradip RB2 (5,500 NAR) increased INR 100/t w-o-w to INR 13,300/t, while RB3 remained at INR 11,600/t. Ex-Vizag, RB2 rose INR 150/t w-o-w to INR 13,250/t and RB3 increased INR 50/t to INR 11,550/t. Buyers continued to enquire for imported coal as domestic availability remained constrained. Higher coal costs are keeping sponge iron production costs elevated and, in turn, providing support to finished steel and raw material prices.
Karnataka iron ore sales scenario (11- 17 September 2026)

Outlook
Lower-grade iron ore prices in Karnataka are expected to remain stable to slightly weak amid ample availability and subdued demand, while high-grade prices may move higher amid tight availability and strong buying interest. Elevated coal costs, firm sponge iron prices and supportive finished steel market sentiment are expected to keep the overall raw material market firm. Continued scarcity of quality ore could further intensify competition among buyers for high-grade material in the near term.
Leave a Reply