- Weak property demand deepens pressure on steel output
- Rising coke costs pressure steel mill margins
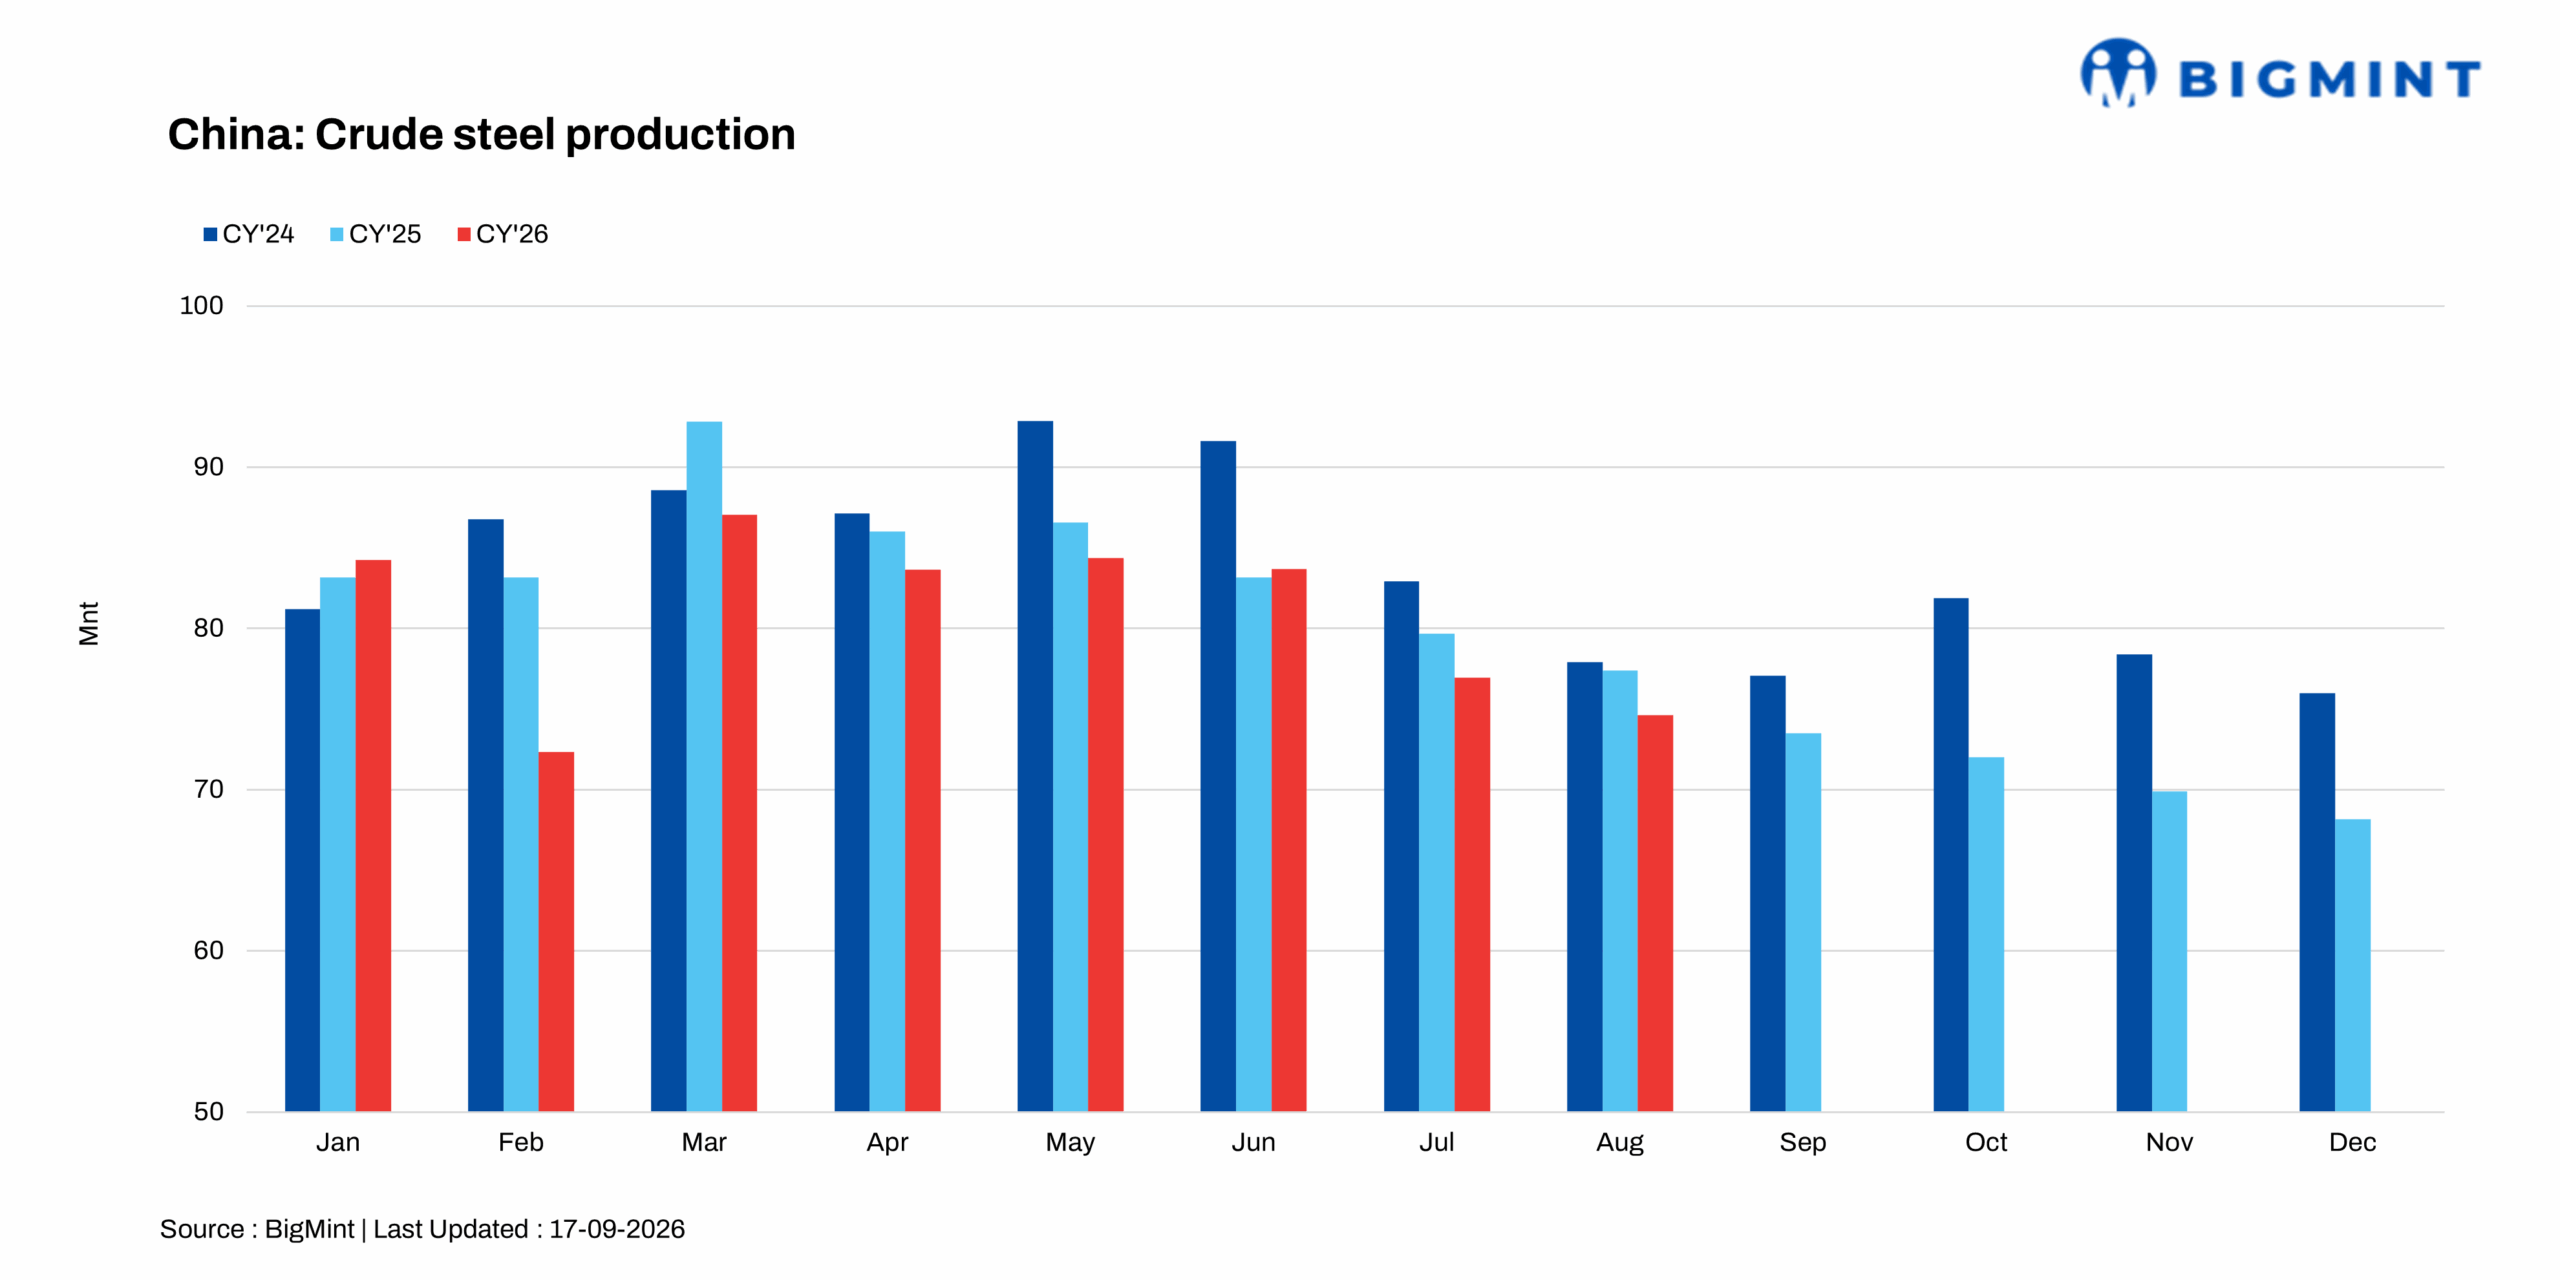
China’s crude steel production fell by 3.7% y-o-y to 74.61 million tonnes (mnt) in August 2026, according to data released by the National Bureau of Statistics (NBS). Average daily crude steel output stood at around 2.407 mnt, down by 3% m-o-m from around 2.48 mnt in July, reflecting a continued slowdown in steel production during the month.
Production cuts deepen in August
Steel production cuts became more prominent in August as large and medium-sized steelmakers reduced output amid weak domestic demand. Real estate development investment declined 19.9% y-o-y during January-August, remaining the key drag on steel consumption.
Infrastructure investment also declined slightly, while manufacturing investment recorded a modest y-o-y decrease. Weak project commencement and slower construction-payment collection further constrained demand for construction steel.
Demand from selected manufacturing segments, including new-energy equipment, shipbuilding and construction machinery, remained relatively moderate and provided some support to flat steel consumption. However, prolonged weakness in the property sector continued to pressure long steel products, particularly rebar and wire rod.
Higher raw material costs pressure mills
Coking coal and coke remained key cost pressures for steelmakers. Tight domestic coking coal supply, linked to safety regulations and capacity constraints, combined with production cuts at loss-making coke plants, triggered multiple rounds of coke price increases.
Meanwhile, high overseas iron ore shipments and relatively elevated port inventories kept iron ore supply ample, restricting significant price gains. The contrasting raw material trends kept steelmaking costs under pressure, particularly from the coke side.
Pig iron production also declines
China’s pig iron production fell by 3.5% y-o-y to 67.65 mnt in August. However cumulative pig iron production during January-August, decreased by 3.1% y-o-y to 563.4 mnt, compared with 495.77 mnt during January-July 2026, indicating continued weakness in blast furnace-based steelmaking activity.
Outlook
China’s steel market is likely to remain in a balancing phase through September as mills weigh domestic demand against elevated coke costs. Lower crude steel output may help contain supply pressure, but price and margin recovery will depend on construction activity and fresh order flows.
The property sector is expected to remain the main constraint on long steel demand, while manufacturing and selected downstream segments may offer some support to flat steel consumption. If peak-season construction activity remains subdued, buyers may continue to adopt a cautious restocking approach.
Elevated coke prices could keep steelmaking costs high and pressure margins if finished steel prices remain weak. Exports may provide an outlet for surplus material, although overseas buying interest and trade-policy developments could limit this support.
Leave a Reply