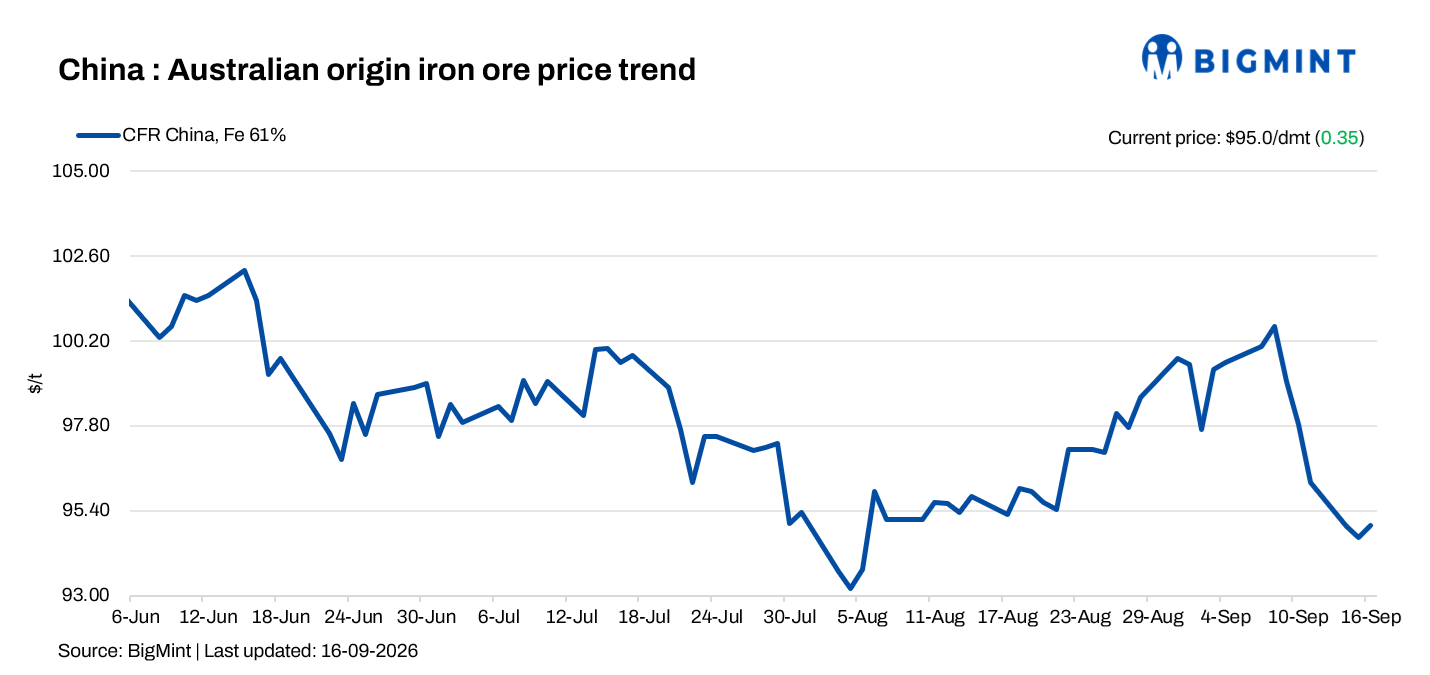
- Uncertainty surrounding Port Hedland operations support rise
- Weak mill margins, steel production cut concerns cap gains
Iron ore fines (Fe 61%) spot prices increased marginally by 0.35/dry metric tonne (dmt) d-o-d to around $95/dmt CFR China on 16 September 2026. China’s iron ore port inventories increased after declining for four consecutive days, suggesting some improvement in replenishment demand following the recent price correction. However, physical market activity remained subdued as mills continued to face weak margins
On the supply side, uncertainty surrounding Port Hedland operations provided an additional market factor. Workers have sought compulsory arbitration after wage negotiations failed to reach an agreement, keeping the possibility of further industrial action in focus. However, there has been no significant impact on shipments so far. As per reports, mills had begun restocking, with some buyers looking to rebuild and raise inventory levels.
However, the broader market tone remained cautious, with concerns over potential steel production cuts and the strength of post-holiday restocking keeping sentiment under pressure. Any reduction in blast furnace output could moderate demand for lump ore, despite its continued importance in steelmaking. With inventories also expected to rise, market participants saw limited fundamental scope for a sustained recovery in lump prices in the near term.
Meanwhile, weaker-than-expected Chinese consumption and investment data released this week increased expectations of further policy support from Beijing for economic activity. Ferrous futures also received some support as traders assessed that expectations of a US Federal Reserve rate increase had largely been incorporated into prices.
DCE iron ore futures remain under pressure
January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) gained RMB 4/tonne (t) ($0.6/t) to RMB 712/t ($106/t) on 16 September, from RMB 708/t ($106/t) on 15 September. The marginal increase offered little change to the broader market outlook, which remained cautious amid subdued steel demand, production-cut concerns and uncertainty over the pace of inventory replenishment.
Leave a Reply