- Lower production keeps concentrate supply under pressure
- Old order execution limits sellers’ fresh market participation
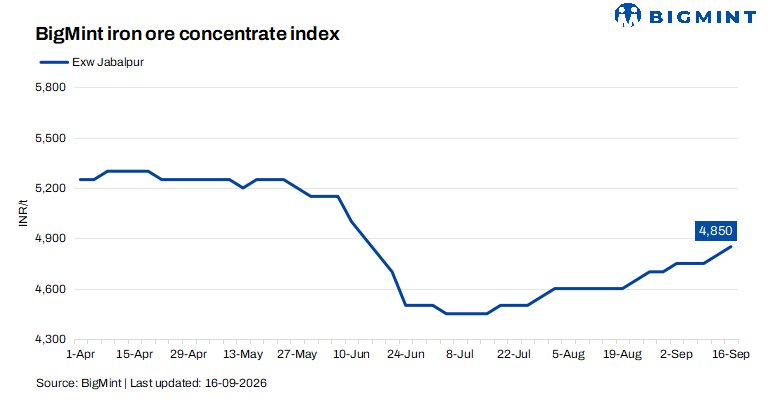
India’s iron ore concentrate prices remained firm during the assessment period, supported by higher pellet prices, stable Odisha iron ore prices and limited availability of fresh material amid continuous monsoon disruptions. BigMint’s bi-weekly assessment for Fe 62% concentrate edged up by INR 50/t ($0.5/t) to INR 4,850/t ($51/t) ex-works, while Fe 63% concentrate offers were heard at around INR 5,200/t ($54/t). Some sellers were also heard offering Fe 62% material at around INR 5,000/t ex-works.
Trading activity remained relatively good during the week, with buyers showing stronger interest in high-grade concentrate. More deals were heard for Fe 63% material compared with Fe 62%, as buyers continued to prefer higher-grade material amid concerns over availability. Some transactions were also under discussion, although buyers remained cautious about committing to large volumes at current price levels.
The market continued to receive support from higher pellet prices and stable iron ore prices in Odisha. Firm sponge iron and billet prices, along with stronger steel realisations, have improved the overall sentiment across the steel raw-material chain. This has encouraged concentrate sellers to maintain firm offers, while buyers are largely restricting purchases to immediate requirements.
On the supply side, continuous rainfall and monsoon-related disruptions have significantly affected mining, production and transportation activity in the region. Production has remained below normal levels, resulting in limited availability of fresh material. Several sellers are still engaged in executing previously committed orders, with delayed dispatches keeping them away from taking fresh orders or quoting aggressively for new business.
Some sellers with pending old orders are continuing to supply material at previously agreed prices despite the improvement in the market. As these orders have not yet been fully dispatched, sellers are waiting for their commitments to be completed before revising offers for fresh business. This has further restricted the availability of freely offerable material and helped prices remain supported.
However, buyers have also become cautious at higher levels and are avoiding bulk procurement, preferring to purchase only against immediate requirements. This has created a balanced market, where tight availability and firm seller expectations are countered by selective buying. A Jabalpur-based seller told BigMint, “Bids are still on the lower side. We are waiting for OMC’s auction base price; till then, we will remain in a wait-and-watch mode for 4-5 days.” Market participants are now closely watching the upcoming OMC auction, with its base price expected to provide a clearer indication of the next price direction.
Rationale
- Two (2) trade was recorded in this publishing window, which was taken into consideration. Therefore, this category received a 50% weightage.
- Nine (9) offers and indicative prices were heard, in which eight (8) are taken into consideration as T2 trades, receiving 50% weightage.
Factors shaping market dynamics
- PELLEX rise by INR 250/t ($2.5/t) w-o-w: PELLEX, BigMint’s bi-weekly domestic pellet index for Raipur, increased by INR 250/t ($2.5/t) w-o-w to INR 11,250/t DAP Raipur on 15 September 2026, supported by firm sponge iron and billet prices, higher raw-material costs and stronger steel realisations. Sellers raised offers by around INR 200-300/t to INR 11,000-11,100/t, while buyers remained selective and focused on immediate requirements. The firm pellet market continues to provide support to concentrate prices.
- Odisha iron ore prices remain stable w-o-w: BigMint’s Odisha Fe 62% iron ore fines assessment remained unchanged w-o-w at around INR 5,100/t ($54/t) ex-mines in the week ending 12 September 2026. Buyers remained in a wait-and-watch mode and continued to procure mainly against immediate requirements. Frequent rainfall disrupted mining and transportation in parts of the state, restricting availability; however, subdued spot buying prevented these supply constraints from pushing prices higher.
Outlook
Iron ore concentrate prices are expected to remain firm with a slight upward bias in the near term, supported by higher pellet prices, stable Odisha iron ore prices and continued monsoon-related supply constraints. However, cautious buying and limited bulk procurement could restrict a sharper price rise. The upcoming OMC auction and its base price will remain the key market trigger, while improved availability after the monsoon could determine whether the current firm sentiment sustains.
Leave a Reply