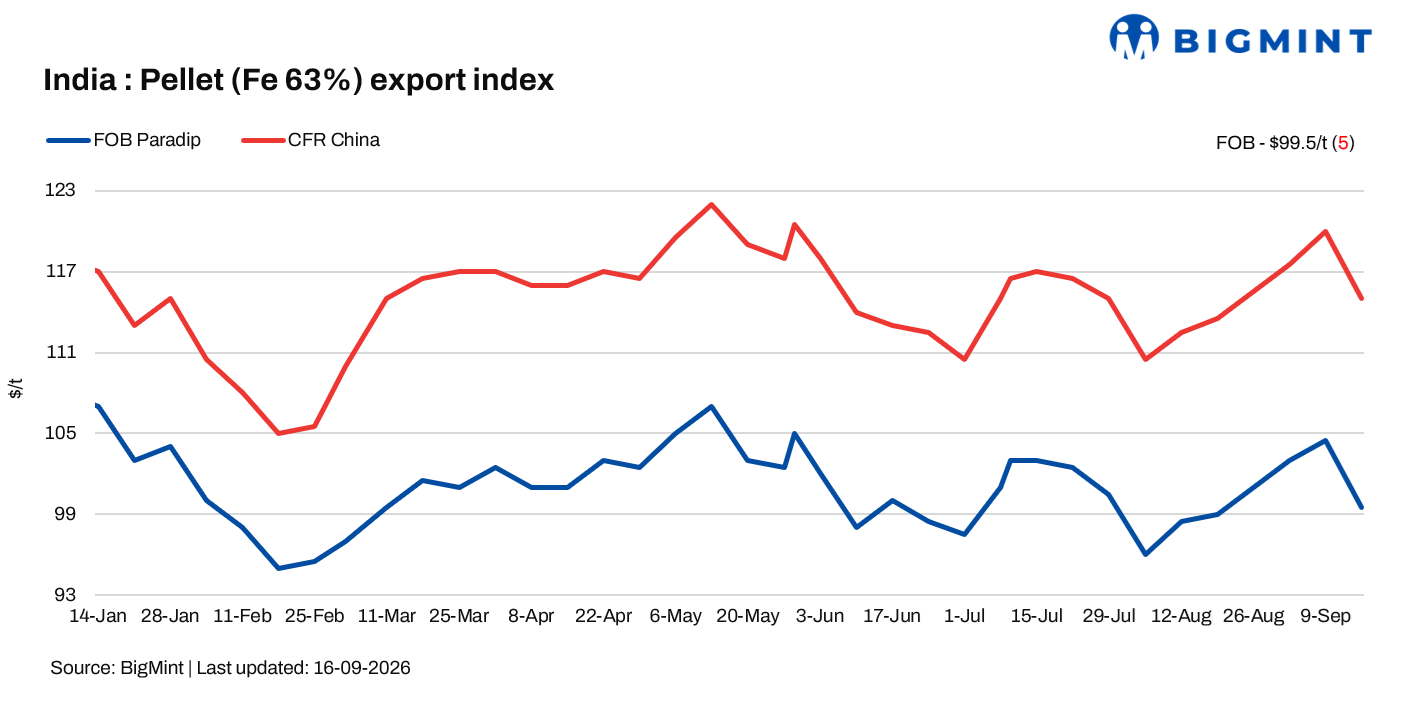
- Weak Chinese buying and uncertainty weigh on export sentiment
- Firm domestic realisations keep Indian sellers away from export market
BigMint’s India pellet export index declined by around $5/t w-o-w to $99.5/t FOB East Coast on 16 September 2026, equivalent to around $115/t CFR China. The decline was largely driven by a $4-5/t correction in the global Fe 61% iron ore fines benchmark from past week level, while subdued spot buying from Chinese mills further weighed on pellet export sentiment.
Chinese pellet inventories at 34 major ports declined marginally to around 5.69 million tonnes (mnt), compared with 5.82 mnt a week earlier. While lower inventories offer some underlying support to pellet demand, aggressive restocking has yet to emerge as several Chinese mills remain cautious amid uncertainty over potential steel production cuts.
Rationale
- Zero (0) confirmed deals from India’s east coast were recorded in this publishing window for T1 trade, and, therefore, this category was allotted 0% weightage for today’s price calculations. Click here for the detailed methodology.
- Ten (10) bids, offers, and indicative prices were heard, of which all were considered for the calculation of the index and given the balance 100% weightage.
Market updates
Chinese mills remained cautious on fresh pellet procurement during the week, with buyers adopting a largely need based approach amid uncertainty over upcoming steel production curtailments. A Chinese buyer said mills are avoiding aggressive purchases until there is greater clarity on operating rates.
The lower pellet inventories provide some underlying support to demand, particularly as relatively high fines prices had previously improved the cost competitiveness of pellets. However, this has not yet translated into meaningful restocking. Rising coking coal costs could also encourage mills to optimise their raw-material mix, but buying remains largely need-based.
Indian sellers, meanwhile, are largely out of the export market and continue to prioritise domestic sales. Domestic pellet realisations remain more than INR 1,700/t higher than equivalent export realisations on an ex-plant basis, leaving little incentive for producers to divert material overseas.
Pellet availability is also becoming tighter in some producing regions, with producers committing near-term output to domestic buyers. Tight iron ore lump availability has further constrained raw-material flexibility, while higher crude oil prices have added to freight and logistics costs, putting additional pressure on export economics.
A domestic pellet seller said, “At current export indications, there is simply no incentive to divert material overseas. Domestic buyers are offering significantly better realisations, while raw-material availability itself remains tight.”
Some tenders are expected to open from the western coast. However, market participants indicated that these are more likely to be prioritised for domestic requirements, with the likelihood of concluding export business remaining low at current price levels.
International traders are currently targeting around $113-114/t CFR China for Indian-origin pellets.
An international trader said buyers are still testing the market around $113-114/t CFR, but Indian suppliers are finding it difficult to match these levels amid firm domestic prices. Another market participant said the gap between buyer ideas and seller expectations remains too wide for meaningful export business.
Meanwhile, some traders expect pre-holiday restocking ahead of China’s October holidays to provide temporary support to port-side pellet buying demand. However, participants remain cautious about the sustainability of such demand given uncertainty over Chinese steel production.

Domestic vs export market
Pellet export realisations for Fe 63% were recorded at INR 7,300-7,400/t ($76-77/t), dropping by INR 400/t this week, while domestic realisations (Fe 62.5%) edged up by INR 500/t w-o-w to INR 9,200/t ($97-98/t) exw. Thus, the gap widened to INR 1,850/t making it better than last week, against 1,400/t.
Factors impacting pellet exports
Chinese iron ore fines prices plunge down w-o-w: The benchmark iron ore fines Fe 61% index dropped w-o-w by $6/dmt to $95/dmt CFR China on 15 September, hitting a 3-week low. The recovery was supported by stronger physical buying in China, expectations of higher freight costs and tighter seaborne availability from major exporters. Uncertainty over future cargoes from an Australian miner also kept market participants cautious and provided support to prices. Chinese physical market activity picked up significantly during the day, particularly at ports, where trading volumes increased sharply from the previous session.
DCE iron ore futures drop w-o-w: Iron ore futures on the Dalian Commodity Exchange (DCE) for the January 2027 contract settled at RMB 708.5/t on 15 September, indicating persistent sluggishness for export trades.
Outlook
Indian pellet export availability is likely to remain limited in the near term as sellers continue to favour domestic sales. Weak Chinese buying, potential steel production cuts and the wide domestic-export spread are expected to keep export activity subdued.
While some western coast tenders may emerge and pre-holiday restocking could improve Chinese buying, a meaningful recovery in Indian pellet exports is likely to require higher international prices that can bridge the gap between export and domestic realisations.
Leave a Reply