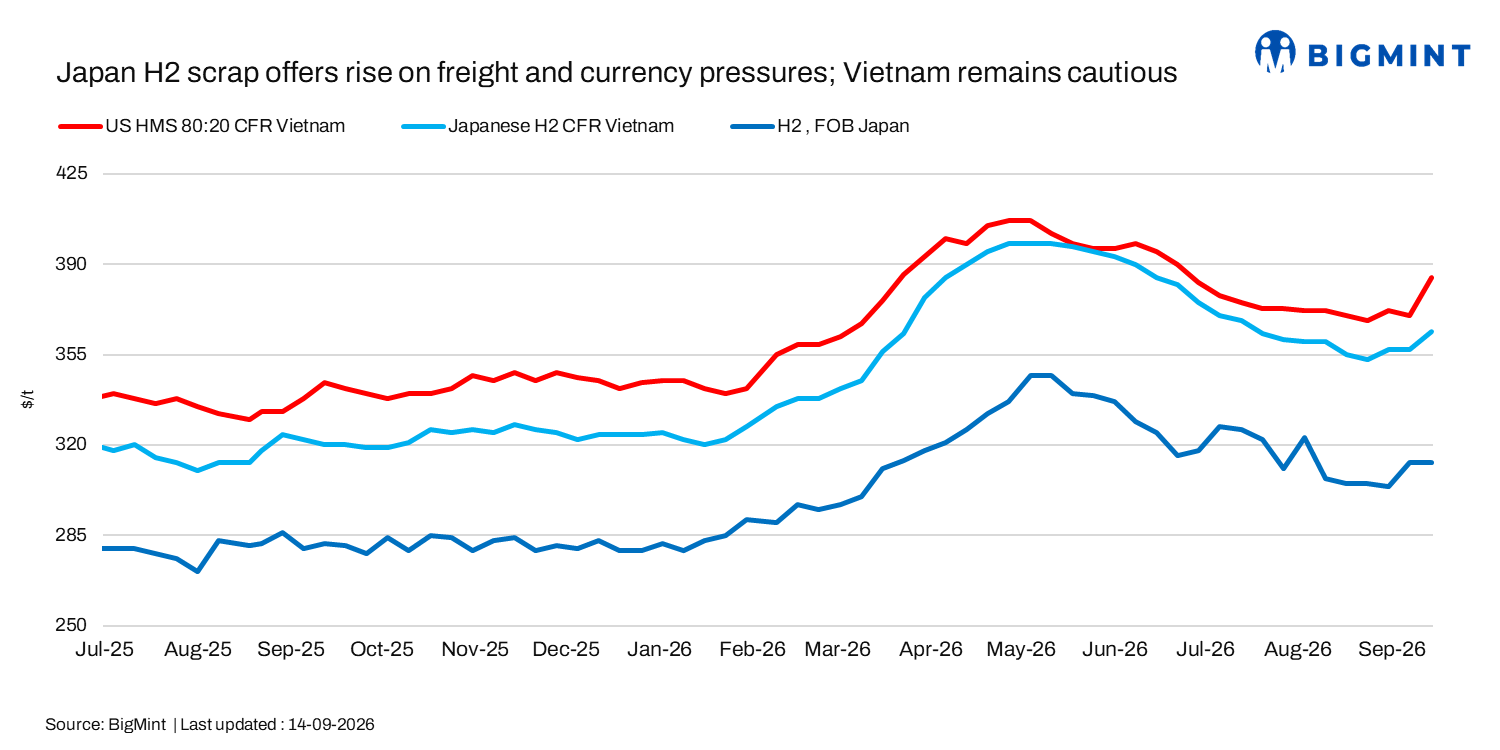
- Tight deep-sea scrap availability supports higher H2 offers
- Vietnamese mills resist higher offers amid weak rebar prices
Japan’s H2 ferrous scrap export prices moved higher during the assessment week ended 14 September, supported by a stronger yen, higher ocean freights, and tight deep-sea scrap availability. However, buying interest in Vietnam remained cautious, as downstream rebar prices showed limited improvement and mills were reluctant to fully accept higher offers.
Weekly assessments
- Japanese H2 scrap was at $365/t CFR Vietnam, up by $8/t w-o-w.
- Japanese H2 scrap was at JPY 48,300/t ($313/t) FOB Tokyo Bay, down by JPY 500/t ($3/t) w-o-w.
- US-origin HMS 80:20 bulk stood at $385/t CFR Vietnam, up by $15/t w-o-w.
Japan
Japan’s September Kanto-Tetsugen export tender concluded at around JPY 48,100/t ($312/t) FAS for a 20,000-t H2 cargo. The winning price was lower in JPY terms than the previous month but higher in US dollar terms due to the stronger JPY.
Following the tender, Japanese H2 export offers to Vietnam increased to around $365-375/t CFR, compared with approximately $360/t in early September. A market participant said the stronger JPY and higher freight costs were key factors behind the rise in supplier offers.
Domestic H2 collection prices remained largely rangebound at JPY 46,000-47,000/t ($299-305/t). H2 at JPY 48,300/t ($313/t) FOB Tokyo Bay, down JPY 500/t ($3/t) w-o-w.
Vietnam
Vietnam’s imported scrap market remained subdued despite higher supplier offers. Japanese H2 was offered at $365-375/t CFR Vietnam, while high-grade bulk scrap reached around $400/t CFR, up from $390-395/t a week earlier.
US-origin HMS 80:20 offers rose by $15/t w-o-w to around $390/t CFR Vietnam, supported by tight US supply and stronger demand from other major markets, particularly Turkiye.
However, Vietnamese buyers were unwilling to follow the sharp price increases. Indicative bids for Japanese H2 were heard at $355-360/t CFR, while deepsea HMS bids were around $375-380/t CFR. Mills remained cautious as domestic long-steel prices were largely unchanged and construction demand had yet to strengthen significantly.
Outlook
Japanese scrap prices are expected to remain supported by firm supplier sentiment, the appreciation of the yen, and tight deepsea availability. However, cautious Vietnamese buying and weak steel demand could limit further gains. Market activity may improve later in September as mills return to the market and restocking requirements emerge.
Leave a Reply